
We read your photo as:
18.1 Draft the relevant journal entry to adjust the Trading stock account. 10.18.2 Post to the following accounts in the General Ledger: (a) Trading stock (b) Trading stock deficit 10.18.3 Show the effect of the adjustment entry on the Accounting equation.
ScanSolve AI Answer
It looks like you've sent the same image again. This image contains a worked solution for a trading stock surplus, followed by Task 10.18 (which we've already completed).
I'll explain the worked solution for the Trading Stock Surplus shown in the image.
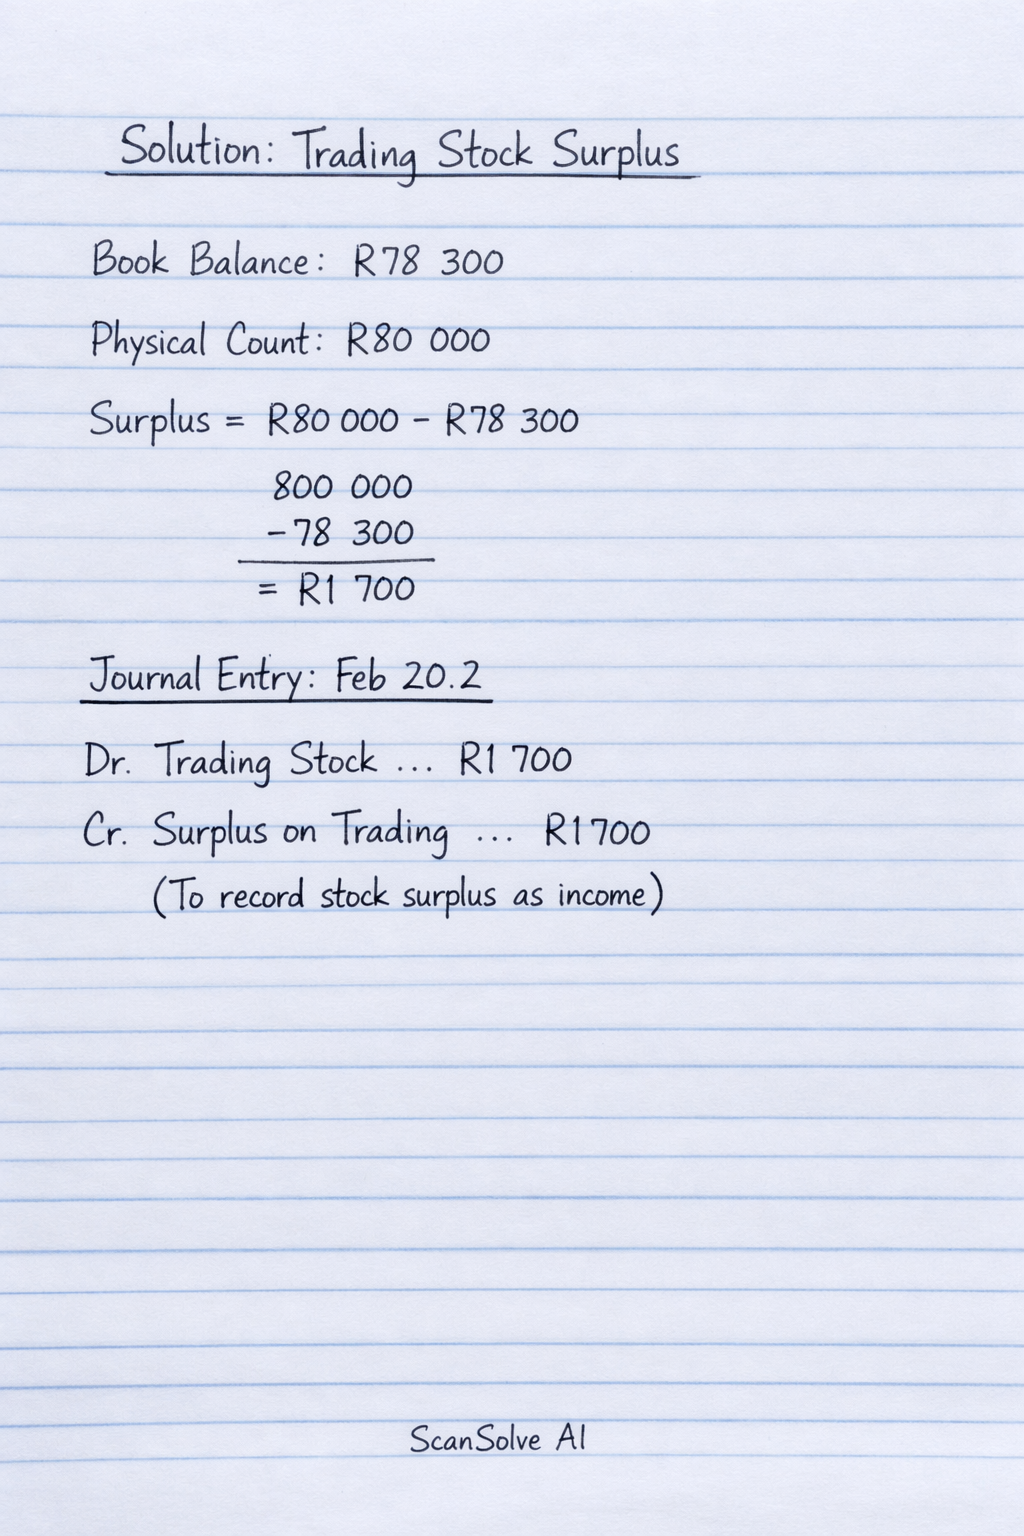
Solution: Trading Stock Surplus
This solution demonstrates how to account for a trading stock surplus, which occurs when the physical count of stock is higher than the book balance.
Information from the image:
- Book Balance (before adjustment): R78 300
- Physical Count (implied by final balance): R80 000
- Trading Stock Surplus: R80 000 - R78 300 = R1 700
General Journal Entry - February 20.2
The journal entry records the increase in trading stock and the recognition of the surplus as income.
| J/V | D | Details | Fol | Debit | Credit |
|---|---|---|---|---|---|
| 1 | 28 | Trading Stock | B7 | 1 700 | |
| Trading Stock Surplus | N15 | 1 700 | |||
| Trading stock surplus as identified by physical count |
- Debit Trading Stock (B7) R1 700: This increases the asset account for trading stock to reflect the actual amount on hand.
- Credit Trading Stock Surplus (N15) R1 700: This recognizes the surplus as an income, as the business has more stock than expected.
General Ledger of Calc Traders
(a) Trading Stock Account (B7)
| Dr | 20.2 | B7 | Cr | ||||
|---|---|---|---|---|---|---|---|
| Feb 28 | Balance | b/d | 78 300 | Feb 28 | Balance | c/d | 80 000 |
| Feb 28 | Trading Stock Surplus | GJ1 | 1 700 | ||||
| 80 000 | 80 000 | ||||||
| Mar 1 | Balance | b/d | 80 000 |
- The opening balance of R78 300 is debited.
- The R1 700 surplus from the General Journal is debited, increasing the stock.
- The account is balanced, showing a closing balance of R80 000, which becomes the opening balance for the next period.
(b) Trading Stock Surplus Account (N15)
| Dr | 20.2 | N15 | Cr | ||||
|---|---|---|---|---|---|---|---|
| Feb 28 | Trading Stock | GJ1 | 1 700 | ||||
- The R1 700 surplus from the General Journal is credited, recognizing it as income. This account will typically be closed off to the Profit and Loss account at year-end.
Effect of the adjustment entry on the Accounting equation
| ASSETS | = | OWNER'S EQUITY | + | LIABILITIES | |
|---|---|---|---|---|---|
| Adjustment | + R1 700 | = | + R1 700 | + | R0 |
- Assets: Trading Stock (an asset) increases by R1 700.
- Owner's Equity: Trading Stock Surplus is an income, which increases profit and therefore increases Owner's Equity by R1 700.
- Liabilities: There is no effect on liabilities.
To continue with Task 10.27, I still need the details from Task 10.22 (Caxio Supplies). Please send that image when you're ready!
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp