
We read your photo as:
What is allowable deduction in the computation of adjusted profit (Section 20 of CITA)?
ScanSolve AI Answer
Answer
Step-by-step solution
4 stepsTo compute the adjusted profit for Fortunes Nigeria Limited for the year ended 31 December 2007, we start with the net profit as per the financial statements and make adjustments for expenses that are either disallowed or allowed for tax purposes under Section 20 of the Companies Income Tax Act (CITA).
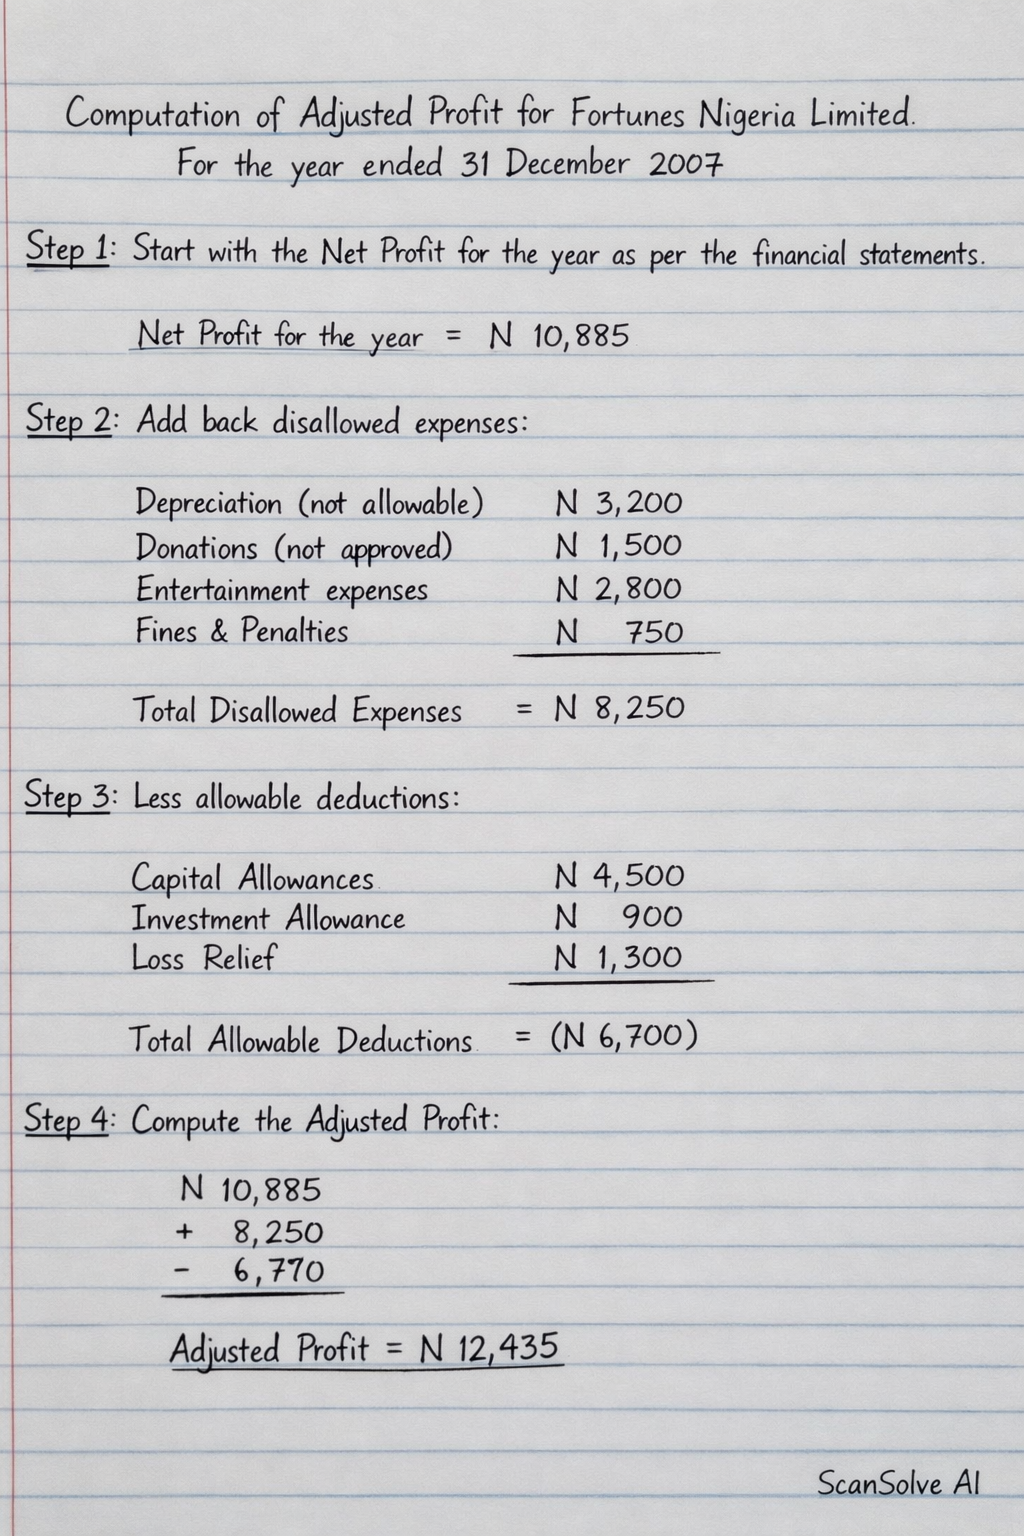
Computation of Adjusted Profit for Fortunes Nigeria Limited
For the year ended 31 December 2007
Start with the Net Profit for the year as per the financial statements.
Add back expenses that were deducted in the financial statements but are disallowed for tax purposes when computing adjusted profit.
- Depreciation: This is an accounting provision for the wear and tear of assets and is not an allowable expense for tax purposes. Instead, capital allowances are granted separately.
- Gifts and donations: Generally, gifts and donations are not allowable deductions in the computation of adjusted profit. While donations to approved bodies may be deductible from assessable profit (subject to limits), they are added back for adjusted profit calculation.
Calculate the total disallowed expenses to be added back.
Compute the Adjusted Profit by adding the total disallowed expenses to the Net Profit.
The adjusted profit for Fortunes Nigeria Limited for the year ended 31 December 2007 is .
Try one yourself
A new problem that tests the same skill.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp