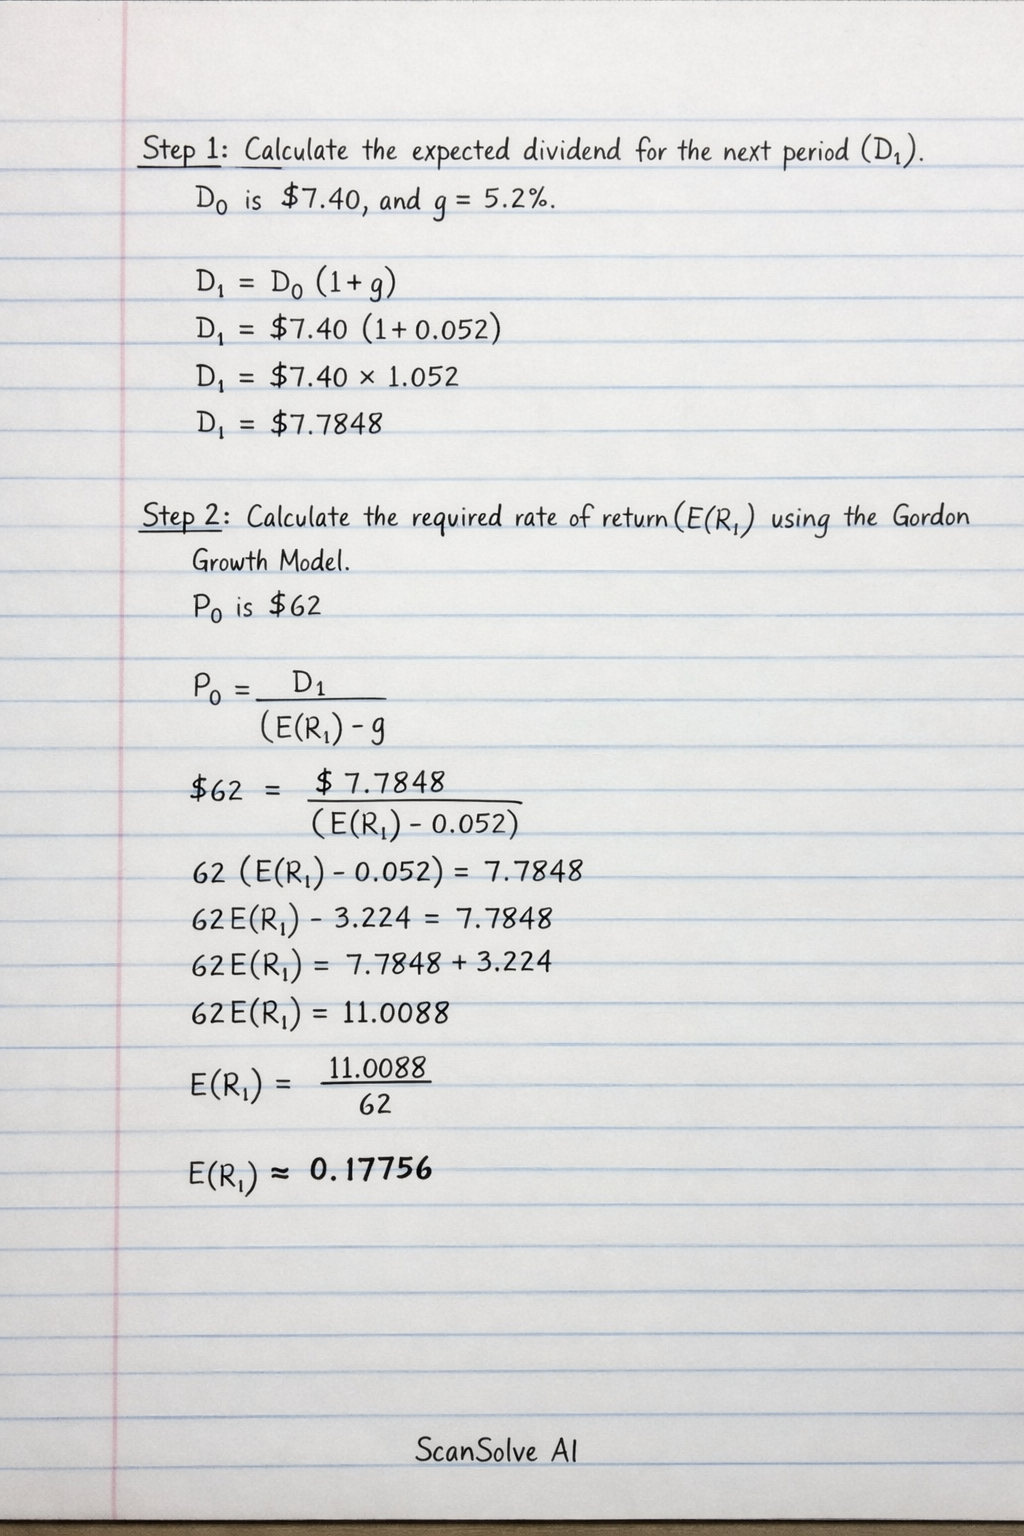We read your photo as:

Calculate the beta coefficient for Nova Orbit Ltd. using the provided financial data and CAPM.

Business/Management

ScanSolve AI Answer

Answer

1.13\text{1.13}

Step-by-step solution

3 steps
  1. Calculate the expected dividend for the next period (D1D_1).

    The current dividend (D0D_0) is \7.40,andthegrowthrate(, and the growth rate (g$) is 5.2%.

    D1=D0(1+g)D_1 = D_0 (1 + g)

    D1=$7.40(1+0.052)D_1 = \$7.40 (1 + 0.052) D1=$7.40×1.052D_1 = \$7.40 \times 1.052 D1=$7.7848D_1 = \$7.7848

  2. Calculate the required rate of return (E(Ri)E(R_i)) using the Gordon Growth Model.

    The current share price (P0P_0) is \62$.

    P0=D1E(Ri)−gP_0 = \frac{D_1}{E(R_i) - g}

    $62=$7.7848E(Ri)−0.052\$62 = \frac{\$7.7848}{E(R_i) - 0.052}

    62(E(Ri)−0.052)=7.784862 (E(R_i) - 0.052) = 7.7848 62E(Ri)−3.224=7.784862 E(R_i) - 3.224 = 7.7848 62E(Ri)=7.7848+3.22462 E(R_i) = 7.7848 + 3.224 62E(Ri)=11.008862 E(R_i) = 11.0088 E(Ri)=11.008862E(R_i) = \frac{11.0088}{62} E(Ri)≈0.17756E(R_i) \approx 0.17756
  3. Calculate the beta coefficient (β\beta) using the Capital Asset Pricing Model (CAPM).

    The risk-free rate (RfR_f) is 10.25% (0.1025).
    The average market return (E(Rm)E(R_m)) is 16.90% (0.1690).

    E(Ri)=Rf+β(E(Rm)−Rf)E(R_i) = R_f + \beta (E(R_m) - R_f) 0.17756=0.1025+β(0.1690−0.1025)0.17756 = 0.1025 + \beta (0.1690 - 0.1025) 0.17756=0.1025+β(0.0665)0.17756 = 0.1025 + \beta (0.0665) 0.17756−0.1025=β(0.0665)0.17756 - 0.1025 = \beta (0.0665) 0.07506=β(0.0665)0.07506 = \beta (0.0665) β=0.075060.0665\beta = \frac{0.07506}{0.0665} β≈1.1287\beta \approx 1.1287

    Rounding to two decimal places:

    β≈1.13\beta \approx 1.13

    The beta coefficient of Nova Orbit Ltd. is 1.13\boxed{\text{1.13}}.

    1.2
    Since the calculated beta coefficient is approximately 1.13, which is greater than 1, Nova Orbit Ltd's ordinary shares are considered more volatile than the overall market. This indicates that the shares carry a higher systematic risk compared to the market.

Was this helpful?

Try one yourself

A new problem that tests the same skill.

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp