We read your photo as:

Calculate the net payoff for a call option with an exercise rate of 1.8000 AUD/USD and a premium of 0.005 AUD/USD, for two different spot exchange rates.

Business/Management

ScanSolve AI Answer

Answers

4 parts
i

−100 AUD\mathbf{-100 \text{ AUD}}

ii

2,100 AUD\mathbf{2,100 \text{ AUD}}

iii

−500 AUD\mathbf{-500 \text{ AUD}}

iv

1.8050 AUD/USD\mathbf{1.8050 \text{ AUD/USD}}

Step-by-step solution

11 steps

Here are the calculations for the call option:

First, calculate the total premium paid in Australian Dollars (AUD).
The premium is 0.5 Australian cents per USD, which is 0.005 AUD per USD.

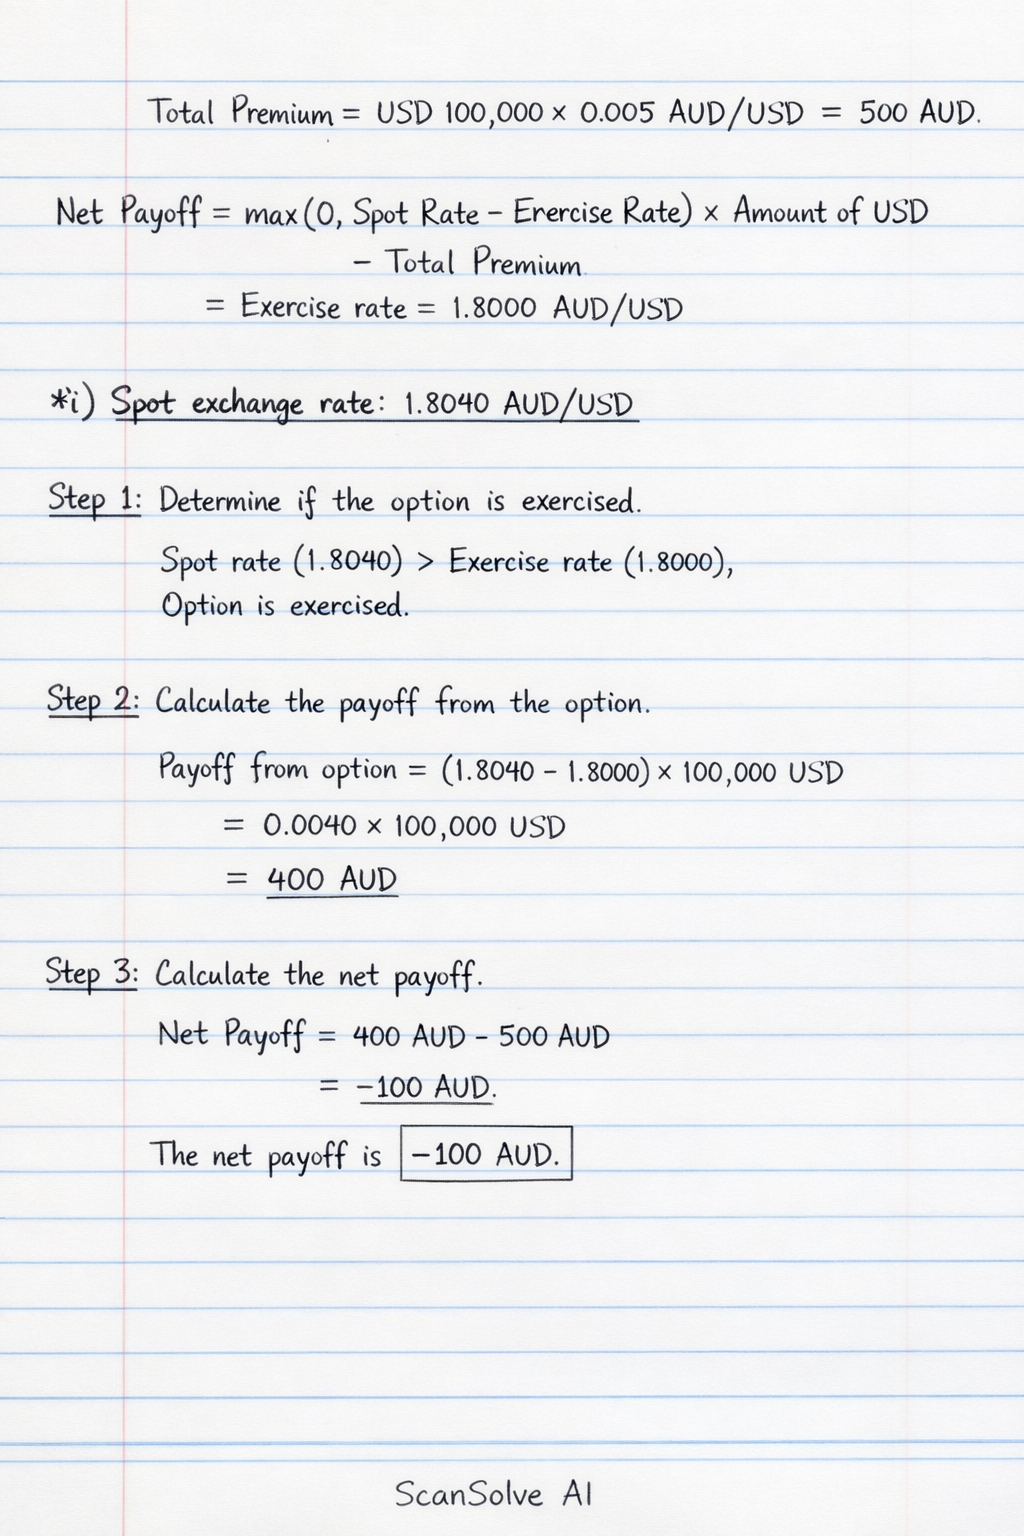
Total Premium=USD 100,000×0.005 AUD/USD=500 AUD\text{Total Premium} = \text{USD }100,000 \times 0.005 \text{ AUD/USD} = 500 \text{ AUD}

The net payoff for a call option is calculated as:

Net Payoff=max⁡(0,Spot Rate−Exercise Rate)×Amount of USD−Total Premium\text{Net Payoff} = \max(0, \text{Spot Rate} - \text{Exercise Rate}) \times \text{Amount of USD} - \text{Total Premium}

The exercise rate is 1.8000 AUD/USD.

Part i· 3 steps

Spot exchange rate: 1.8040 AUD/USD

  1. Determine if the option is exercised.

    Since the spot rate (1.8040) is greater than the exercise rate (1.8000), the option is exercised.

  2. Calculate the payoff from the option.

    Payoff from option=(1.8040−1.8000)×USD 100,000=0.0040×USD 100,000=400 AUD\text{Payoff from option} = (1.8040 - 1.8000) \times \text{USD }100,000 = 0.0040 \times \text{USD }100,000 = 400 \text{ AUD}
  3. Calculate the net payoff.

    Net Payoff=400 AUD−500 AUD=−100 AUD\text{Net Payoff} = 400 \text{ AUD} - 500 \text{ AUD} = -100 \text{ AUD}

    The net payoff is −100 AUD\boxed{\mathbf{-100 \text{ AUD}}}.

Part ii

2,100 AUD\mathbf{2,100 \text{ AUD}}

Spot exchange rate: 1.8260 AUD/USD

  1. Determine if the option is exercised.

    Since the spot rate (1.8260) is greater than the exercise rate (1.8000), the option is exercised.

  2. Calculate the payoff from the option.

    Payoff from option=(1.8260−1.8000)×USD 100,000=0.0260×USD 100,000=2,600 AUD\text{Payoff from option} = (1.8260 - 1.8000) \times \text{USD }100,000 = 0.0260 \times \text{USD }100,000 = 2,600 \text{ AUD}
  3. Calculate the net payoff.

    Net Payoff=2,600 AUD−500 AUD=2,100 AUD\text{Net Payoff} = 2,600 \text{ AUD} - 500 \text{ AUD} = 2,100 \text{ AUD}

    The net payoff is 2,100 AUD\boxed{\mathbf{2,100 \text{ AUD}}}.

Part iii

−500 AUD\mathbf{-500 \text{ AUD}}

Spot exchange rate: 1.7870 AUD/USD

  1. Determine if the option is exercised.

    Since the spot rate (1.7870) is less than the exercise rate (1.8000), the option is not exercised.

  2. Calculate the payoff from the option.

    Payoff from option=0 AUD\text{Payoff from option} = 0 \text{ AUD}
  3. Calculate the net payoff.

    Net Payoff=0 AUD−500 AUD=−500 AUD\text{Net Payoff} = 0 \text{ AUD} - 500 \text{ AUD} = -500 \text{ AUD}

    The net payoff is −500 AUD\boxed{\mathbf{-500 \text{ AUD}}}.

Part iv

1.8050 AUD/USD\mathbf{1.8050 \text{ AUD/USD}}

At what exchange rate will the holder break even?

  1. Set the net payoff to zero.

    Break-even occurs when the payoff from the option equals the total premium paid. For a call option, this means the option must be exercised.

    (Break-even Spot Rate−Exercise Rate)×Amount of USD=Total Premium(\text{Break-even Spot Rate} - \text{Exercise Rate}) \times \text{Amount of USD} = \text{Total Premium}
  2. Substitute the known values and solve for the break-even spot rate.

    (Break-even Spot Rate−1.8000)×USD 100,000=500 AUD(\text{Break-even Spot Rate} - 1.8000) \times \text{USD }100,000 = 500 \text{ AUD} Break-even Spot Rate−1.8000=500100,000\text{Break-even Spot Rate} - 1.8000 = \frac{500}{100,000} Break-even Spot Rate−1.8000=0.005\text{Break-even Spot Rate} - 1.8000 = 0.005 Break-even Spot Rate=1.8000+0.005\text{Break-even Spot Rate} = 1.8000 + 0.005 Break-even Spot Rate=1.8050 AUD/USD\text{Break-even Spot Rate} = 1.8050 \text{ AUD/USD}

    The holder will break even at an exchange rate of 1.8050 AUD/USD\boxed{\mathbf{1.8050 \text{ AUD/USD}}}.

Was this helpful?

Try one yourself

A new problem that tests the same skill.

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp