
We read your photo as:
From the original list of balances, draw up the sales ledger control account for the year ended 30 June 2004. Show the amendments to be made to the control account. Draw up a statement amending the total of the sales ledger balance to agree with the new control account balance.
ScanSolve AI Answer
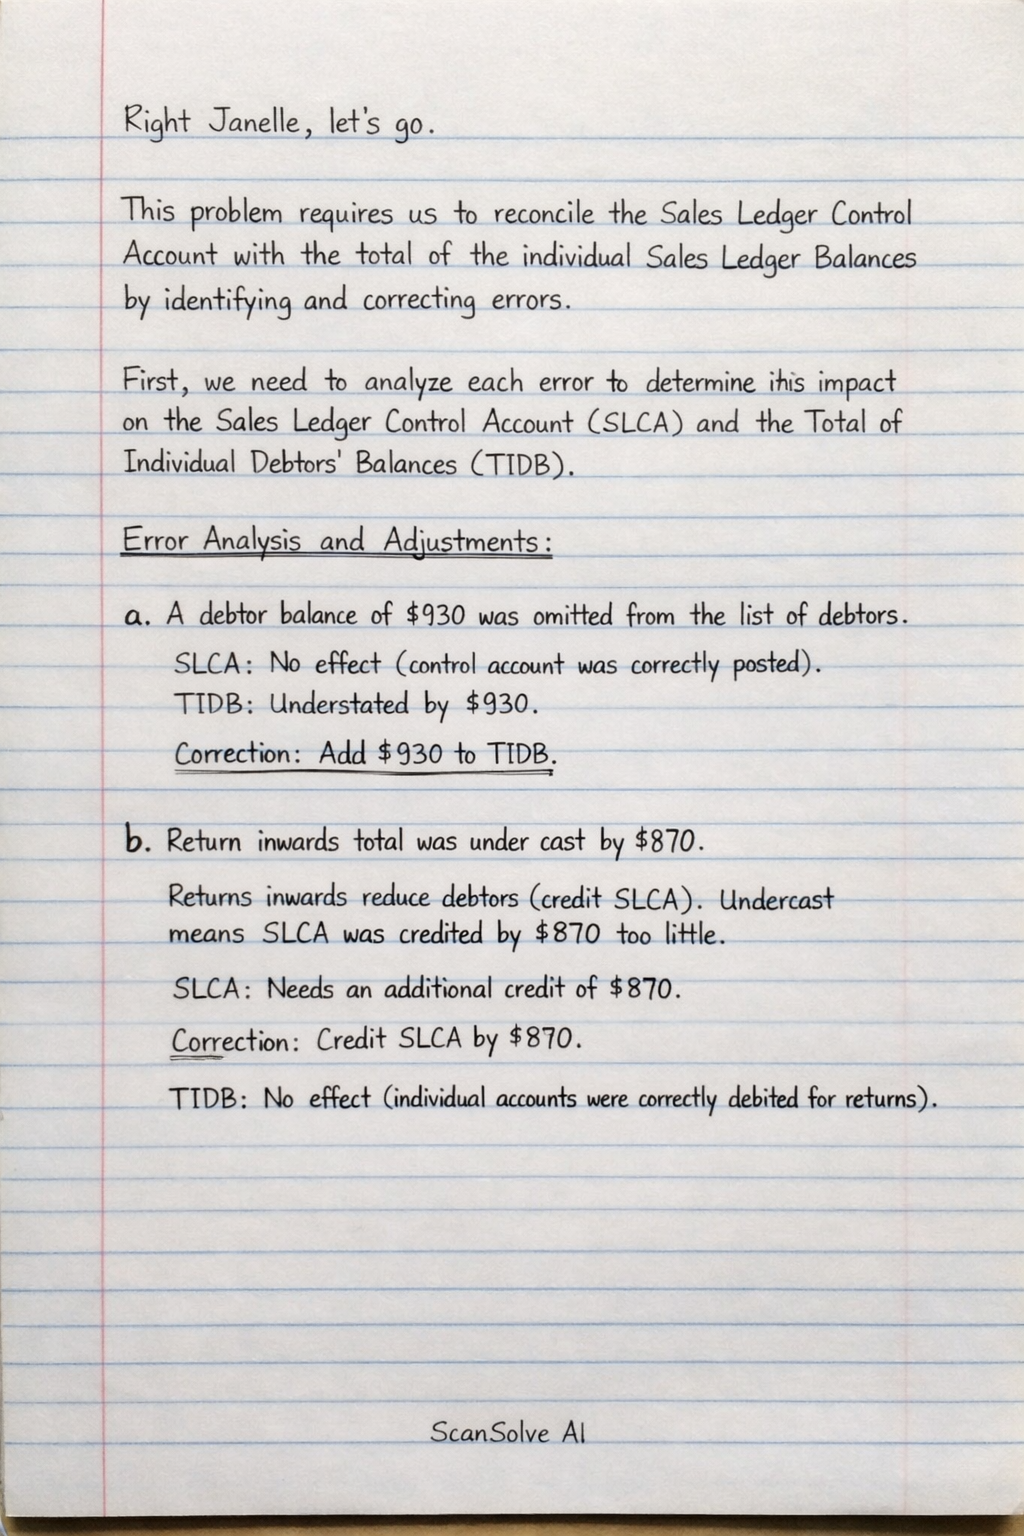
This problem requires us to reconcile the Sales Ledger Control Account with the total of the individual Sales Ledger Balances by identifying and correcting errors.
First, we need to analyze each error to determine its impact on the Sales Ledger Control Account (SLCA) and the Total of Individual Debtors' Balances (TIDB).
Error Analysis and Adjustments:
-
a. A debtor balance of $930 was omitted from the list of debtors.
- SLCA: No effect (control account was correctly posted).
- TIDB: Understated by 930 to TIDB.*
-
b. Return inwards formal was under cast by $870.
- Returns inwards reduce debtors (credit SLCA). Undercast means SLCA was credited by $870 too little.
- SLCA: Needs an additional credit of 870.*
- TIDB: No effect (individual accounts were correctly debited for returns).
-
c. C-Donald had returned goods worth 450 in his account.
- C-Donald's individual account was credited 540. This means his balance is overstated by 540 - $450).
- SLCA: No effect (assumed correctly credited $540).
- TIDB: Overstated by 90 from TIDB.*
-
d. Discount allowed $270 had been posted to the wrong side of debtors account.
- Discount allowed reduces a debtor's balance (credit individual account). Posting to the wrong side means it was debited 270 (wrong debit) + 540.
- SLCA: No effect (assumed correctly credited for discount allowed).
- TIDB: Overstated by 540 from TIDB.*
-
e. A debtor was charged with $80 interest but it was overlooked by the accountant.
- Interest charged increases a debtor's balance (debit SLCA, debit individual account).
- SLCA: Should have been debited 80.*
- TIDB: Understated by 80 to TIDB.*
-
f. Sales day book had been over cast by $1360.
- The total of the sales day book is debited to the SLCA. If overcast, the SLCA is overstated.
- SLCA: Needs a credit of 1360.*
- TIDB: No effect (individual accounts were correctly debited for sales).
-
g. Bad debts of $190 is entered in the control account but is not posted to the customer's account.
- Bad debts reduce debtors (credit SLCA, credit individual account).
- SLCA: Correctly credited $190. No effect.
- TIDB: Individual account was not credited. So, TIDB is overstated by 190 from TIDB.*
-
h. Discount allowed of $350 had been entered in the cash book but is not entered in the customer's account.
- Discount allowed reduces debtors (credit individual account). If not entered, the customer's balance is overstated.
- SLCA: No effect (control account is usually updated from the cash book total for discounts allowed).
- TIDB: Overstated by 350 from TIDB.*
-
i. Return inwards $440 from B-Jones had not been recorded in the books.
- Returns inwards reduce debtors (credit SLCA, credit individual account).
- SLCA: Should have been credited 440.*
- TIDB: Overstated by 440 from TIDB.*
-
j. B-Hertz was both a customer and a supplier. He had a balance of 190 in the sales ledger. The contra entry was made in B-Hertz's account but no entry was made in the control account.
- A contra entry reduces both sales ledger and purchase ledger balances. The smaller amount (190.
- SLCA: Should have been credited 190.*
- TIDB: No effect (individual account was correctly credited).
-
k. A sales invoice of $1490 was not entered in the books.
- Sales increase debtors (debit SLCA, debit individual account).
- SLCA: Should have been debited 1490.*
- TIDB: Understated by 1490 to TIDB.*
-
l. A credit sale of $1860 to C-Nelson was entered on the credit side of his account.
- A credit sale increases a debtor's balance (debit individual account). Entering on the credit side means it was credited 1860. This makes the balance understated by 1860 (missing debit) = $3720.
- SLCA: No effect (control account was correctly debited for the sale).
- TIDB: Understated by 3720 to TIDB.*
1. From the original list of balances, draw up the sales ledger control account for the year ended 30 June 2004.
To "draw up" the sales ledger control account, we first need to determine its unadjusted closing balance. We will do this by working backward from the corrected balance, which we will find by adjusting the total of the sales ledger balances.
-
Step 1: Calculate the corrected total of Sales Ledger Balances (TIDB). Initial Total of Sales Ledger Balances = $80080 Additions to TIDB:
- a. Debtor balance omitted: $930
- e. Interest charged overlooked: $80
- k. Sales invoice not entered: $1490
- l. Credit sale wrongly credited: 930 + 1490 + 6220
Deductions from TIDB:
- c. C-Donald returns (450): $90
- d. Discount allowed wrong side (270): $540
- g. Bad debts not posted to customer: $190
- h. Discount allowed not entered in customer's account: $350
- i. Returns inwards not recorded: 90 + 190 + 440 = $1610
Corrected Total of Sales Ledger Balances = 6220 - 84690.
This is the target corrected balance for both the TIDB and the SLCA. -
Step 2: Determine the unadjusted closing balance of the Sales Ledger Control Account. Let be the unadjusted closing balance of the Sales Ledger Control Account. Adjustments to SLCA:
- Debits: e (1490) = $1570
- Credits: b (1360), i (190) = $2860
The corrected balance of SLCA is .
1570 - 84690
1290 = X = 1290 = $85980Since we are asked to "draw up" the account but lack full transaction details, we present the derived unadjusted closing balance.
The unadjusted closing balance of the Sales Ledger Control Account is
\boxed{\85980}$.
2. Show the amendments to be made to the control account.
This involves reconciling the unadjusted control account balance with the corrected balance.
-
Step 1: Start with the unadjusted balance. Unadjusted Balance of Sales Ledger Control Account = $85980.
-
Step 2: Apply debit adjustments.
- e. Interest charged overlooked: Debit SLCA by $80.
- k. Sales invoice not entered: Debit SLCA by $1490.
- Total Debits = $1570.
-
Step 3: Apply credit adjustments.
- b. Returns inwards undercast: Credit SLCA by $870.
- f. Sales day book overcast: Credit SLCA by $1360.
- i. Returns inwards not recorded: Credit SLCA by $440.
- j. Contra entry not made: Credit SLCA by $190.
- Total Credits = $2860.
-
Step 4: Calculate the corrected balance. Corrected Balance = Unadjusted Balance + Total Debits - Total Credits Corrected Balance = 1570 - 84690.
Sales Ledger Control Account Reconciliation
3. Draw up a statement amending the total of the sales ledger balance to agree with the new control account balance.
This statement reconciles the initial total of individual sales ledger balances with the corrected balance.
-
Step 1: Start with the initial total of sales ledger balances. Initial Total of Sales Ledger Balances = $80080.
-
Step 2: Apply additions.
- a. Debtor balance omitted: $930
- e. Interest charged overlooked: $80
- k. Sales invoice not entered: $1490
- l. Credit sale wrongly credited (): 3720 Total Additions = 80 + 3720 = $6220.
-
Step 3: Apply deductions.
- c. C-Donald returns (450): $90
- d. Discount allowed wrong side (): 540
- g. Bad debts not posted to customer: $190
- h. Discount allowed not entered in customer's account: $350
- i. Returns inwards not recorded: 440 Total Deductions = 540 + 350 + 1610.
-
Step 4: Calculate the corrected total. Corrected Total = Initial Total + Total Additions - Total Deductions Corrected Total = 6220 - 84690.
Statement Amending Total of Sales Ledger Balances
The corrected balance of the Sales Ledger Control Account (84690).
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp