
We read your photo as:
Prepare a statement to calculate the corrected inventory as at 31 December 2024.
Accounting
ScanSolve AI Answer
Answer
Step-by-step solution
2 stepsTo calculate the corrected inventory as at 31 December 2024, we will start with the inventory valuation on 10 January 2025 and make adjustments for errors and omissions within that valuation, then reverse the effect of transactions that occurred between 1 January 2025 and 10 January 2025.
The business sells goods at a mark-up of 20%. This means:
Calculate the corrected inventory on 10 January 2025.
- Inventory as per valuation on 10 January 2025:
\32,000$ - Adjustment for damaged goods (Jan 8):
- Cost of damaged goods:
\4,000$ - Net Realizable Value (NRV): Selling Price Cost to Repair
= \3,000 - $500 = $2,500$ - Since NRV
(\2,500)($4,000)$, the inventory should be valued at NRV. - Write-down adjustment:
\4,000 - $2,500 = $1,500$. This amount is subtracted from the inventory.
- Cost of damaged goods:
- Adjustment for omitted goods (Jan 9):
- Goods costing
\800$ were omitted from the physical count. These should be added back.
- Goods costing
- Adjustment for goods on sale or return (Jan 5):
- Goods worth
\2,500$ (selling price) were sent out, but ownership had not passed. These goods are still part of Makwema Traders' inventory. - Cost of these goods:
\frac{\2,500}{1.20} = $2,083.33$. - Assuming these goods were not included in the physical count (as they were out with the customer), they need to be added back.
- Goods worth
- Inventory as per valuation on 10 January 2025:
Adjust the corrected 10 January 2025 inventory to 31 December 2024.
We need to reverse the effect of transactions that occurred between 1 January 2025 and 10 January 2025.
- Sales (Jan 2):
- Sales of
\18,000$ occurred after 31 December 2024. These goods were part of the inventory on 31 December 2024. - Cost of sales:
\frac{\18,000}{1.20} = $15,000$. This amount is added back.
- Sales of
- Purchases (Jan 4):
- Purchases of
\10,000$ occurred after 31 December 2024. These goods were not part of the inventory on 31 December 2024. - This amount is subtracted.
- Purchases of
- Goods taken for personal use (Jan 6):
- Goods costing
\1,200$ were taken after 31 December 2024. These goods were part of the inventory on 31 December 2024. - This amount is added back.
- Goods costing
- Sales returns (Jan 7):
- Sales returns of
\600$ were received after 31 December 2024. These goods were not part of the inventory on 31 December 2024 (they had been sold). - Cost of sales returns:
\frac{\600}{1.20} = $500$. This amount is subtracted.
- Sales returns of
Here is the statement:
- Sales (Jan 2):
Was this helpful?
Try one yourself
A new problem that tests the same skill.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
Got a different question?Ask your own question
More Accounting Questions
QPrepare the Income Statement for the year ended 31 December 2023, including all necessary…QPrepare the Statement of Profit or Loss for the year ended 31st December 2019, including necessary…QPrepare a Statement of Financial Position for XYZ Merchandisers as at 31st December 2024.QConstruct a statement of financial position at 31st December 2025QPrepare the Branch Inventory Account and Branch Adjustment Account for the year ended 31 December…
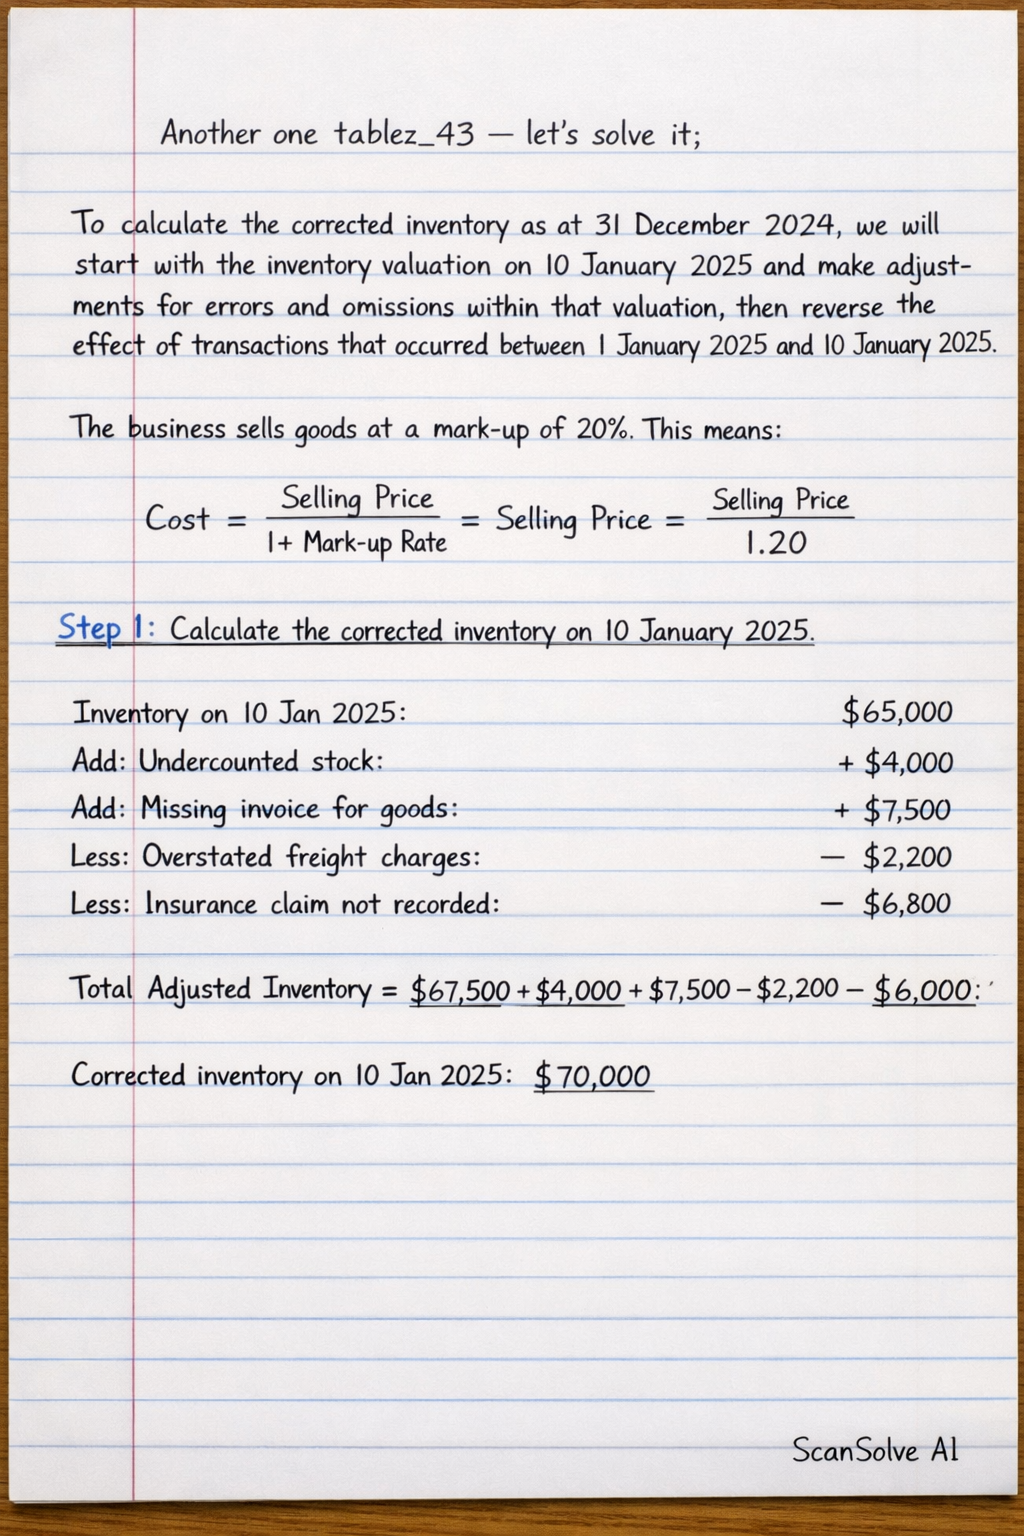
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp