We read your photo as:

Prepare income statements under absorption and marginal costing and reconcile the difference in profit, given the following data...

Accounting

ScanSolve AI Answer

Step-by-step solution

4 steps

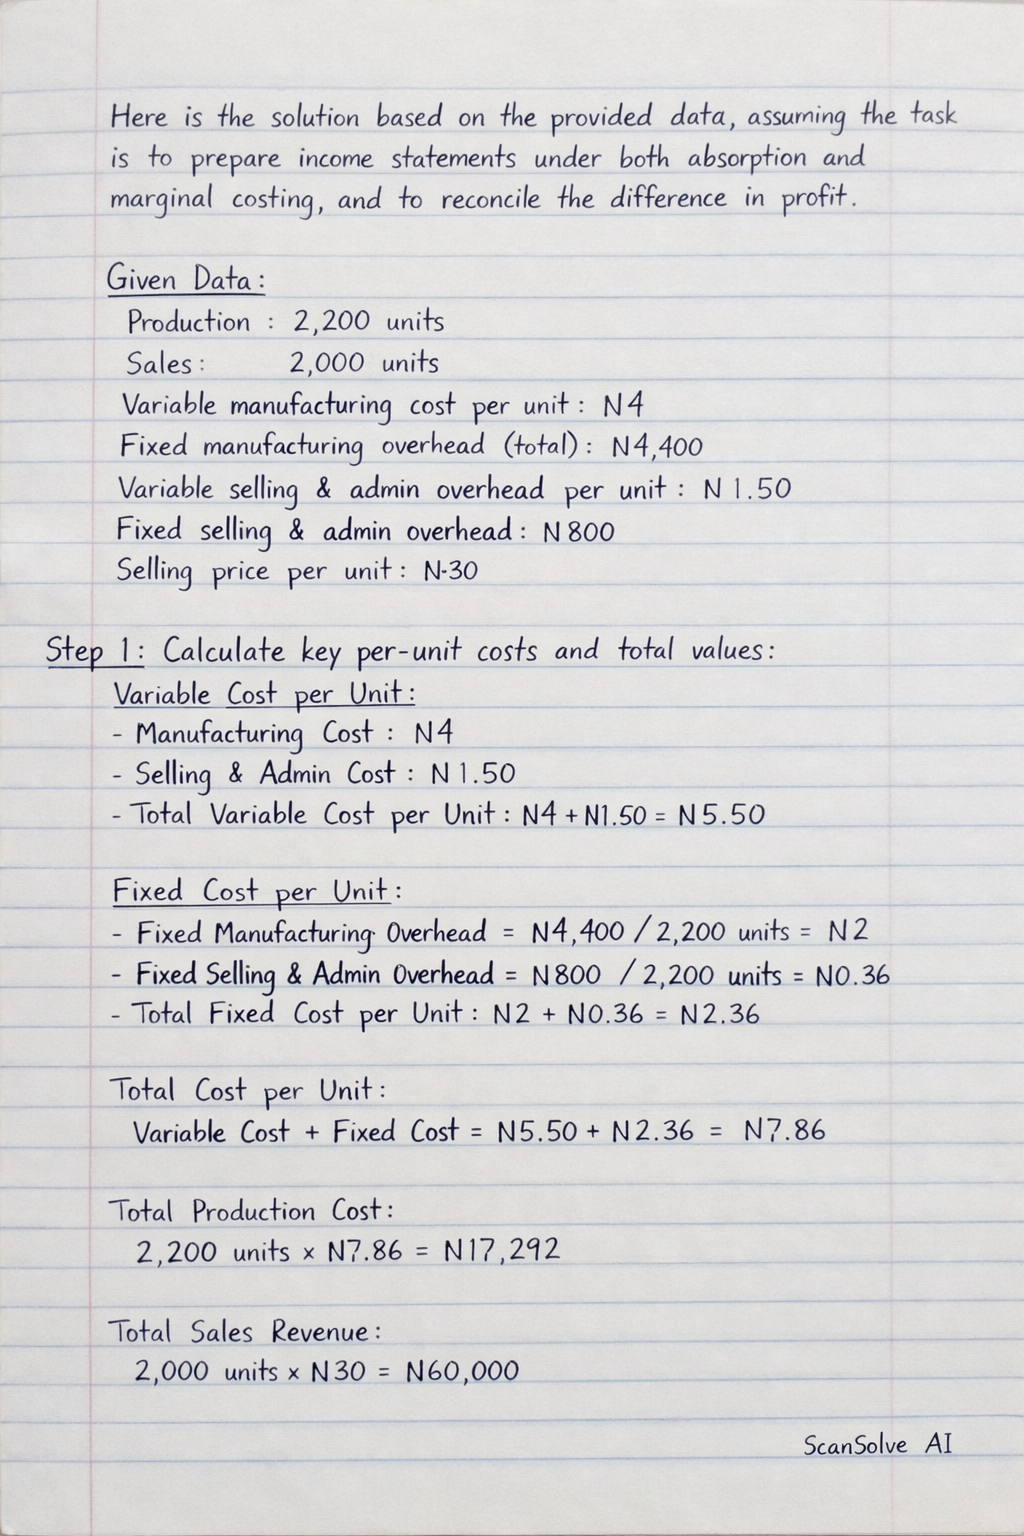
Here is the solution based on the provided data, assuming the task is to prepare income statements under both absorption and marginal costing, and to reconcile the difference in profit.

Given Data:

  • Production: 2,200 units
  • Sales: 2,000 units
  • Variable manufacturing cost per unit: N4\text{N}4
  • Fixed manufacturing overhead (total): N4,400\text{N}4,400
  • Variable selling and administration overhead per unit: N1.50\text{N}1.50
  • Fixed selling and administration overhead: N800\text{N}800
  • Selling price per unit: N30\text{N}30
  1. Calculate key per-unit costs and total values.

    • Fixed manufacturing overhead per unit: Fixed manufacturing overhead (total)Production units=N4,4002,200 units=N2 per unit\frac{\text{Fixed manufacturing overhead (total)}}{\text{Production units}} = \frac{\text{N}4,400}{2,200 \text{ units}} = \text{N}2 \text{ per unit}
    • Total Sales Revenue: 2,000 units×N30/unit=N60,0002,000 \text{ units} \times \text{N}30/\text{unit} = \text{N}60,000
    • Ending Inventory Units: Production units−Sales units=2,200 units−2,000 units=200 units\text{Production units} - \text{Sales units} = 2,200 \text{ units} - 2,000 \text{ units} = 200 \text{ units}
    • Total Variable Selling and Administrative Expenses: 2,000 units×N1.50/unit=N3,0002,000 \text{ units} \times \text{N}1.50/\text{unit} = \text{N}3,000
  2. Prepare Income Statement under Absorption Costing.

    Under absorption costing, all manufacturing costs (variable and fixed) are included in the product cost.

    • Product Cost per Unit (Absorption): Variable manufacturing cost per unit+Fixed manufacturing overhead per unit=N4+N2=N6 per unit\text{Variable manufacturing cost per unit} + \text{Fixed manufacturing overhead per unit} = \text{N}4 + \text{N}2 = \text{N}6 \text{ per unit}
    • Cost of Goods Sold (Absorption): Sales units×Product cost per unit (Absorption)=2,000 units×N6/unit=N12,000\text{Sales units} \times \text{Product cost per unit (Absorption)} = 2,000 \text{ units} \times \text{N}6/\text{unit} = \text{N}12,000
    Fortune Ltd.Absorption Costing Income StatementSales RevenueN60,000Less: Cost of Goods SoldN12,000Gross ProfitN48,000Less: Selling and Administrative Expenses:Variable Selling and Admin.N3,000Fixed Selling and Admin.N800Total Selling and Admin. ExpensesN3,800Net Operating IncomeN44,200\begin{align*} \textbf{Fortune Ltd.}\\ \textbf{Absorption Costing Income Statement}\\ \text{Sales Revenue} && \text{N}60,000 \\ \text{Less: Cost of Goods Sold} && \text{N}12,000 \\ \text{Gross Profit} && \text{N}48,000 \\ \text{Less: Selling and Administrative Expenses:} \\ \text{Variable Selling and Admin.} && \text{N}3,000 \\ \text{Fixed Selling and Admin.} && \text{N}800 \\ \text{Total Selling and Admin. Expenses} && \text{N}3,800 \\ \textbf{Net Operating Income} && \boxed{\textbf{N}44,200} \end{align*}
  3. Prepare Income Statement under Marginal Costing.

    Under marginal costing, only variable manufacturing costs are included in the product cost. Fixed manufacturing overhead is treated as a period cost.

    • Product Cost per Unit (Marginal): Variable manufacturing cost per unit=N4 per unit\text{Variable manufacturing cost per unit} = \text{N}4 \text{ per unit}
    • Variable Cost of Goods Sold (Marginal): Sales units×Product cost per unit (Marginal)=2,000 units×N4/unit=N8,000\text{Sales units} \times \text{Product cost per unit (Marginal)} = 2,000 \text{ units} \times \text{N}4/\text{unit} = \text{N}8,000
    Fortune Ltd.Marginal Costing Income StatementSales RevenueN60,000Less: Variable Cost of Goods SoldN8,000Manufacturing Contribution MarginN52,000Less: Variable Selling and Administrative ExpensesN3,000Total Contribution MarginN49,000Less: Fixed Expenses:Fixed Manufacturing OverheadN4,400Fixed Selling and Administrative ExpensesN800Total Fixed ExpensesN5,200Net Operating IncomeN43,800\begin{align*} \textbf{Fortune Ltd.}\\ \textbf{Marginal Costing Income Statement}\\ \text{Sales Revenue} && \text{N}60,000 \\ \text{Less: Variable Cost of Goods Sold} && \text{N}8,000 \\ \text{Manufacturing Contribution Margin} && \text{N}52,000 \\ \text{Less: Variable Selling and Administrative Expenses} && \text{N}3,000 \\ \text{Total Contribution Margin} && \text{N}49,000 \\ \text{Less: Fixed Expenses:} \\ \text{Fixed Manufacturing Overhead} && \text{N}4,400 \\ \text{Fixed Selling and Administrative Expenses} && \text{N}800 \\ \text{Total Fixed Expenses} && \text{N}5,200 \\ \textbf{Net Operating Income} && \boxed{\textbf{N}43,800} \end{align*}
  4. Reconcile the difference in Net Operating Income.

    The difference in net operating income between absorption costing and marginal costing is due to the treatment of fixed manufacturing overhead in inventory.

    • Net Operating Income (Absorption Costing): N44,200\text{N}44,200
    • Net Operating Income (Marginal Costing): N43,800\text{N}43,800
    • Difference: N44,200−N43,800=N400\text{N}44,200 - \text{N}43,800 = \text{N}400

    This difference can be reconciled as follows:

    Change in Inventory Units=Production units−Sales units=2,200 units−2,000 units=200 units (increase)Fixed Manufacturing Overhead per Unit=N2Difference in Profit=Change in Inventory Units×Fixed Manufacturing Overhead per Unit=200 units×N2/unit=N400\begin{align*} \text{Change in Inventory Units} &= \text{Production units} - \text{Sales units} \\ &= 2,200 \text{ units} - 2,000 \text{ units} = 200 \text{ units (increase)} \\ \text{Fixed Manufacturing Overhead per Unit} &= \text{N}2 \\ \text{Difference in Profit} &= \text{Change in Inventory Units} \times \text{Fixed Manufacturing Overhead per Unit} \\ &= 200 \text{ units} \times \text{N}2/\text{unit} = \text{N}400 \end{align*}

    Since production was greater than sales, inventory increased, meaning some fixed manufacturing overhead was "stored" in ending inventory under absorption costing, leading to a higher profit compared to marginal costing.

    Net Operating Income (Marginal Costing)N43,800Add: Fixed Manufacturing Overhead in Ending Inventory(200 units×N2/unit)N400Net Operating Income (Absorption Costing)N44,200\begin{align*} \text{Net Operating Income (Marginal Costing)} && \text{N}43,800 \\ \text{Add: Fixed Manufacturing Overhead in Ending Inventory} && \\ (200 \text{ units} \times \text{N}2/\text{unit}) && \text{N}400 \\ \textbf{Net Operating Income (Absorption Costing)} && \boxed{\textbf{N}44,200} \end{align*}
Was this helpful?

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp