

This accounting problem is solved step by step below, with detailed explanations to help you understand the method and arrive at the correct answer.
ScanSolve AI Answer
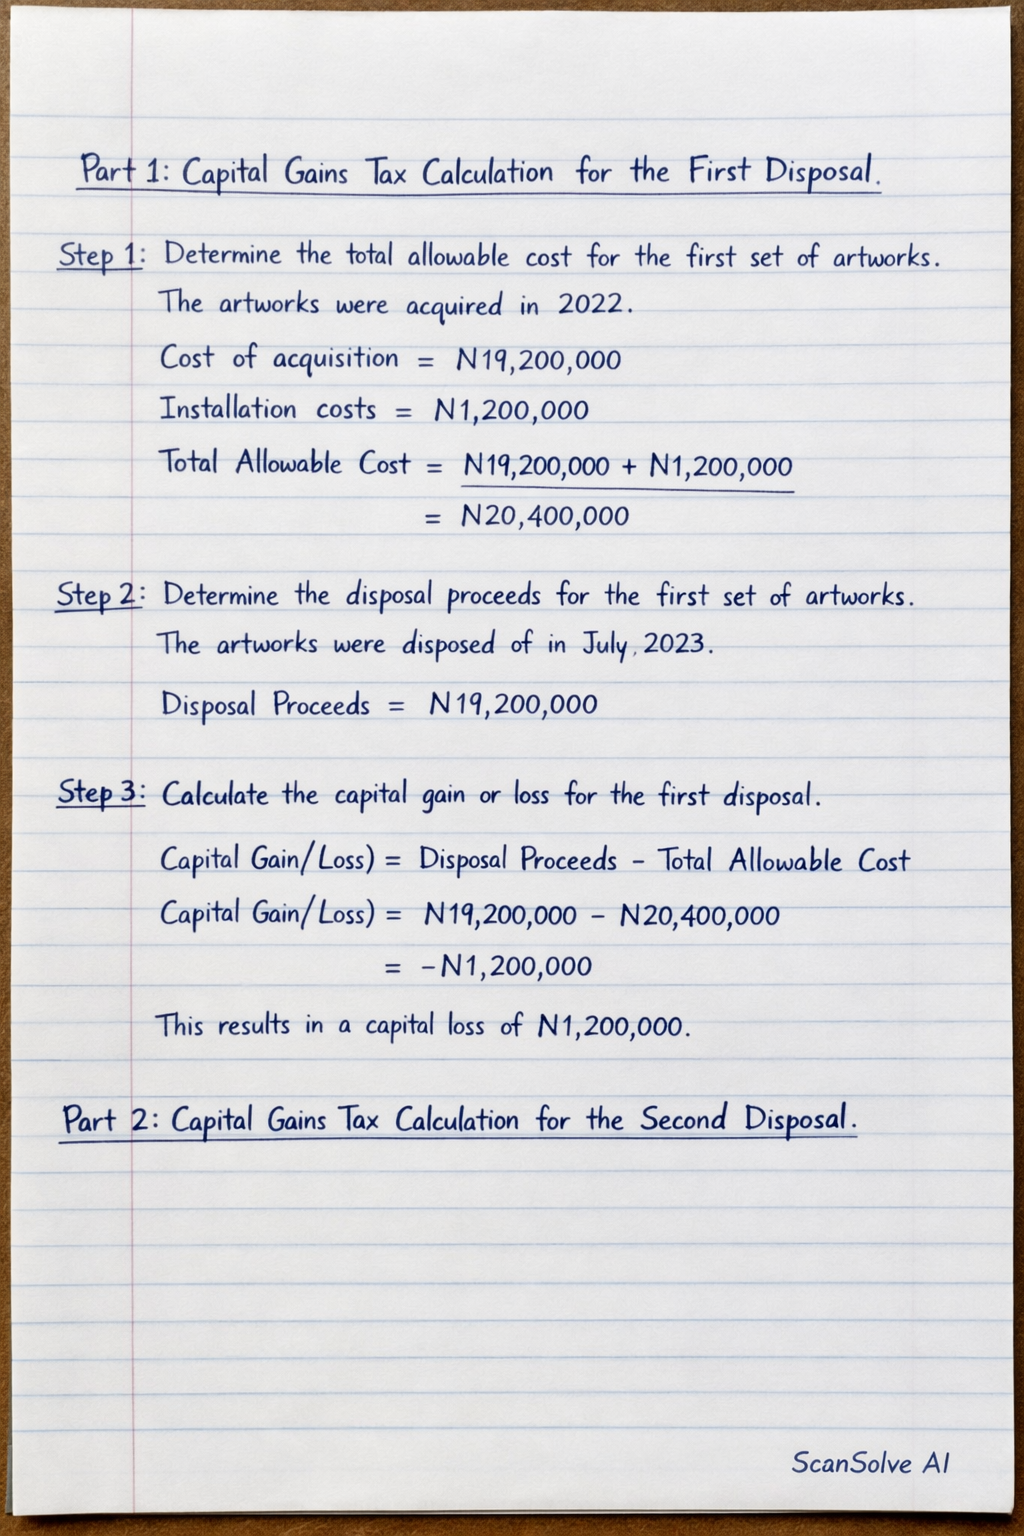
Alright glorydaniel, let's tackle Question Two regarding Glory and Daniel Hotels Limited. This question focuses on Capital Gains Tax (CGT) for the disposal of artworks. Part 1: Capital Gains Tax Calculation for the First Disposal Step 1: Determine the total allowable cost for the first set of artworks. The artworks were acquired in 2022. Cost of acquisition = N19,200,000 Installation costs = N1,200,000 Total Allowable Cost = N19,200,000 + N1,200,000 = N20,400,000 Step 2: Determine the disposal proceeds for the first set of artworks. The artworks were disposed of in July 2023. Disposal Proceeds = N19,200,000 Step 3: Calculate the capital gain or loss for the first disposal. Capital Gain/(Loss) = Disposal Proceeds - Total Allowable Cost Capital Gain/(Loss) = N19,200,000 - N20,400,000 = -N1,200,000 This results in a capital loss of N1,200,000. Part 2: Capital Gains Tax Calculation for the Second Disposal Step 1: Determine the total allowable cost for the second set of artworks. The second set of artworks was acquired in August 2023. Cost of acquisition = N22,500,000 Step 2: Determine the net disposal proceeds for the second set of artworks. The artworks were disposed of in May 2026, with financial details presented in August 2026. Sale proceeds = N15,100,000 Auctioneer's commission = 1.5\% × N15,100,000 = 0.015 × N15,100,000 = N226,500 Net Disposal Proceeds = N15,100,000 Total Allowable Costs (Acquisition and Disposal) = N22,500,000 + N226,500 = N22,726,500 Step 3: Calculate the capital gain or loss for the second disposal. Capital Gain/(Loss) = Net Disposal Proceeds - Total Allowable Costs Capital Gain/(Loss) = N15,100,000 - N22,726,500 = -N7,626,500 This results in a capital loss of N7,626,500. Part 3: Total Capital Gains Tax Payable Since both disposals resulted in capital losses, and in Nigeria, capital losses can only be carried forward to offset future capital gains (they cannot be offset against other income or result in a tax refund), there is no Capital Gains Tax payable for Glory and Daniel Hotels Limited for these transactions. Total Capital Gains Tax Payable = N0