
We read your photo as:
The following adjustments must be taken into account for the Statement of Financial Position:
ScanSolve AI Answer
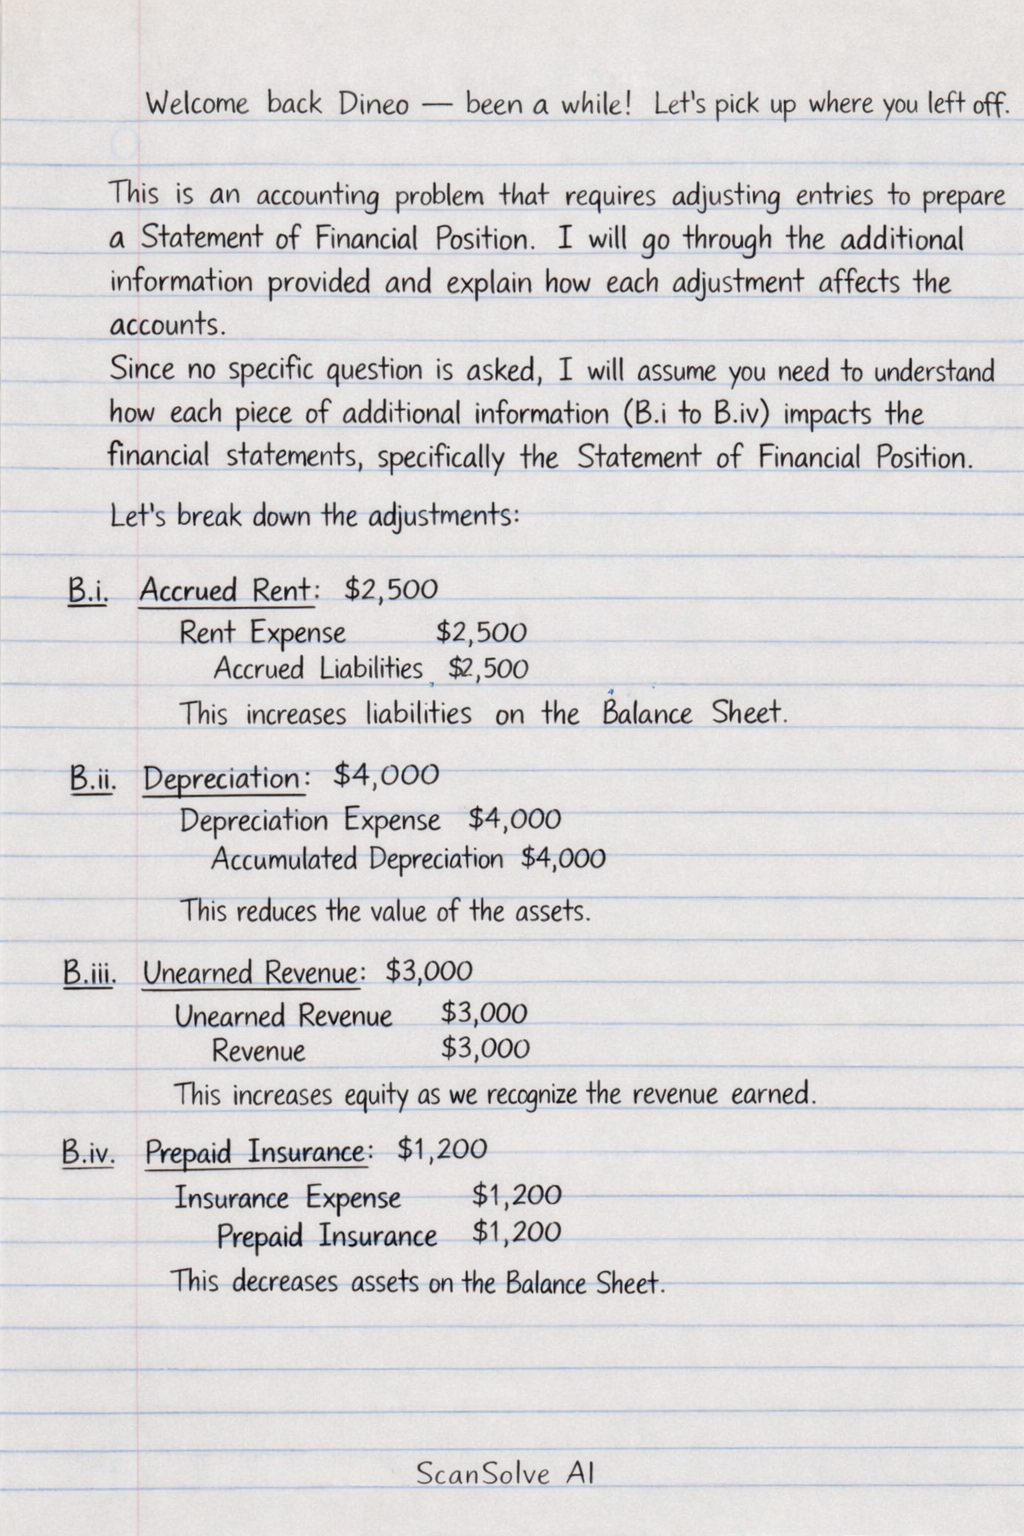
This is an accounting problem that requires adjusting entries to prepare a Statement of Financial Position. I will go through the additional information provided and explain how each adjustment affects the accounts.
Since no specific question is asked, I will assume you need to understand how each piece of additional information (B.i to B.iv) impacts the financial statements, specifically the Statement of Financial Position.
Let's break down the adjustments:
-
B.i. Adjustments for Statement of Financial Position:
- Amount owed for electricity, R3 900: This is an accrued expense.
- Impact: Increase Accrued Expenses (Current Liability) by R3 900.
- Commission income received in advance, R15 000: This is unearned revenue.
- Impact: Increase Unearned Income (Current Liability) by R15 000.
- An advertisement costing R14 000 will appear in the newspaper in March 2024. Payment was made and recorded in February 2024: This is a prepaid expense.
- Impact: Increase Prepaid Expenses (Current Asset) by R14 000.
- Packing material on hand at year-end per physical count, R7 300: This is inventory of consumables.
- Impact: Increase Packing Material on Hand (Current Asset) by R7 300.
- Rent owed by tenant, R8 000: This is accrued income.
- Impact: Increase Accrued Income (Current Asset) by R8 000.
- Amount owed for electricity, R3 900: This is an accrued expense.
-
B.ii. Fixed assets error correction:
- The R182 000 paid includes R150 000 for building a storeroom (capital expenditure) and R32 000 for repairs to the roof (revenue expenditure). The entire R182 000 was incorrectly included in Fixed Assets.
- Impact:
- The R150 000 for the storeroom is correctly part of Fixed Assets.
- The R32 000 for repairs should have been an expense, not capitalized. Therefore, Fixed Assets must be reduced by R32 000. This R32 000 would typically be expensed in the Income Statement, but for the Statement of Financial Position, it means the asset value is overstated.
- The initial Fixed Assets value is R1 191 200. The R182 000 was already included. The correction means R32 000 needs to be removed from Fixed Assets.
- New Fixed Assets value: R1 191 200 - R32 000 = R1 159 200.
- The R32 000 overstatement in Fixed Assets would also imply an overstatement in profit if it was expensed, or an understatement of expenses if it was capitalized. For the Statement of Financial Position, the direct impact is on the asset value.
-
B.iii. Fixed Deposit maturity:
- R25 000 of the Fixed Deposit at Top Bank matures on 31 May 2024. The financial year-end is 28 February 2024. Since it matures within 12 months of the year-end, this portion becomes a current asset.
- Impact:
- Reduce Non-current Fixed Deposit by R25 000.
- Increase Current Portion of Fixed Deposit (Current Asset) by R25 000.
- The total Fixed Deposit remains R120 000, but its classification changes.
-
B.iv. Loan repayment not recorded:
- A direct transfer of R15 000 was made from the bank account to settle the monthly repayment of the loan from Star Bank on 28 February 2024, but no entry was made.
- Impact:
- Reduce Bank (or increase Bank Overdraft) by R15 000.
- Reduce Loan from Star Bank (Non-current Liability) by R15 000.
- The initial Bank Overdraft is R64 700. If the R15 000 was paid from the bank, it would increase the overdraft.
- New Loan from Star Bank: R350 000 - R15 000 = R335 000.
Let me know if you'd like me to calculate the final adjusted balances for any specific accounts! 📸
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp