
We read your photo as:
Complete the following notes: Ordinary share capital, Retained income. Prepare the Statement of Financial Position.
ScanSolve AI Answer
Step-by-step solution
6 stepsHere's a breakdown of the required notes and the Statement of Financial Position based on the provided information and adjustments.
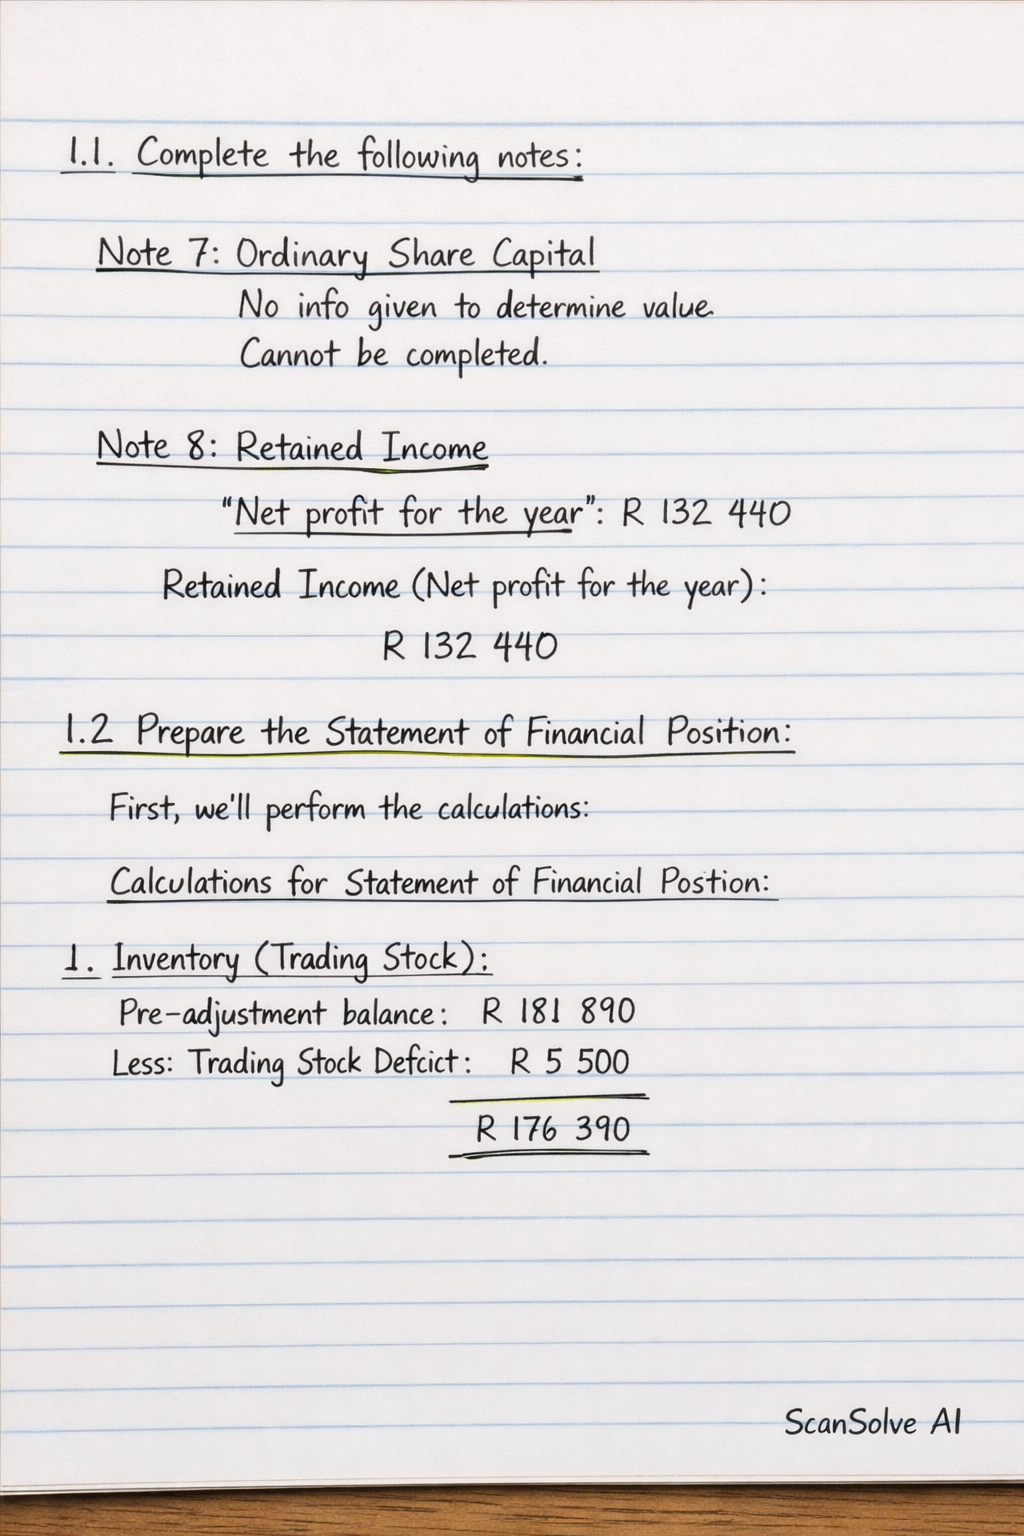
Part 1.1
Complete the following notes
Note 7: Ordinary Share Capital
No information is provided in the problem to determine the value of Ordinary Share Capital. Therefore, it cannot be completed.
Note 8: Retained Income
The Statement of Comprehensive Income explicitly states "Net profit after tax for the year (Note 8): R 132 440". Assuming the question refers to this value for Note 8, as no opening balance or dividends are provided for a full reconciliation.
- Retained Income (Net profit for the year): R 132 440
Part 1.2· 6 steps
Prepare the Statement of Financial Position.
First, we'll perform the necessary calculations for each line item.
Calculations for Statement of Financial Position:
Inventory (Trading Stock)
The pre-adjustment balance was R 181 890, and there was a trading stock deficit of R 5 500.
Trade and Other Receivables
- Debtors' list: R 133 022
- Less: Write-off of overdue account: R 4 400
- Adjusted debtors: R 133 022 - R 4 400 = R 128 622
- Less: New provision for bad debts: R 11 440
Prepaid Lease
The lease of vehicle expense is R 52 800 for the year. Since it's paid one month in advance, one month's payment is prepaid.
Prepaid Lease = R 4 400.
Long-term Loan
From the previous calculation (loan statement):
- Balance at the end of the year: R 618 737.76
- Fixed monthly repayments: R 8 120
- Interest for the next financial year: R 38 640 The current portion of the loan is the principal amount repayable in the next 12 months.
Trade and Other Payables
- Creditors' list: R 94 612
- Accrued Audit Fees: 20% of the year's audit fees are outstanding. The expense of R 48 400 represents 80% of the total.
- Accrued Insurance: The premium increased by R355 from 1 November 2025. The insurance for February 2026 is owed. Let be the monthly premium before November 2025. The new monthly premium (from Nov 2025) is R 2 100 + R 355 = R 2 455. Accrued Insurance (for February 2026) = R 2 455.
- Rent Received in Advance: Rent was paid until 30 April 2026 (2 months beyond year-end).
- Total Trade and Other Payables:
Income Tax Payable
From the Statement of Comprehensive Income, Income Tax is R 56 760. Assuming this is the amount payable at year-end.
Statement of Financial Position on 28 February 2026
ASSETS R Non-current assets Property, Plant and Equipment Not determinable Fixed deposit R 142 527 Current assets Inventory R 176 390 Trade and other receivables R 117 182 Prepaid lease R 4 400 Cash and cash equivalents Not determinable TOTAL ASSETS Not determinable EQUITY AND LIABILITIES Equity Ordinary share capital Not determinable Retained income R 132 440 Non-current liabilities Long-term loan R 559 937.76 Current liabilities Trade and other payables R 121 487 Current portion of long-term loan R 58 800 Income tax payable R 56 760 TOTAL EQUITY AND LIABILITIES Not determinable Note: The Statement of Financial Position cannot be fully completed or balanced due to missing information regarding Property, Plant and Equipment, Ordinary Share Capital, and Cash and Cash Equivalents.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp