
b A stock is currently selling for #60. The call option on the stock exercisable a year from now at an exercise price of #55 is currently selling for #15. The risk-free interest rate is 12%. The stock can either rise or fall atter a year. Calculate the per cent of the stock rise Calculate the per cent of the stock fall
Economics
ScanSolve AI Answer
This problem can be solved using the one-period binomial option pricing model. We are given the current stock price (), exercise price (), time to expiration (), current call option price (), and the risk-free interest rate (). We need to find the percentage rise and fall of the stock.
Given values:
- Current stock price,
- Exercise price,
- Time to expiration, year
- Current call option price,
- Risk-free interest rate, $r = 12% =
Was this helpful?
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
Got a different question?Ask your own question
More Economics Questions
QCalculate the net payoff for a call option with an exercise rate of 1.8000 AUD/USD and a premium of…QSuppose the value of the stock has fallen to $70 per share, sketch the balance sheet for this…QYou are given additional information: i) Stock as 30th/Dec/2025 ii) Closing StockQAn investment of GHS 10,000 is being considered for two options. Option A offers an 8% annual…QCalculate the expected return of a portfolio with 30% of Stock A and 70% of Stock B, given their…
Browse by topic:Macroeconomics
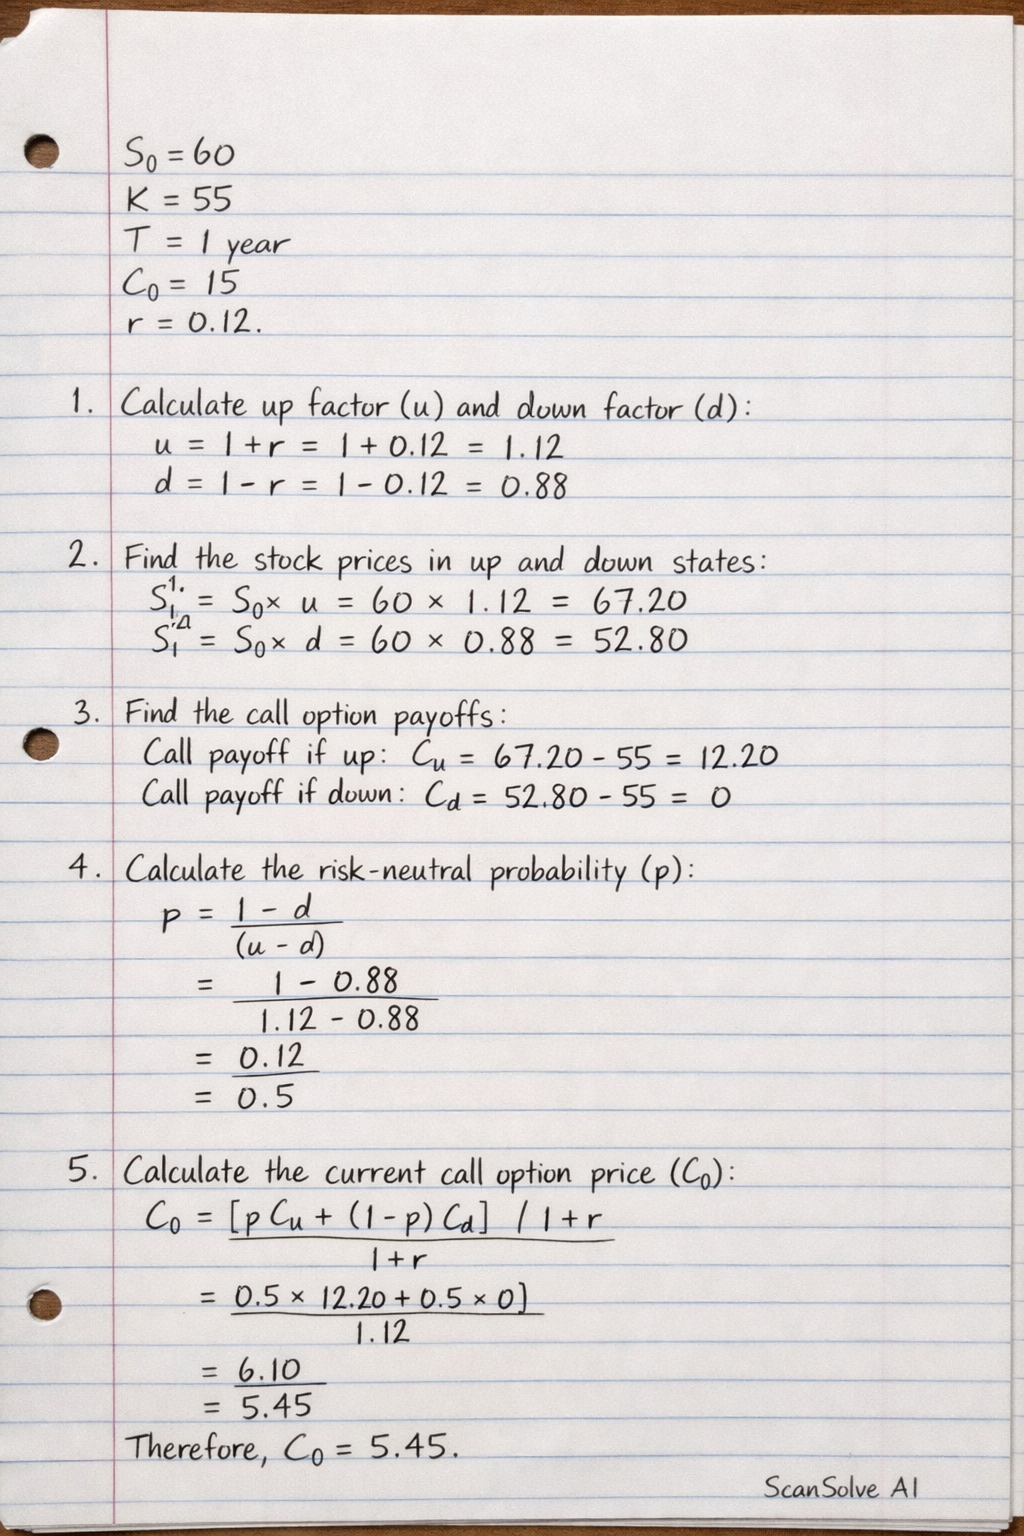
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp