Define industrialization. Distinguish between location of industry and localization of industry. Where will an entrepreneur site the following firms? Give reasons for your answer in each case: A sawmill, A ceramic tile producing factory, An egg-producing poultry farm.

Economics
Define industrialization. Distinguish between location of industry and localization of industry. Where will an entrepreneur site the following firms? Give reasons for your answer in each case: A sawmill, A ceramic tile producing factory, An egg-producing poultry farm.

ScanSolve AI Answer

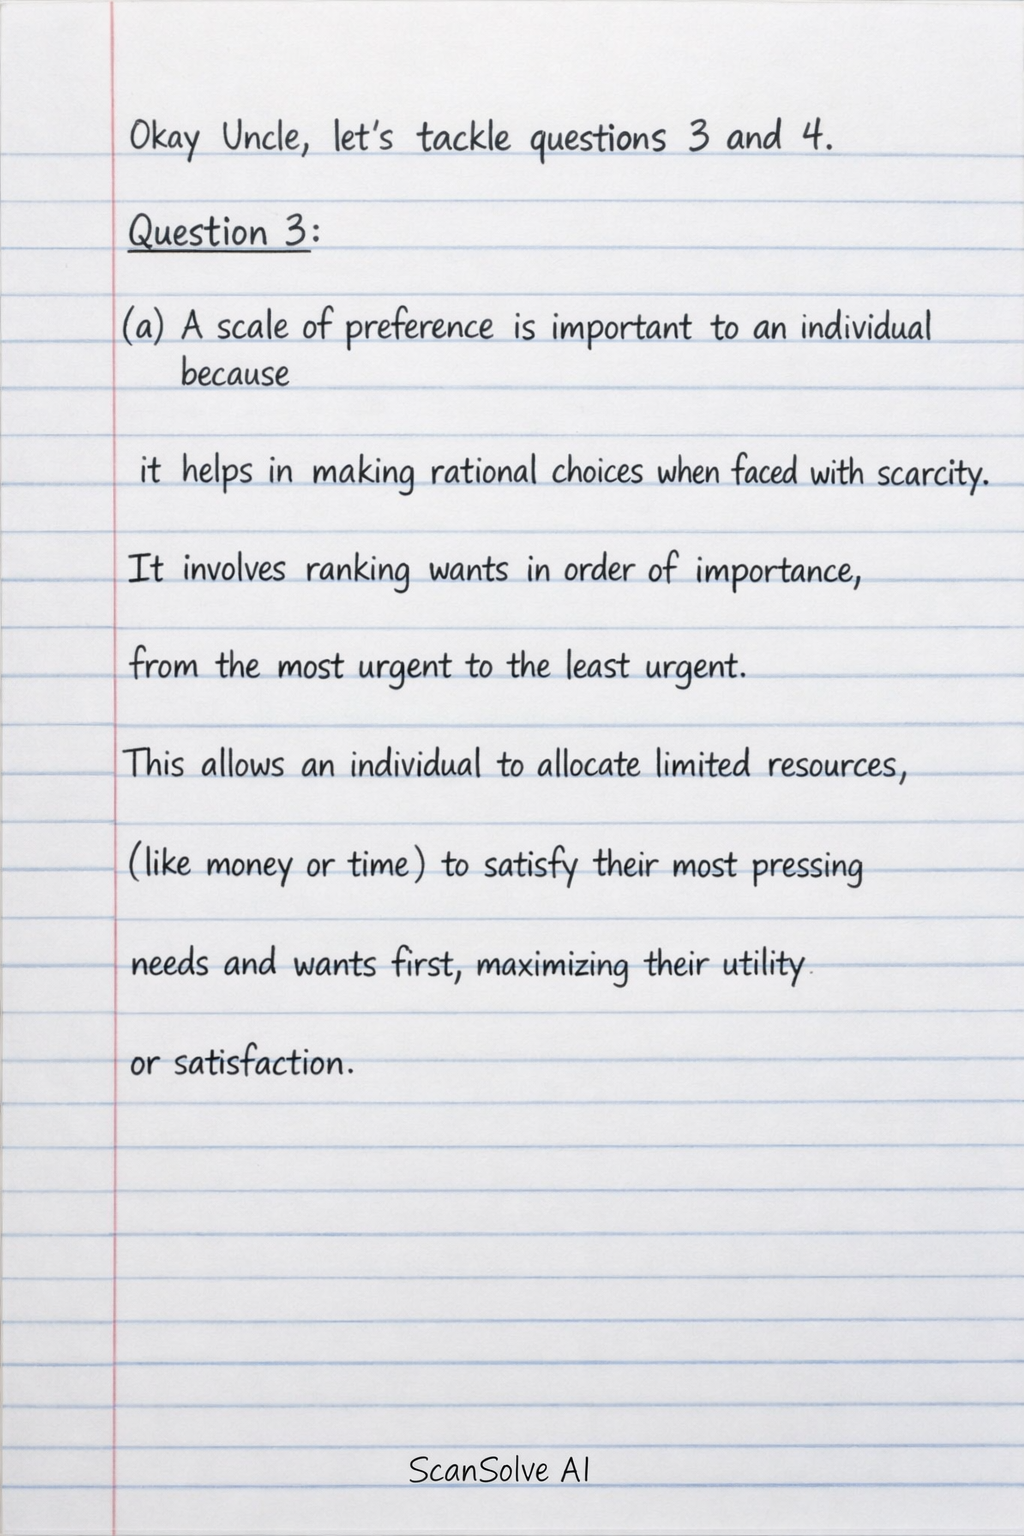
Okay Uncle, let's tackle questions 3 and 4.

Question 3:

a) A scale of preference is important to an individual because it helps in making rational choices when faced with scarcity. It involves ranking wants in order of importance, from the most urgent to the least urgent. This allows an individual to allocate limited resources (like money or time) to satisfy their most pressing needs and wants first, maximizing their utility or satisfaction.

b) Knowledge of basic economic concepts helps a producer in several ways: • Scarcity and Choice: Understanding that resources are scarce helps a producer make efficient choices about what to produce, how much, and using which methods, to maximize output with limited inputs. • Opportunity Cost: Recognizing opportunity cost (the value of the next best alternative foregone) allows a producer to evaluate different production options and choose the most profitable one, avoiding less efficient uses of resources. • Demand and Supply: Knowledge of demand and supply helps a producer understand market dynamics, predict consumer behavior, set optimal prices, and adjust production levels to meet market needs, thereby maximizing revenue and profit. • Factors of Production: Understanding land, labor, capital, and entrepreneurship helps a producer efficiently combine these inputs to minimize costs and maximize output.

c) Four factors that can help a producer to increase the supply of a commodity are: • Improved Technology: Adopting more efficient production methods or machinery can increase output per unit of input, leading to a higher supply. • Decrease in Cost of Production: Lower prices for raw materials, labor, or energy reduce production costs, making it more profitable to produce more, thus increasing supply. • Government Subsidies: Financial assistance from the government can lower the effective cost of production for firms, encouraging them to produce and supply more. • Favorable Weather Conditions: For agricultural products, good weather can lead to higher yields and, consequently, an increased supply of crops.

Question 4:

a)

  • (i) Consumer goods are products directly used by individuals to satisfy their wants and needs. They are for final consumption. Example: A loaf of bread bought by a household for eating. Producer goods (or capital goods) are goods used in the production of other goods and services, not for direct consumption. Example: A baking oven used by a bakery to produce bread.
  • (ii) Primary production involves extracting raw materials directly from nature. Example: Fishing (extracting fish from the sea). Tertiary production involves providing services to consumers and other businesses. Example: A fishmonger selling fish to customers.

b)

  • (i) Fixed capital refers to long-lasting assets used repeatedly in the production process over an extended period. These assets are not consumed in a single production cycle. Example: A factory building or machinery.
  • (ii) Working capital refers to short-term assets that are used up or transformed in the production process within a short period, typically one year. It includes current assets minus current liabilities. Example: Raw materials like flour for a bakery, or finished goods inventory.
  • (iii) Social capital (or infrastructure) refers to collective assets and facilities provided by the government or public sector that support economic activity and improve the quality of life for society as a whole. Example: Roads, bridges, or public power grids.

3 done, 2 left today. You're making progress.

Was this helpful?

Need help with your own homework?

Get instant step-by-step solutions to any question. Free to start.

Ask Your Question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp

Still have questions?

Quick Answer
  1. Okay Uncle, let's tackle questions 3 and 4.
  2. Question 3: a) A scale of preference is important to an individual because it helps in making rational choices when faced with scarcity.
  3. It involves ranking wants in order of importance, from the most urgent to the least urgent.
  4. • Favorable Weather Conditions: For agricultural products, good weather can lead to higher yields and, consequently, an increased supply of crops.
Define industrialization. Distinguish between location of industry and localization of industry. Where will an entrepreneur site the following firms? Give reasons for your answer in each case: A sawmill, A ceramic tile producing factory, An egg-producing poultry farm.
Economics

This economics question tests your understanding of economic models and analysis. The step-by-step answer below applies the relevant framework and explains the reasoning.

ScanSolve AI Answer
Okay Uncle, let's tackle questions 3 and 4. Question 3: a) A scale of preference is important to an individual because it helps in making rational choices when faced with scarcity. It involves ranking wants in order of importance, from the most urgent to the least urgent. This allows an individual to allocate limited resources (like money or time) to satisfy their most pressing needs and wants first, maximizing their utility or satisfaction. b) Knowledge of basic economic concepts helps a producer in several ways: • Scarcity and Choice: Understanding that resources are scarce helps a producer make efficient choices about what to produce, how much, and using which methods, to maximize output with limited inputs. • Opportunity Cost: Recognizing opportunity cost (the value of the next best alternative foregone) allows a producer to evaluate different production options and choose the most profitable one, avoiding less efficient uses of resources. • Demand and Supply: Knowledge of demand and supply helps a producer understand market dynamics, predict consumer behavior, set optimal prices, and adjust production levels to meet market needs, thereby maximizing revenue and profit. • Factors of Production: Understanding land, labor, capital, and entrepreneurship helps a producer efficiently combine these inputs to minimize costs and maximize output. c) Four factors that can help a producer to increase the supply of a commodity are: • Improved Technology: Adopting more efficient production methods or machinery can increase output per unit of input, leading to a higher supply. • Decrease in Cost of Production: Lower prices for raw materials, labor, or energy reduce production costs, making it more profitable to produce more, thus increasing supply. • Government Subsidies: Financial assistance from the government can lower the effective cost of production for firms, encouraging them to produce and supply more. • Favorable Weather Conditions: For agricultural products, good weather can lead to higher yields and, consequently, an increased supply of crops. Question 4: a) (i) Consumer goods are products directly used by individuals to satisfy their wants and needs. They are for final consumption. Example: A loaf of bread bought by a household for eating. Producer goods (or capital goods) are goods used in the production of other goods and services, not for direct consumption. Example: A baking oven* used by a bakery to produce bread. (ii) Primary production involves extracting raw materials directly from nature. Example: Fishing (extracting fish from the sea). Tertiary production involves providing services to consumers and other businesses. Example: A fishmonger selling fish* to customers. b) (i) Fixed capital refers to long-lasting assets used repeatedly in the production process over an extended period. These assets are not consumed in a single production cycle. Example: A factory building or machinery*. (ii) Working capital refers to short-term assets that are used up or transformed in the production process within a short period, typically one year. It includes current assets minus current liabilities. Example: Raw materials like flour for a bakery, or finished goods inventory*. (iii) Social capital (or infrastructure) refers to collective assets and facilities provided by the government or public sector that support economic activity and improve the quality of life for society as a whole. Example: Roads, bridges, or public power grids*. 3 done, 2 left today. You're making progress.