We read your photo as:

Journal entries to correct the errors given above. The Suspense Account clearly showing the opening balance on this account. Prepare a Statement of Corrected Net Profit for Trophy Enterprises for the year ended September 30, 2013. Prepare a Corrected Trial Balance for the business.

Accounting

ScanSolve AI Answer

Step-by-step solution

8 steps

Here are the journal entries to correct the errors:

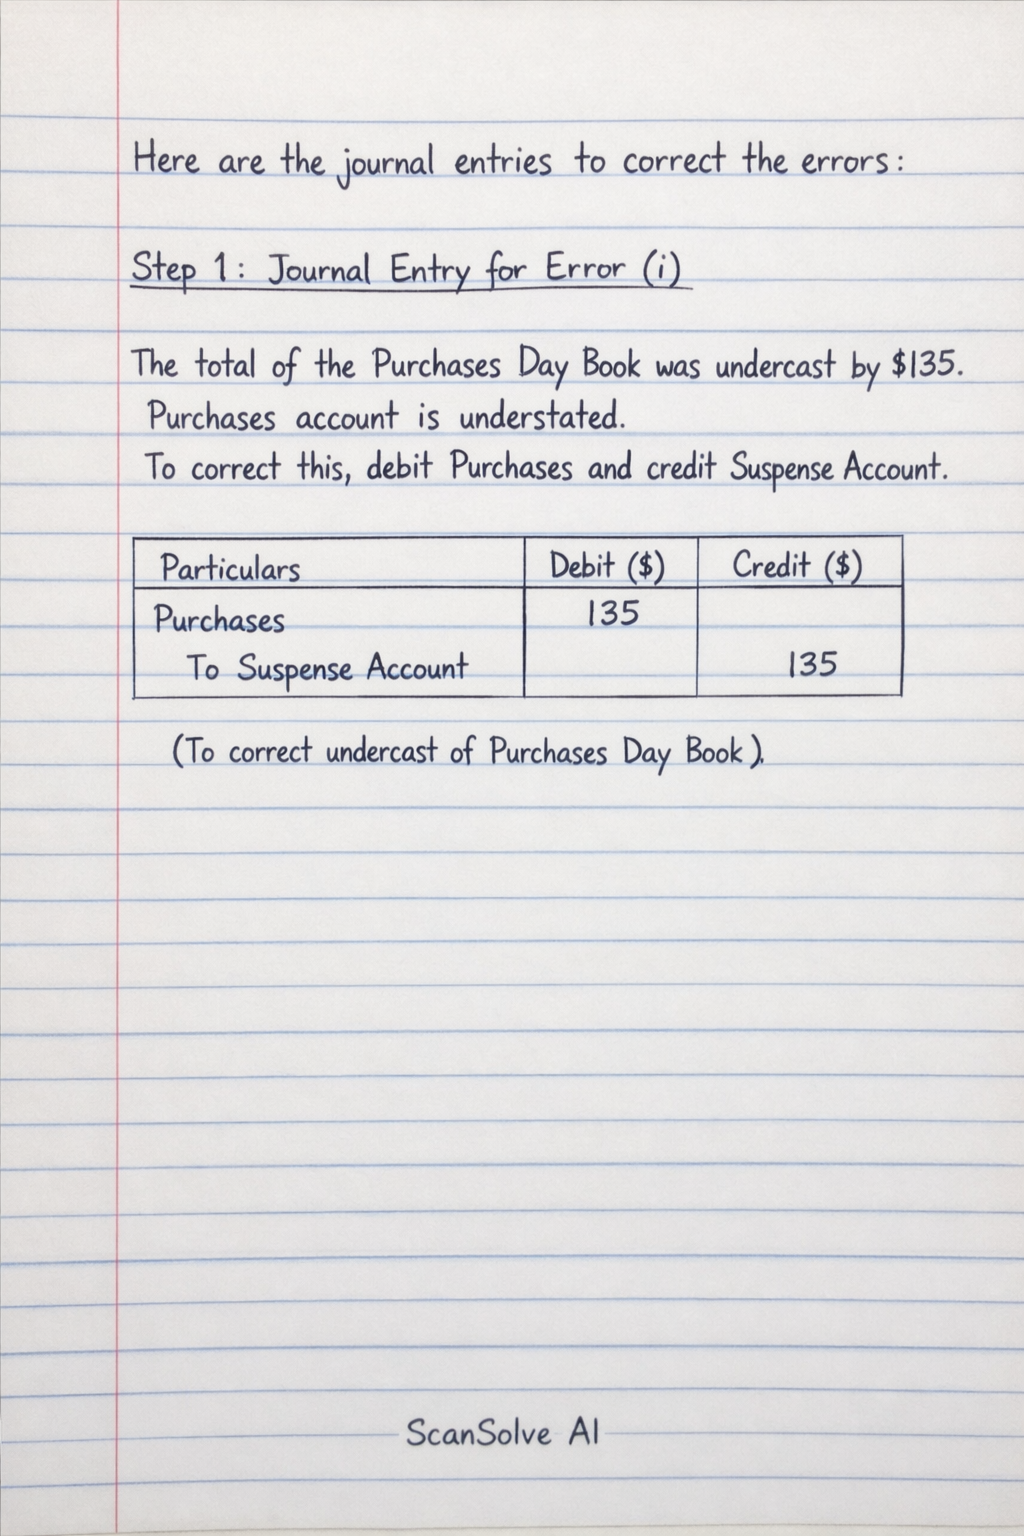
  1. Journal Entry for Error (i)

    The total of the Purchases Day Book was undercast by $135. This means the Purchases account is understated. To correct this, Purchases must be debited, and the Suspense Account credited.

    ParticularsDebit ($)Credit ($)Purchases135To Suspense Account135(To correct undercast of Purchases Day Book)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Purchases} & & 135 & \\ \quad \text{To Suspense Account} & & & 135 \\ \text{(To correct undercast of Purchases Day Book)} & & & \\ \end{array} }
  2. Journal Entry for Error (ii)

    A payment of $400 for Carriage Outwards was correctly recorded in the Cash Book but was not posted to the Carriage Outwards Account. This means the Carriage Outwards account is understated. To correct this, Carriage Outwards must be debited, and the Suspense Account credited.

    ParticularsDebit ($)Credit ($)Carriage Outwards400To Suspense Account400(To record unposted Carriage Outwards)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Carriage Outwards} & & 400 & \\ \quad \text{To Suspense Account} & & & 400 \\ \text{(To record unposted Carriage Outwards)} & & & \\ \end{array} }
  3. Journal Entry for Error (iii)

    Discounts Received of 87weredebitedtotheDiscountsAllowedAccount.DiscountsReceivedshouldbecredited,andDiscountsAllowedshouldnothavebeendebited.Tocorrect,creditDiscountsReceivedby87 were debited to the Discounts Allowed Account. Discounts Received should be credited, and Discounts Allowed should not have been debited. To correct, credit Discounts Received by 87 and credit Discounts Allowed by $87 to reverse the incorrect debit. The balancing debit goes to the Suspense Account.

    ParticularsDebit ($)Credit ($)Suspense Account174To Discounts Received87To Discounts Allowed87(To correct misposting of Discounts Received)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Suspense Account} & & 174 & \\ \quad \text{To Discounts Received} & & & 87 \\ \quad \text{To Discounts Allowed} & & & 87 \\ \text{(To correct misposting of Discounts Received)} & & & \\ \end{array} }
  4. Journal Entry for Error (iv)

    Interest Received of $168 was omitted from the Trial Balance. Interest Received is revenue and should be credited. The balancing debit goes to the Suspense Account.

    ParticularsDebit ($)Credit ($)Suspense Account168To Interest Received168(To record omitted Interest Received)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Suspense Account} & & 168 & \\ \quad \text{To Interest Received} & & & 168 \\ \text{(To record omitted Interest Received)} & & & \\ \end{array} }
  5. Journal Entry for Error (v)

    Sales Returns from a debtor totaling 390werecorrectlyrecordedintheSalesReturnsAccountbutwereincorrectlydebitedtothedebtor′saccount.SalesReturnsreducetheamountowedbyadebtor,sothedebtor′saccountshouldhavebeencredited.Tocorrecttheincorrectdebit,creditthedebtor′saccountby390 were correctly recorded in the Sales Returns Account but were incorrectly debited to the debtor's account. Sales Returns reduce the amount owed by a debtor, so the debtor's account should have been credited. To correct the incorrect debit, credit the debtor's account by 390. To record the correct reduction, credit the debtor's account by another $390. The balancing debit goes to the Suspense Account.

    ParticularsDebit ($)Credit ($)Suspense Account780To Accounts Receivable (Debtor)780(To correct incorrect debit to Debtor’s account for Sales Returns)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Suspense Account} & & 780 & \\ \quad \text{To Accounts Receivable (Debtor)} & & & 780 \\ \text{(To correct incorrect debit to Debtor's account for Sales Returns)} & & & \\ \end{array} }
  6. Journal Entry for Error (vi)

    A cash sale for 204wasdebitedtotheSalesAccountandcreditedtotheCashAccount.Foracashsale,CashshouldbedebitedandSalescredited.Tocorrect,debitCashby204 was debited to the Sales Account and credited to the Cash Account. For a cash sale, Cash should be debited and Sales credited. To correct, debit Cash by 204 (to reverse the incorrect credit) and another 204(forthecorrectdebit),totaling204 (for the correct debit), totaling 408. Credit Sales by 204(toreversetheincorrectdebit)andanother204 (to reverse the incorrect debit) and another 204 (for the correct credit), totaling $408.

    ParticularsDebit ($)Credit ($)Cash408To Sales408(To correct misposting of cash sale)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Cash} & & 408 & \\ \quad \text{To Sales} & & & 408 \\ \text{(To correct misposting of cash sale)} & & & \\ \end{array} }
  7. Journal Entries for Error (vii)

    The purchase of Equipment for $5,400 was debited to a Debtor's account.

    • First, correct the misposting: Debit Equipment by 5,400andcreditAccountsReceivable(Debtor)by5,400 and credit Accounts Receivable (Debtor) by 5,400 to reverse the incorrect debit.
    • Second, record depreciation: Calculate depreciation as 5,400×10%=5,400 \times 10\% = 540. Debit Depreciation Expense and credit Accumulated Depreciation.
    ParticularsDebit ($)Credit ($)Equipment5 400To Accounts Receivable (Debtor)5 400(To correct misposting of Equipment purchase)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Equipment} & & 5\,400 & \\ \quad \text{To Accounts Receivable (Debtor)} & & & 5\,400 \\ \text{(To correct misposting of Equipment purchase)} & & & \\ \end{array} } ParticularsDebit ($)Credit ($)Depreciation Expense540To Accumulated Depreciation - Equipment540(To record depreciation on new equipment)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Depreciation Expense} & & 540 & \\ \quad \text{To Accumulated Depreciation - Equipment} & & & 540 \\ \text{(To record depreciation on new equipment)} & & & \\ \end{array} }
  8. Journal Entry for Error (viii)

    Drawings of $4,862 made by the owner was only recorded in the bank account. This means the Drawings account was not debited. To correct this, debit Drawings and credit the Suspense Account.

    ParticularsDebit ($)Credit ($)Drawings4 862To Suspense Account4 862(To record unposted Drawings)\boxed{ \begin{array}{l l r r} \text{Particulars} & & \text{Debit (\$)} & \text{Credit (\$)} \\ \hline \text{Drawings} & & 4\,862 & \\ \quad \text{To Suspense Account} & & & 4\,862 \\ \text{(To record unposted Drawings)} & & & \\ \end{array} }
Was this helpful?

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp