
We read your photo as:
Prepare the consolidated statement of financial position of Ghana Ltd group as at 31 December 2013
Accounting
ScanSolve AI Answer
Answer
Step-by-step solution
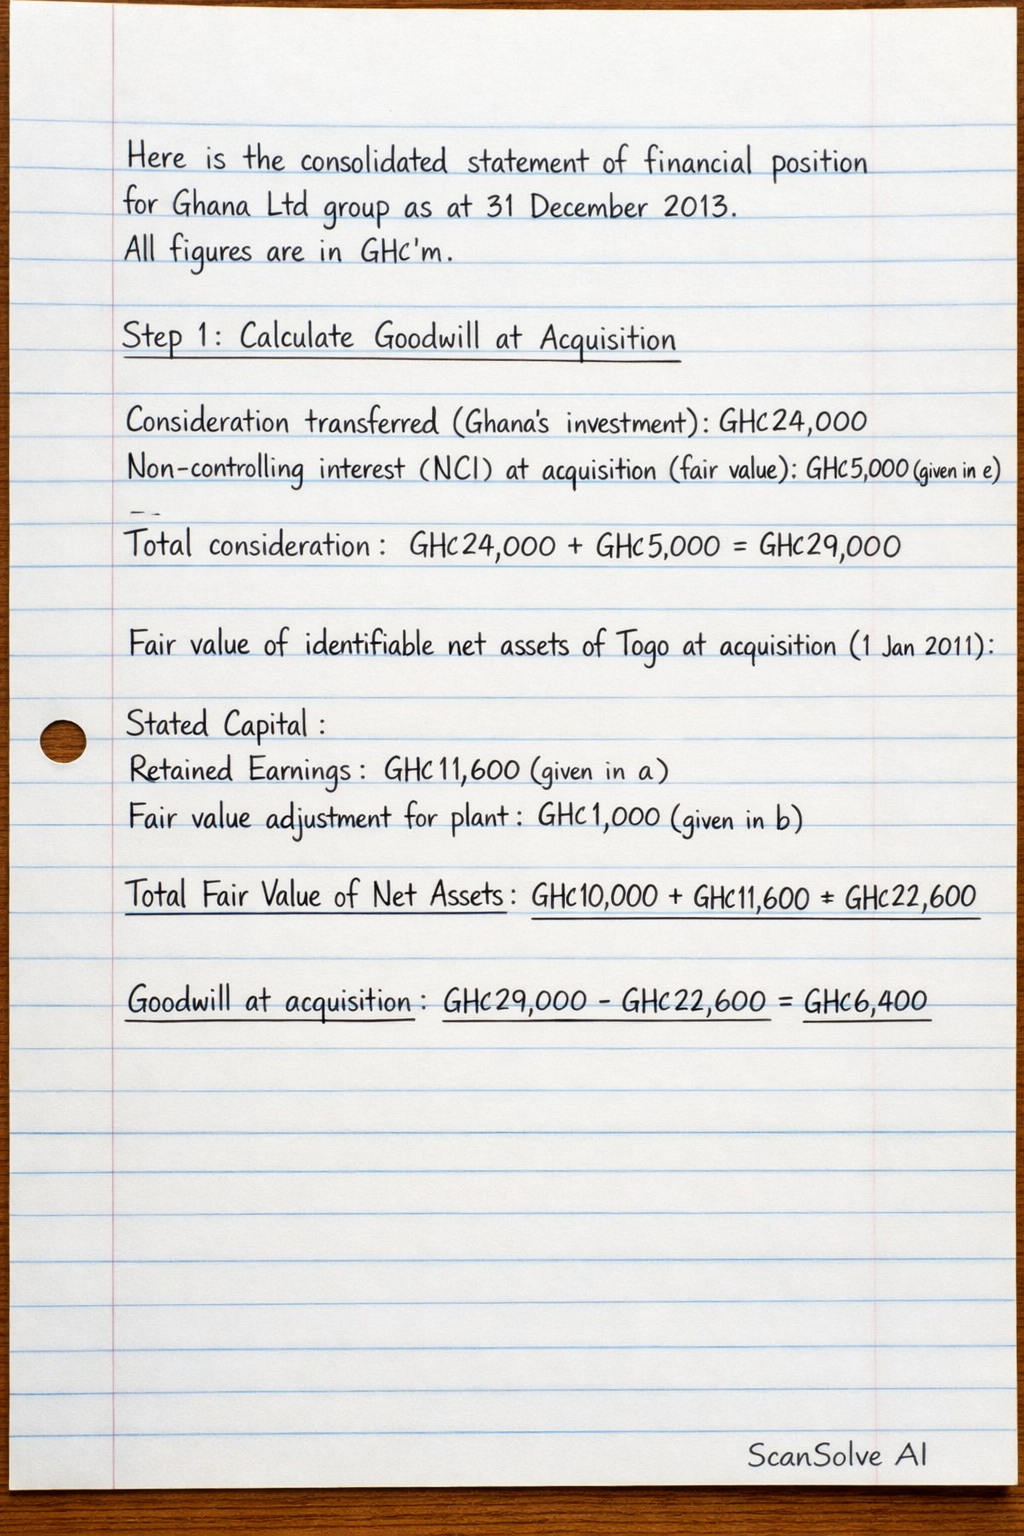
8 stepsHere is the consolidated statement of financial position for Ghana Ltd group as at 31 December 2013. All figures are in GH¢'m.
Calculate Goodwill at Acquisition
-
Consideration transferred (Ghana's investment): GH¢24,000
-
Non-controlling interest (NCI) at acquisition (fair value): GH¢5,000 (given in e)
-
Total consideration: GH¢24,000 + GH¢5,000 = GH¢29,000
-
Fair value of identifiable net assets of Togo at acquisition (1 Jan 2011):
- Stated Capital: GH¢10,000
- Retained Earnings: GH¢11,600 (given in a)
- Fair value adjustment for plant: GH¢1,000 (given in b)
- Total Fair Value of Net Assets: GH¢10,000 + GH¢11,600 + GH¢1,000 = GH¢22,600
-
Goodwill at acquisition: GH¢29,000 - GH¢22,600 = GH¢6,400
-
Adjust for Fair Value of Plant and Depreciation
- Fair value adjustment on plant: GH¢1,000
- Useful life: 10 years
- Annual depreciation on fair value adjustment: GH¢1,000 / 10 = GH¢100
- Period from acquisition (1 Jan 2011) to reporting date (31 Dec 2013): 3 years
- Total accumulated depreciation on fair value adjustment: GH¢100 3 = GH¢300
- Net carrying amount of fair value adjustment at 31 Dec 2013: GH¢1,000 - GH¢300 = GH¢700
Adjust for Unrealized Profit in Inventory
- Ghana sells goods to Togo at a markup of 25%. This means the profit margin on selling price is .
- Goods sold by Ghana to Togo in 2013: GH¢3,000 (given in d)
- One-third of these goods are still in Togo's inventory:
- Unrealized profit in closing inventory:
Adjust for Inter-company Balances and Cash in Transit
- Togo's payable to Ghana: GH¢1,100 (given in c)
- Ghana's receivable from Togo: GH¢1,500 (given in c)
- Difference (cash in transit): GH¢1,500 - GH¢1,100 = GH¢400
- Consolidation adjustments:
- Eliminate GH¢1,100 from Trade Receivables and Trade Payables.
- Add GH¢400 to Cash and Cash Equivalents.
- Reduce Trade Receivables by GH¢400 (as it's no longer a receivable but cash in transit).
Calculate Goodwill at Reporting Date
- Goodwill at acquisition: GH¢6,400 (from Step 1)
- Impairment loss: GH¢2,000 (given in f)
- Goodwill at reporting date: GH¢6,400 - GH¢2,000 = GH¢4,400
Calculate Non-Controlling Interest (NCI) at Reporting Date
- NCI at acquisition: GH¢5,000
- Togo's post-acquisition retained earnings: GH¢15,800 (RE at 31/12/13) - GH¢11,600 (RE at 01/01/11) = GH¢4,200
- NCI share of post-acquisition retained earnings:
- NCI share of fair value depreciation: (reduction)
- NCI share of goodwill impairment: (reduction)
- NCI at reporting date: GH¢5,000 + GH¢840 - GH¢60 - GH¢400 = GH¢5,380
Calculate Consolidated Retained Earnings
- Ghana's retained earnings: GH¢25,200
- Ghana's share of Togo's post-acquisition retained earnings:
- Ghana's share of fair value depreciation: (reduction)
- Unrealized profit in inventory: GH¢200 (reduction, fully attributable to parent)
- Ghana's share of goodwill impairment: (reduction)
- Consolidated Retained Earnings: GH¢25,200 + GH¢3,360 - GH¢240 - GH¢200 - GH¢1,600 = GH¢26,520
Prepare Consolidated Statement of Financial Position
Was this helpful?
Try one yourself
A new problem that tests the same skill.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
Got a different question?Ask your own question
More Accounting Questions
QConsolidated statement of Financial position of Ghana Ltd as at 31 December 2013 of the above…QPrepare consolidated statement of comprehensive income for the year ended 31 December 2013 from the…QPrepare a consolidated statement of profit and loss and other comprehensive income for the year…QVeronica acquired 80% of the shares of Ghana Ltd on 1 January 2009 for GHȻ500 million, on which date…QPrepare the "Asset" section of the statement of financial position for All Ltd at 31 December 19.9…
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp