
We read your photo as:
Question 1: COMPANY FINANCIAL STATEMENTS The information relates to ZOZIE (PTY) LTD, a stationery retailer, for the year ended 28 February 2026.
Accounting
ScanSolve AI Answer
Answer
Step-by-step solution
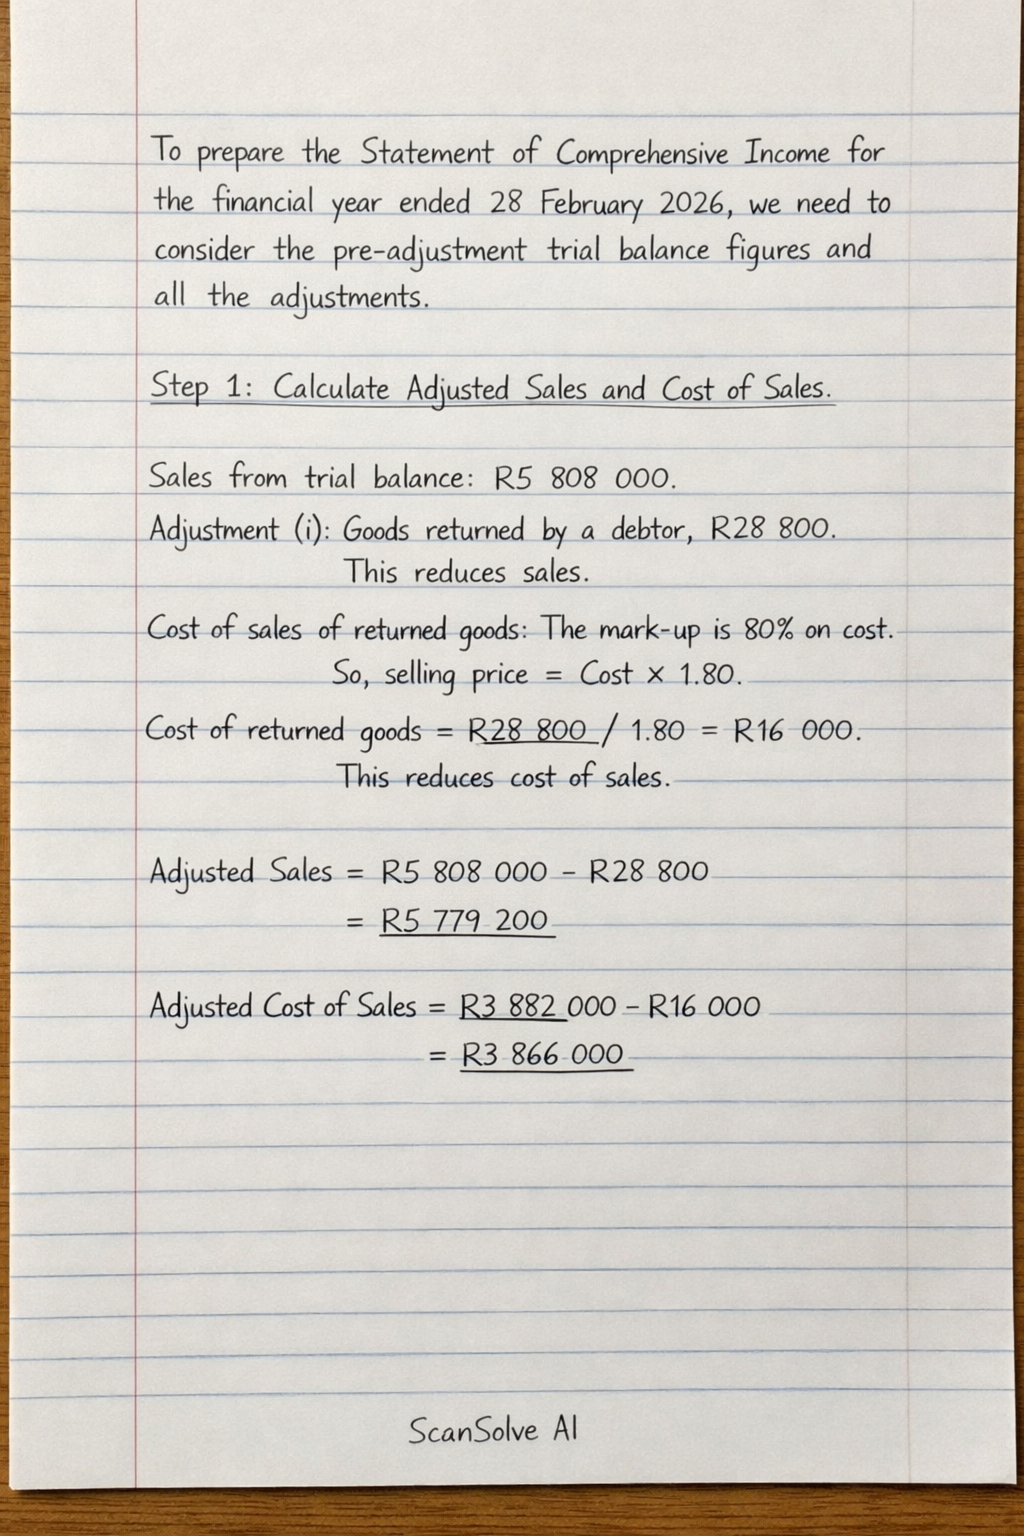
5 stepsTo prepare the Statement of Comprehensive Income for the financial year ended 28 February 2026, we need to consider the pre-adjustment trial balance figures and all the adjustments.
Calculate Adjusted Sales and Cost of Sales.
- Sales from trial balance: R5 808 000
- Adjustment (i): Goods returned by a debtor, R28 800. This reduces sales.
- Cost of sales of returned goods: The mark-up is 80% on cost. So, selling price = Cost 1.80. Cost of returned goods = R28 800 / 1.80 = R16 000. This reduces cost of sales.
Calculate Adjusted Other Operating Income.
- Discount received from trial balance: R14 000
- Rent income from trial balance: R450 000
- Adjustment (iii): Rent was paid up to 30 April 2026. The financial year ends 28 February 2026. This means rent for March and April 2026 (2 months) is unearned. The rent increased by 15% from 1 July 2025. Let be the monthly rent before 1 July 2025. Let be the monthly rent from 1 July 2025 (). The R450 000 received covers: 4 months (March 2025 - June 2025) at 10 months (July 2025 - April 2026) at
Unearned rent (March 2026 and April 2026) = $2 \times R_{new} = 2 \times \text{R}33\,387.09 = \text{R}66\,774.18$. Adjusted Rent income = R450 000 - R66 774.18 = R383 225.82. Rounded to R383 226.- Adjustment (iv): Stock surplus of calculators. Units available for sale = Opening stock (600) + Purchases (2 650) - Returns (185) = 3 065 units. Expected closing stock = Units available for sale (3 065) - Units sold (2 745) = 320 units. Actual closing stock = 430 units. Stock surplus = 430 - 320 = 110 units. Value of stock surplus = 110 units R175/unit = R19 250. This is other operating income.
Calculate Adjusted Operating Expenses.
- Depreciation from trial balance: R285 500 (No adjustment)
- Insurance from trial balance: R132 600
- Adjustment (ii): Annual premium of R14 400 covers 1 April 2025 to 31 March 2026. The financial year ends 28 February 2026. Prepaid insurance for March 2026 = R14 400 / 12 months = R1 200. Adjusted Insurance = R132 600 - R1 200 = R131 400.
- Directors' fees from trial balance: R492 000 (Adjustment (v) confirms fees were received for the current year, so no adjustment to the expense amount).
- Salaries and wages from trial balance: R850 000
- Adjustment (vi): Omitted clerk's salary. Net salary R9 424 is 76% (100% - 24% deductions) of gross salary. Gross salary = R9 424 / 0.76 = R12 400. Employer contributions = R1 240. Additional Salaries and Wages expense = R12 400 (gross salary) + R1 240 (employer contributions) = R13 640. Adjusted Salaries and Wages = R850 000 + R13 640 = R863 640.
- Audit fees from trial balance: R23 400
- Adjustment (vii): Adjusted assessment for audit fees is R30 500. Adjusted Audit fees = R30 500.
- Sundry expenses from trial balance: R128 000 (No adjustment)
Calculate Interest Income and Interest Expense.
- Interest income from trial balance: R5 700 (No adjustment)
- No interest expense is given in the trial balance or adjustments for the Luther Bank loan. Assume R0.
Prepare the Statement of Comprehensive Income.
Note: The SARS: Income tax of R882 000 from the trial balance is treated as the income tax expense for the year, as no further information (e.g., tax rate) is provided to calculate the actual tax liability.
Was this helpful?
Try one yourself
A new problem that tests the same skill.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
Got a different question?Ask your own question
More Accounting Questions
QQUESTION 1: COMPANY FINANCIAL STATEMENTS The following information was taken from the accounting…QPrepare a Statement of Financial Position for XYZ Merchandisers as at 31st December 2024.QComplete the Statement of Financial Position as at 28 February 2023.QPrepare the Statement of Profit or Loss and Other Comprehensive Income for Kwagga Packaging CC for…QPrepare the Statement of Changes in Equity for Stratos Ltd for the year ended 28 February 2026.
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp