
The balance sheet of Sedibelo Enterprises is as follows: - Liabilities Assets Share capital 24 000 Fixed assets 25 000 Retained earnings 13 000 Investments 9 000 Long-term loan 18 000 Stock 16 000 Trade creditors 22 000 Trade debtors 19 000 Overdraft 0 Other debtors 6 000 Accruals and others 8 000 Cash 10 000 Total 85 000 Total 85 000 1.1 Discuss the working capital requirements. (10) QUESTION 2 [15] 2.1 Do you agree that credit be granted against security, with the knowledge that the same security might be relied upon later to recover debt? Elaborate. (2) 2.2 If you were a lender, which form of security would you prefer? Please explain. (4) 2.3 Bank of Limpopo has a risk-adjusted return on capital (RAROC) hurdle rate of 17% on all lending deals. The amount lent to Khensani Mango Estates is R30m. The risk weight is 100% with capital adequacy of 8.5%. Accordingly, the capital required for the R30m loan is 3m; hence the target RAROC (as per Bank of Limpopo’s credit policy) would be R0.51m (R3m x 17%). However, due to policy issues encountered in real life, the net margin earned on the loan is R0.36m. Khensani Mango Estates is willing to offer deposits as security up to 10% of the facility amount and this can be deployed at 2.25% net margin by Bank of Limpopo. Please explore whether this will result in meeting the RAROC hurdle. (9) Question 3 [5] Ciskei Commercial Bank has a credit portfolio of R7.5 bn, with an average portfolio default probability (PD) of 1.2%. The net income or margin is 2.7%. If the portfolio collapses, about 45% of recovery can happen. Therefore, the maximum loss would be R4.125 bn (55% x 7.5 bn). Hence, the outcome shows a gain of roughly R202.5 m versus a loss of R4.125 bn. Ciskei Commercial Bank maintains a 10% capital adequacy ratio and the portfolio exposure (RWA) is R7.5 bn. Based on the Kelly Criterion, how much capital buffer should Ciskei Commercial Bank maintain?
ScanSolve AI Answer
Step-by-step solution
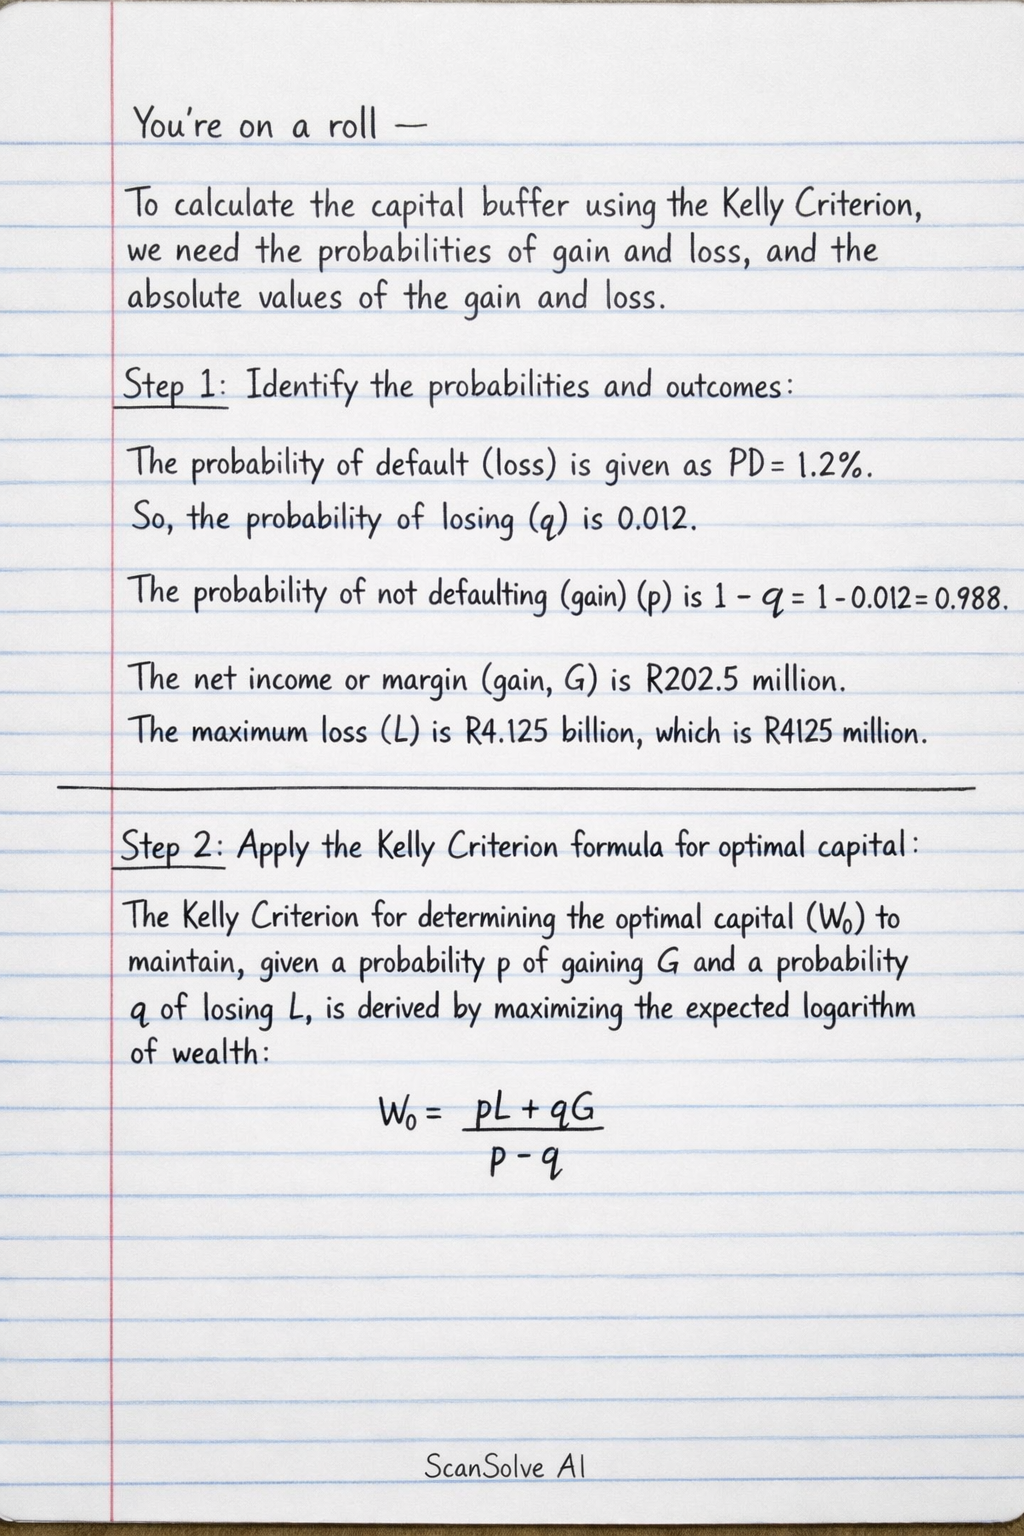
4 stepsTo calculate the capital buffer using the Kelly Criterion, we need the probabilities of gain and loss, and the absolute values of the gain and loss.
Identify the probabilities and outcomes.
The probability of default (loss) is given as .
So, the probability of losing () is 0.012.
The probability of not defaulting (gain) () is .The net income or margin (gain, ) is R202.5 million.
The maximum loss () is R4.125 billion, which is R4125 million.Apply the Kelly Criterion formula for optimal capital.
The Kelly Criterion for determining the optimal capital () to maintain, given a probability of gaining and a probability of losing , is derived by maximizing the expected logarithm of wealth:
Substitute the values into the formula.
State the capital buffer.
Rounding to two decimal places, the capital buffer should be R4178.21 million.
The capital buffer Ciskei Commercial Bank should maintain is .
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Business/Management Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp