We read your photo as:

Emily wants to buy a house. The purchase price is R1 620 000. Calculate the amount financed.

Mathematics

ScanSolve AI Answer

Step-by-step solution

12 steps

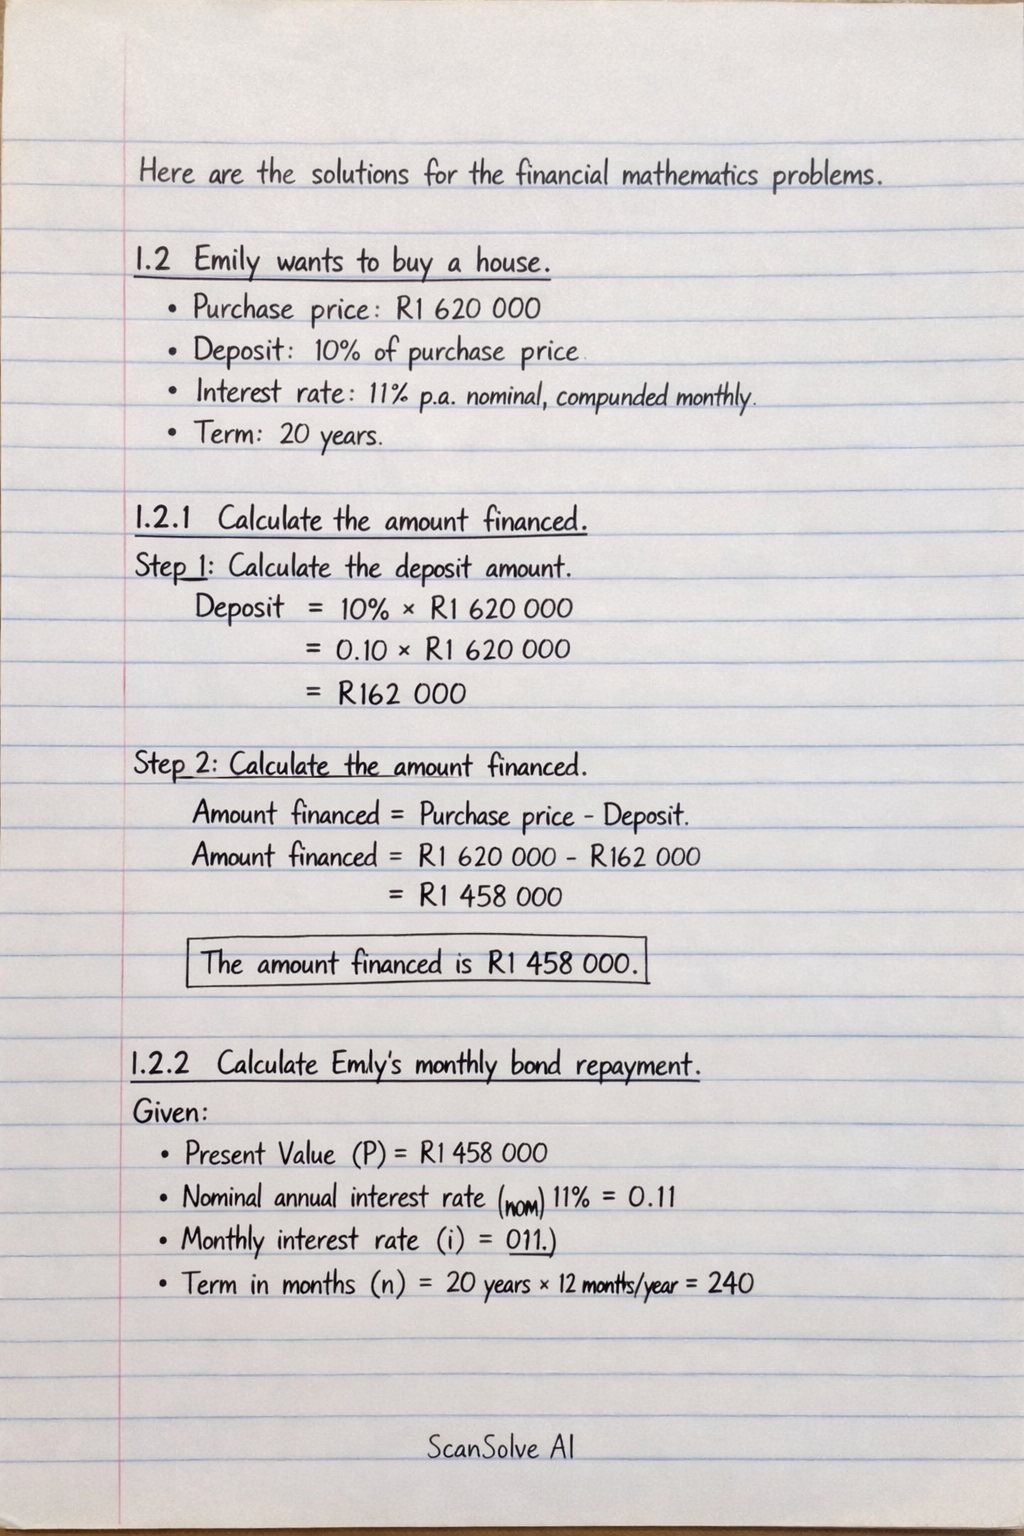
Here are the solutions for the financial mathematics problems.

1.2 Emily wants to buy a house.

  • Purchase price: R1 620 000
  • Deposit: 10% of purchase price
  • Interest rate: 11% p.a. nominal, compounded monthly
  • Term: 20 years

1.2.1 Calculate the amount financed.

  1. Calculate the deposit amount.

    Deposit=10%×R1 620 000=0.10×R1 620 000=R162 000\text{Deposit} = 10\% \times \text{R}1\,620\,000 = 0.10 \times \text{R}1\,620\,000 = \text{R}162\,000
  2. Calculate the amount financed.

    Amount financed=Purchase price−Deposit\text{Amount financed} = \text{Purchase price} - \text{Deposit} Amount financed=R1 620 000−R162 000=R1 458 000\text{Amount financed} = \text{R}1\,620\,000 - \text{R}162\,000 = \text{R}1\,458\,000

    The amount financed is R1 458 000\boxed{\text{R}1\,458\,000}.

    1.2.2 Calculate Emily's monthly bond repayment.
    Given:

    • Present Value (PP) = R1 458 000
    • Nominal annual interest rate (inomi_{nom}) = 11% = 0.11
    • Monthly interest rate (ii) = 0.1112\frac{0.11}{12}
    • Term in months (nn) = 20 years×12 months/year=24020 \text{ years} \times 12 \text{ months/year} = 240
  3. Use the present value annuity formula to find the monthly repayment (xx).

    P=x[1−(1+i)−n]iP = \frac{x[1 - (1+i)^{-n}]}{i} R1 458 000=x[1−(1+0.1112)−240]0.1112\text{R}1\,458\,000 = \frac{x[1 - (1 + \frac{0.11}{12})^{-240}]}{\frac{0.11}{12}}
  4. Solve for xx.

    x=R1 458 000×0.11121−(1+0.1112)−240x = \frac{\text{R}1\,458\,000 \times \frac{0.11}{12}}{1 - (1 + \frac{0.11}{12})^{-240}} x=133551−(1.00916666666)−240x = \frac{13355}{1 - (1.00916666666)^{-240}} x=133551−0.11200696x = \frac{13355}{1 - 0.11200696} x=133550.88799304x = \frac{13355}{0.88799304} x≈R15 039.50x \approx \text{R}15\,039.50

    Emily's monthly bond repayment is R15 039.50\boxed{\text{R}15\,039.50}.

    1.2.3 How much will Emily have paid back in total at the end of the 20 years?

  5. Calculate the total amount paid.

    Total paid=Monthly repayment×Number of payments\text{Total paid} = \text{Monthly repayment} \times \text{Number of payments} Total paid=R15 039.50×240\text{Total paid} = \text{R}15\,039.50 \times 240 Total paid=R3 609 480.00\text{Total paid} = \text{R}3\,609\,480.00

    Emily will have paid back a total of R3 609 480.00\boxed{\text{R}3\,609\,480.00}.

    1.2.4 If Emily decides to pay an extra R1 500 at the end of each month, how many years will it take to settle her bond?
    New monthly repayment (xnewx_{new}) = R15 039.50 + R1 500 = R16 539.50
    P=R1 458 000P = \text{R}1\,458\,000
    i=0.1112i = \frac{0.11}{12}

  6. Use the present value annuity formula to solve for the new number of payments (nnewn_{new}).

    P=xnew[1−(1+i)−nnew]iP = \frac{x_{new}[1 - (1+i)^{-n_{new}}]}{i} R1 458 000=R16 539.50[1−(1+0.1112)−nnew]0.1112\text{R}1\,458\,000 = \frac{\text{R}16\,539.50[1 - (1 + \frac{0.11}{12})^{-n_{new}}]}{\frac{0.11}{12}}

    Rearrange to solve for nnewn_{new}:

    (1+0.1112)−nnew=1−R1 458 000×0.1112R16 539.50(1 + \frac{0.11}{12})^{-n_{new}} = 1 - \frac{\text{R}1\,458\,000 \times \frac{0.11}{12}}{\text{R}16\,539.50} (1.00916666666)−nnew=1−1335516539.50(1.00916666666)^{-n_{new}} = 1 - \frac{13355}{16539.50} (1.00916666666)−nnew≈1−0.8074099(1.00916666666)^{-n_{new}} \approx 1 - 0.8074099 (1.00916666666)−nnew≈0.1925901(1.00916666666)^{-n_{new}} \approx 0.1925901
  7. Use logarithms to solve for nnewn_{new}.

    −nnewln⁡(1.00916666666)=ln⁡(0.1925901)-n_{new} \ln(1.00916666666) = \ln(0.1925901) nnew=−ln⁡(0.1925901)ln⁡(1.00916666666)n_{new} = -\frac{\ln(0.1925901)}{\ln(1.00916666666)} nnew≈−−1.647360.009124≈180.55 monthsn_{new} \approx -\frac{-1.64736}{0.009124} \approx 180.55 \text{ months}
  8. Convert months to years.

    Years=180.5512≈15.046 years\text{Years} = \frac{180.55}{12} \approx 15.046 \text{ years}

    It will take approximately 15.05 years\boxed{15.05 \text{ years}} to settle her bond.

    1.3 Rushaana is comparing two home loan options.

    • Property price: R1 800 000
    • Deposit: R180 000
    • Amount financed (PP) = R1 800 000 - R180 000 = R1 620 000

    1.3.1 Calculate the monthly repayment for each option.
    Formula: x=P⋅i1−(1+i)−nx = \frac{P \cdot i}{1 - (1+i)^{-n}}

    Imrah Bank:

    • P=R1 620 000P = \text{R}1\,620\,000
    • i=0.107512i = \frac{0.1075}{12}
    • n=20 years×12=240n = 20 \text{ years} \times 12 = 240 months
  9. Calculate monthly repayment for Imrah Bank.

    xImrah=R1 620 000×0.1075121−(1+0.107512)−240x_{\text{Imrah}} = \frac{\text{R}1\,620\,000 \times \frac{0.1075}{12}}{1 - (1 + \frac{0.1075}{12})^{-240}} xImrah=14587.51−(1.00895833333)−240x_{\text{Imrah}} = \frac{14587.5}{1 - (1.00895833333)^{-240}} xImrah=14587.51−0.120538x_{\text{Imrah}} = \frac{14587.5}{1 - 0.120538} xImrah=14587.50.879462≈R16 586.20x_{\text{Imrah}} = \frac{14587.5}{0.879462} \approx \text{R}16\,586.20

    Endinako Bank:

    • P=R1 620 000P = \text{R}1\,620\,000
    • i=0.099512i = \frac{0.0995}{12}
    • n=25 years×12=300n = 25 \text{ years} \times 12 = 300 months
  10. Calculate monthly repayment for Endinako Bank.

    xEndinako=R1 620 000×0.0995121−(1+0.099512)−300x_{\text{Endinako}} = \frac{\text{R}1\,620\,000 \times \frac{0.0995}{12}}{1 - (1 + \frac{0.0995}{12})^{-300}} xEndinako=13447.51−(1.00829166666)−300x_{\text{Endinako}} = \frac{13447.5}{1 - (1.00829166666)^{-300}} xEndinako=13447.51−0.082725x_{\text{Endinako}} = \frac{13447.5}{1 - 0.082725} xEndinako=13447.50.917275≈R14 659.80x_{\text{Endinako}} = \frac{13447.5}{0.917275} \approx \text{R}14\,659.80

    The monthly repayment for Imrah Bank is R16 586.20\boxed{\text{R}16\,586.20} and for Endinako Bank is R14 659.80\boxed{\text{R}14\,659.80}.

    1.3.2 Calculate the total amount Rushaana will pay back over the term of each loan.

    Imrah Bank:

  11. Calculate total paid for Imrah Bank.

    Total paidImrah=Monthly repayment×Number of payments\text{Total paid}_{\text{Imrah}} = \text{Monthly repayment} \times \text{Number of payments} Total paidImrah=R16 586.20×240=R3 980 688.00\text{Total paid}_{\text{Imrah}} = \text{R}16\,586.20 \times 240 = \text{R}3\,980\,688.00

    Endinako Bank:

  12. Calculate total paid for Endinako Bank.

    Total paidEndinako=Monthly repayment×Number of payments\text{Total paid}_{\text{Endinako}} = \text{Monthly repayment} \times \text{Number of payments} Total paidEndinako=R14 659.80×300=R4 397 940.00\text{Total paid}_{\text{Endinako}} = \text{R}14\,659.80 \times 300 = \text{R}4\,397\,940.00

    The total amount paid for Imrah Bank is R3 980 688.00\boxed{\text{R}3\,980\,688.00} and for Endinako Bank is R4 397 940.00\boxed{\text{R}4\,397\,940.00}.

    1.3.3 Which option is the better choice overall? Motivate your answer fully by comparing both the monthly repayments and the total amount paid.

    • Monthly Repayment: Endinako Bank has a lower monthly repayment of R14 659.80 compared to Imrah Bank's R16 586.20. This makes Endinako Bank more affordable on a month-to-month basis.
    • Total Amount Paid: Imrah Bank results in a total payment of R3 980 688.00, which is R417 252.00 less than Endinako Bank's total payment of R4 397 940.00. Imrah Bank also has a shorter loan term (20 years vs. 25 years).

    Conclusion:
    If Rushaana can comfortably afford the higher monthly repayment, Imrah Bank is the better choice overall. This is because it results in a significantly lower total amount paid over the life of the loan (saving R417 252.00) and allows her to pay off the loan 5 years sooner. However, if monthly affordability is a critical concern, Endinako Bank offers a lower monthly payment, albeit at a higher total cost and longer term.

Was this helpful?

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp