We read your photo as:

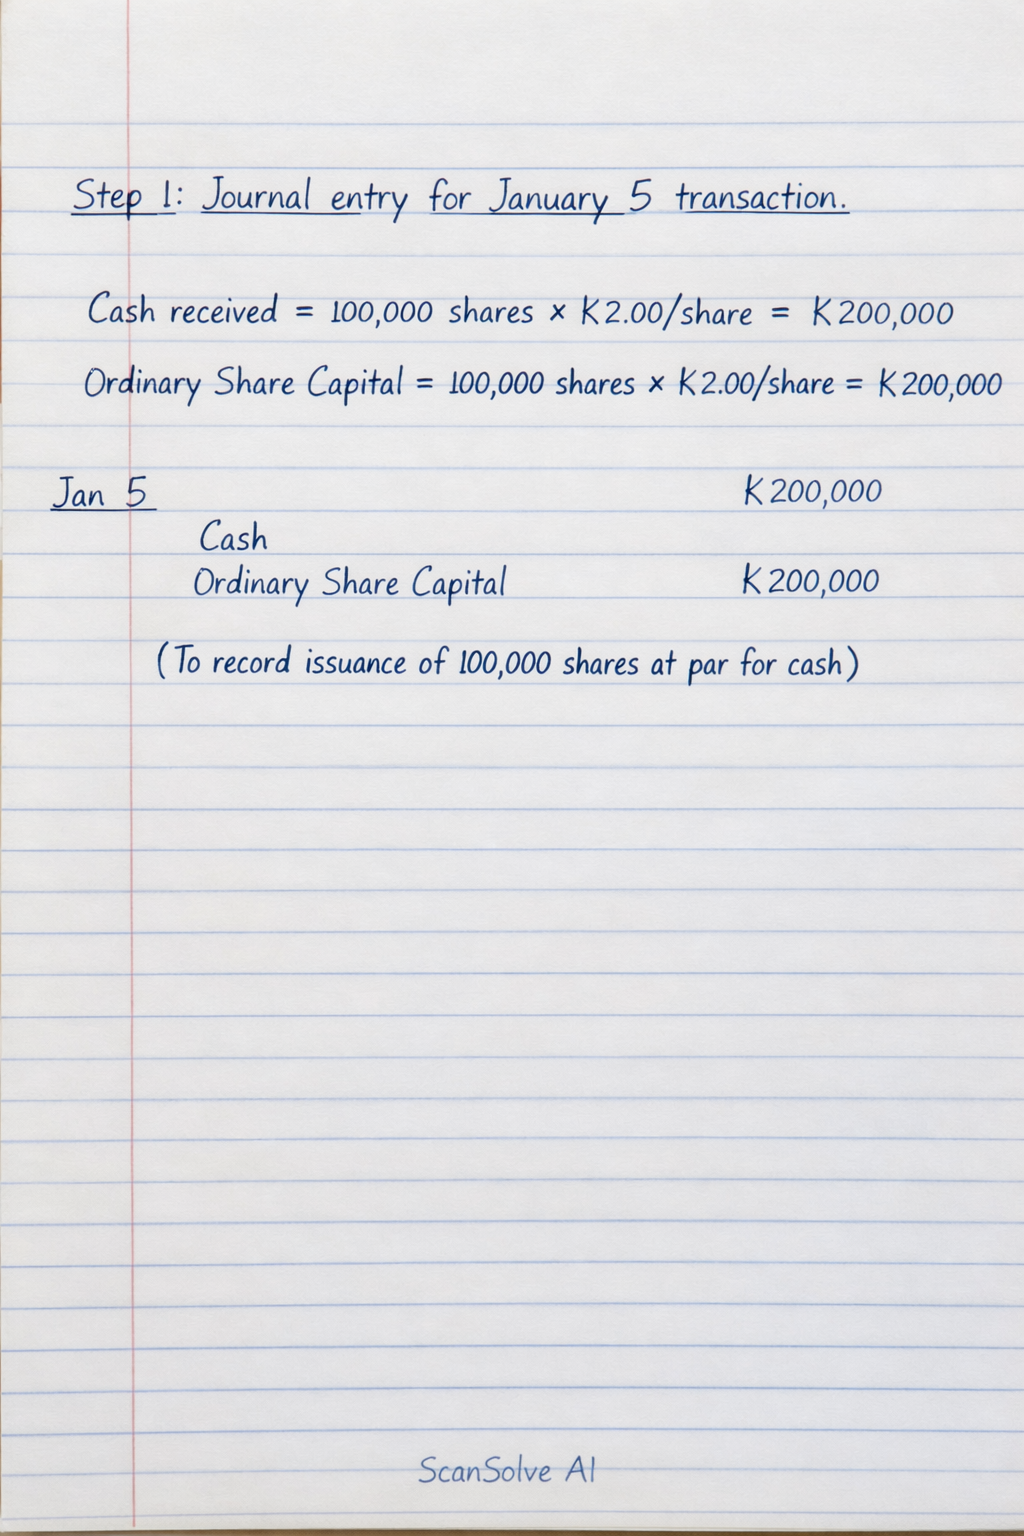
Journal entry for January 5 transaction.

Accounting

ScanSolve AI Answer

Answers

2 parts
b

K75,000\text{K}75,000

c

465,000\textbf{465,000}

Step-by-step solution

6 steps

Part a· 3 steps

Prepare the journal entries for each of the three transactions.

  1. Journal entry for January 5 transaction.

    The company issued 100,000 ordinary shares at K2.00 par value for cash.

    Cash received=100,000 shares×K2.00/share=K200,000\text{Cash received} = 100,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}200,000 Ordinary Share Capital=100,000 shares×K2.00/share=K200,000\text{Ordinary Share Capital} = 100,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}200,000

    \begin{align*} Jan 5 && Cash && K200,000 \ && Ordinary Share Capital && && K200,000 \ && (To record issuance of 100,000 shares at par for cash) \end{align*}

  2. Journal entry for January 12 transaction.

    The company issued 50,000 ordinary shares at K3.50 each (above par). The par value is K2.00.

    Cash received=50,000 shares×K3.50/share=K175,000\text{Cash received} = 50,000 \text{ shares} \times \text{K}3.50/\text{share} = \text{K}175,000 Ordinary Share Capital=50,000 shares×K2.00/share=K100,000\text{Ordinary Share Capital} = 50,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}100,000 Share Premium=Cash received−Ordinary Share Capital=K175,000−K100,000=K75,000\text{Share Premium} = \text{Cash received} - \text{Ordinary Share Capital} = \text{K}175,000 - \text{K}100,000 = \text{K}75,000

    \begin{align*} Jan 12 && Cash && K175,000 \ && Ordinary Share Capital && && K100,000 \ && Share Premium && && K75,000 \ && (To record issuance of 50,000 shares above par for cash) \end{align*}

  3. Journal entry for January 20 transaction.

    The company issued 20,000 ordinary shares in exchange for land and equipment with a fair value of K90,000. The par value is K2.00.

    Land and Equipment (Fair Value)=K90,000\text{Land and Equipment (Fair Value)} = \text{K}90,000 Ordinary Share Capital=20,000 shares×K2.00/share=K40,000\text{Ordinary Share Capital} = 20,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}40,000 Share Premium=Fair Value of Asset−Ordinary Share Capital=K90,000−K40,000=K50,000\text{Share Premium} = \text{Fair Value of Asset} - \text{Ordinary Share Capital} = \text{K}90,000 - \text{K}40,000 = \text{K}50,000

    \begin{align*} Jan 20 && Land and Equipment && K90,000 \ && Ordinary Share Capital && && K40,000 \ && Share Premium && && K50,000 \ && (To record issuance of 20,000 shares for land and equipment) \end{align*}

Part b

K75,000\text{K}75,000

Identify and explain the Share Premium (Additional Paid-In Capital) arising from the January 12 transaction.

Share Premium (also known as Additional Paid-In Capital) is the amount of money shareholders pay for shares that is above the par value of those shares. It represents the excess of the issue price over the par value.

For the January 12 transaction:

Issue Price per share=K3.50\text{Issue Price per share} = \text{K}3.50 Par Value per share=K2.00\text{Par Value per share} = \text{K}2.00 Premium per share=K3.50−K2.00=K1.50\text{Premium per share} = \text{K}3.50 - \text{K}2.00 = \text{K}1.50 Number of shares issued=50,000\text{Number of shares issued} = 50,000 Total Share Premium=50,000 shares×K1.50/share=K75,000\text{Total Share Premium} = 50,000 \text{ shares} \times \text{K}1.50/\text{share} = \boxed{\text{K}75,000}

Part c

465,000\textbf{465,000}

Prepare the Shareholders' Equity section of the Statement of Financial Position as at 31 January 2024 (assume no profits yet).

  1. Calculate total Ordinary Share Capital.

    • From Jan 5: 100,000 shares×K2.00/share=K200,000100,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}200,000
    • From Jan 12: 50,000 shares×K2.00/share=K100,00050,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}100,000
    • From Jan 20: 20,000 shares×K2.00/share=K40,00020,000 \text{ shares} \times \text{K}2.00/\text{share} = \text{K}40,000
    Total Ordinary Share Capital=K200,000+K100,000+K40,000=K340,000\text{Total Ordinary Share Capital} = \text{K}200,000 + \text{K}100,000 + \text{K}40,000 = \text{K}340,000
  2. Calculate total Share Premium.

    • From Jan 5: K0 (issued at par)
    • From Jan 12: K75,000
    • From Jan 20: K50,000
    Total Share Premium=K75,000+K50,000=K125,000\text{Total Share Premium} = \text{K}75,000 + \text{K}50,000 = \text{K}125,000
  3. Prepare the Shareholders' Equity section.

    Since no profits are assumed, Retained Earnings will be K0.

    Kumul Fisheries Corporation Ltd
    Statement of Financial Position (Extract)
    As at 31 January 2024

    Shareholders’ EquityKOrdinary Share Capital340,000Share Premium125,000Retained Earnings0Total Shareholders’ Equity465,000\begin{array}{l r} \textbf{Shareholders' Equity} & \textbf{K} \\ \text{Ordinary Share Capital} & 340,000 \\ \text{Share Premium} & 125,000 \\ \text{Retained Earnings} & 0 \\ \hline \textbf{Total Shareholders' Equity} & \boxed{\textbf{465,000}} \\ \end{array}
Was this helpful?

Try one yourself

A new problem that tests the same skill.

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp