
We read your photo as:
Prepare a non-current asset schedule clearly showing the movements in both the cost and depreciation for the categories of the assets listed.
Accounting
ScanSolve AI Answer
Answer
To prepare the non-current asset schedule, we will calculate the movements in cost and accumulated depreciation for Buildings, Motor Vehicles, and Equipment. The year ends on 31 May 2010.
Step-by-step solution
5 stepsNon-Current Asset Schedule for the year ended 31 May 2010
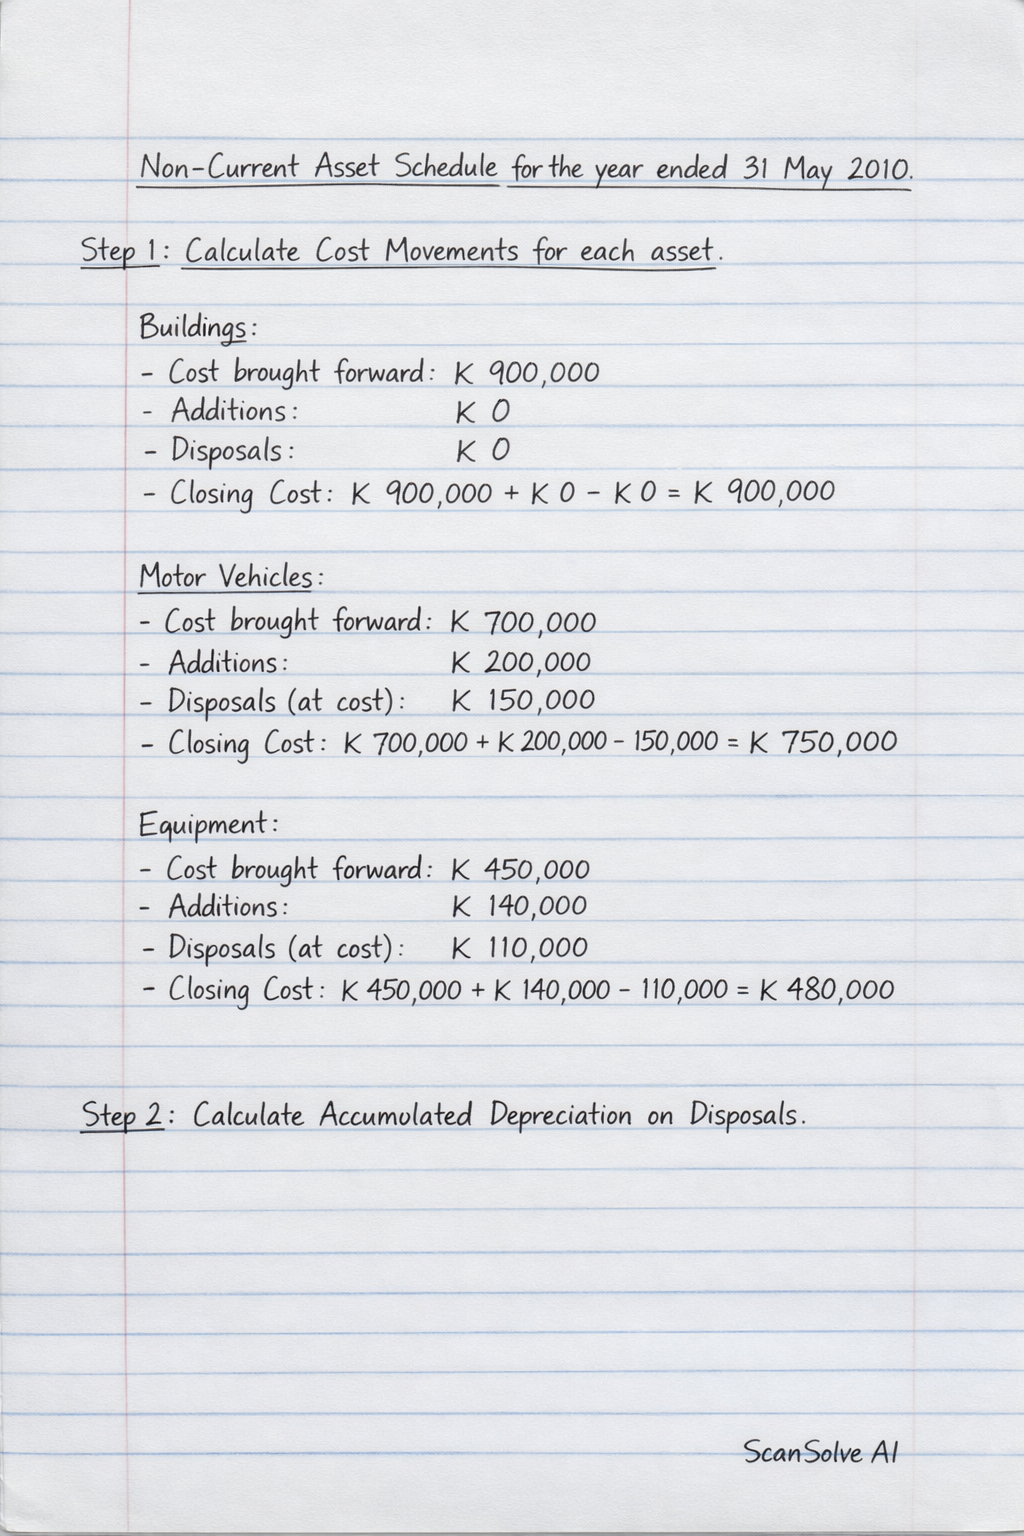
Calculate Cost Movements for each asset.
-
Buildings:
- Cost brought forward: K 900,000
- Additions: K 0
- Disposals: K 0
- Closing Cost: K 900,000 + K 0 - K 0 = K 900,000
-
Motor Vehicles:
- Cost brought forward: K 700,000
- Additions: K 200,000
- Disposals (at cost): K 150,000
- Closing Cost: K 700,000 + K 200,000 - K 150,000 = K 750,000
-
Equipment:
- Cost brought forward: K 450,000
- Additions: K 140,000
- Disposals (at cost): K 110,000
- Closing Cost: K 450,000 + K 140,000 - K 110,000 = K 480,000
-
Calculate Accumulated Depreciation on Disposals.
-
Motor Vehicles:
- Cost of disposed vehicle: K 150,000
- Net Book Value (NBV) of disposed vehicle: K 80,000
- Accumulated depreciation on disposal: K 150,000 - K 80,000 = K 70,000
-
Equipment:
- Cost of disposed equipment: K 110,000
- Net Book Value (NBV) of disposed equipment: K 50,000
- Accumulated depreciation on disposal: K 110,000 - K 50,000 = K 60,000
-
Calculate Depreciation for the Year.
-
Buildings (2% per annum on cost):
- Depreciation = K 900,000 2% = K 18,000
-
Motor Vehicles (20% straight line):
- Depreciation on assets held for full year: (K 700,000 - K 150,000) 20% = K 550,000 20% = K 110,000
- Depreciation on additions: K 200,000 20% = K 40,000
- Total depreciation for the year: K 110,000 + K 40,000 = K 150,000
-
Equipment (10% reducing balance method):
- Depreciation on assets held for full year:
- Cost of remaining assets: K 450,000 - K 110,000 = K 340,000
- Accumulated depreciation on remaining assets (opening): K 100,000 (total b/f) - K 60,000 (disposed) = K 40,000
- Net Book Value of remaining assets (opening): K 340,000 - K 40,000 = K 300,000
- Depreciation on remaining assets: K 300,000 10% = K 30,000
- Depreciation on additions: K 140,000 10% = K 14,000
- Total depreciation for the year: K 30,000 + K 14,000 = K 44,000
- Depreciation on assets held for full year:
-
Calculate Accumulated Depreciation Closing Balances.
-
Buildings:
- Opening Acc. Dep.: K 40,000
- Depreciation on disposals: K 0
- Depreciation for the year: K 18,000
- Closing Acc. Dep.: K 40,000 - K 0 + K 18,000 = K 58,000
-
Motor Vehicles:
- Opening Acc. Dep.: K 120,000
- Depreciation on disposals: K 70,000
- Depreciation for the year: K 150,000
- Closing Acc. Dep.: K 120,000 - K 70,000 + K 150,000 = K 200,000
-
Equipment:
- Opening Acc. Dep.: K 100,000
- Depreciation on disposals: K 60,000
- Depreciation for the year: K 44,000
- Closing Acc. Dep.: K 100,000 - K 60,000 + K 44,000 = K 84,000
-
Prepare the Non-Current Asset Schedule.
Was this helpful?
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
Got a different question?Ask your own question
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp