
We read your photo as:
Prepare the Division of net income and Prepare the partnership financial statement for the first question. For the second question, prepare the partnership liquidation journal entries for sagastina.
ScanSolve AI Answer
Step-by-step solution
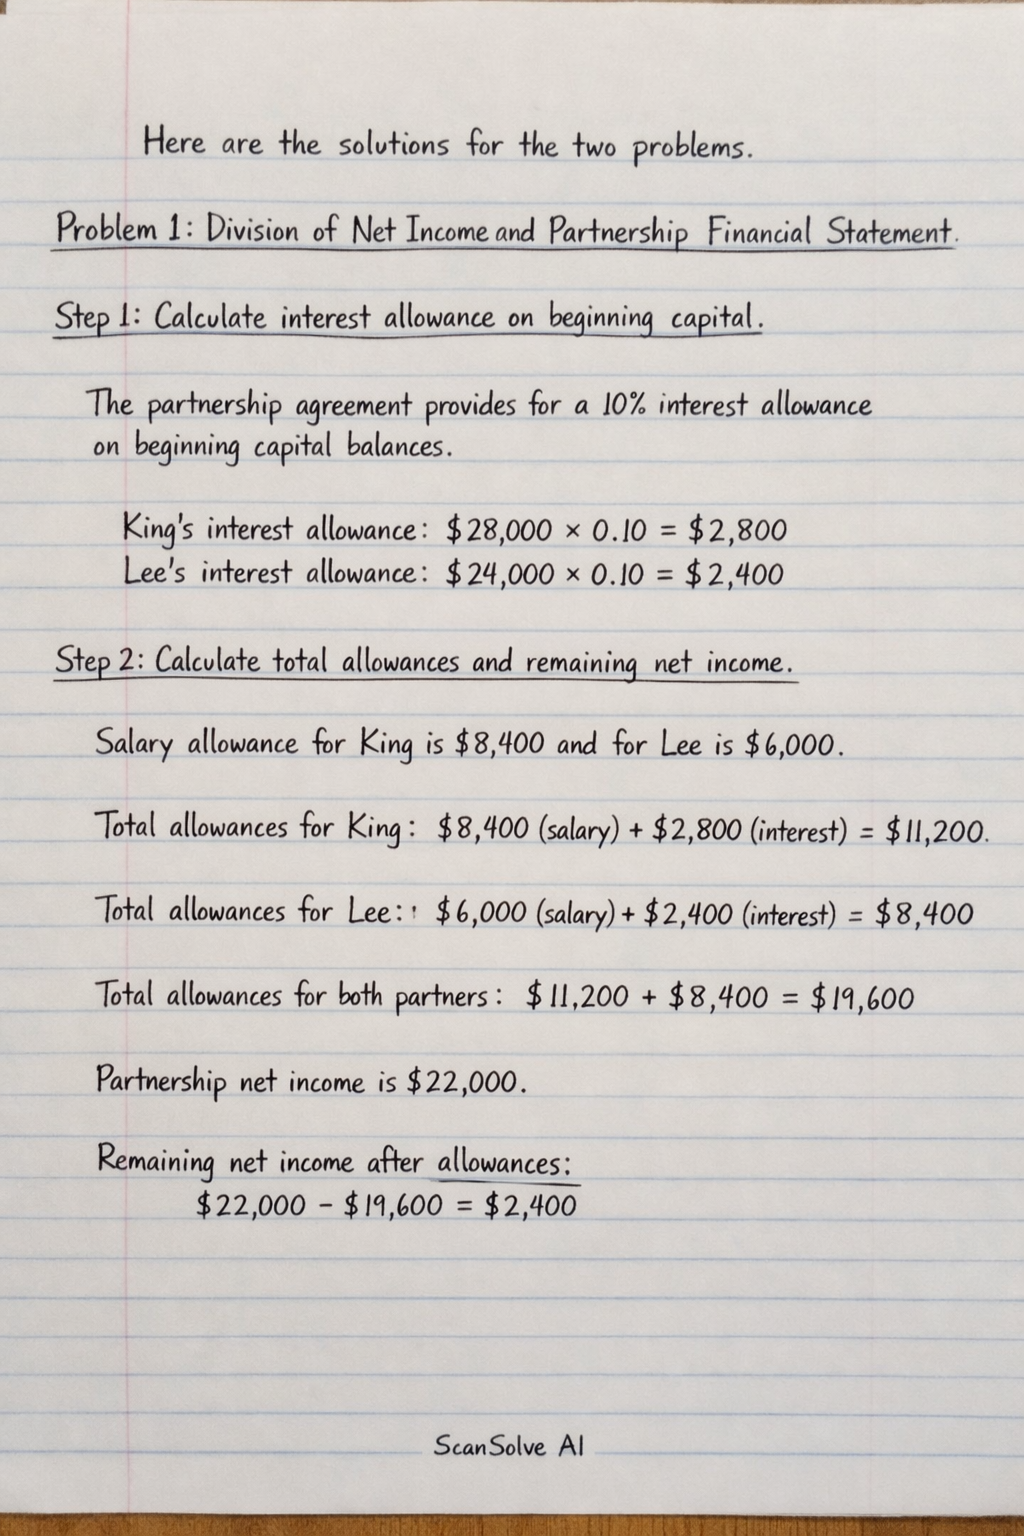
8 stepsHere are the solutions for the two problems.
: Division of Net Income and Partnership Financial Statement
Calculate interest allowance on beginning capital.
The partnership agreement provides for a 10% interest allowance on beginning capital balances.
King's interest allowance: Lee's interest allowance:Calculate total allowances and remaining net income.
Salary allowance for King is 6,000.
Total allowances for King: Total allowances for Lee: Total allowances for both partners: Partnership net income is22,000. Remaining net income after allowances: $$ \22,000 - $19,600 = $2,400 $$Distribute remaining net income and determine total share for each partner.
The remaining net income is distributed equally.
King's share of remaining net income: Lee's share of remaining net income: Total share of net income for King: Total share of net income for Lee:Division of Net Income:
Partner Salary Allowance Interest Allowance Remaining Income Total Share of Net Income King $8,400 $2,800 $1,200 $12,400 Lee $6,000 $2,400 $1,200 $9,600 Total $14,400 $5,200 $2,400 $22,000 Prepare the Partnership Financial Statement (Statement of Partners' Capital).
The statement of partners' capital shows the changes in each partner's capital account over the period.
Kingslee Company
Statement of Partners' Capital
For the Year Ended December 31Particulars King Lee Total Capital, January 1 $28,000 $24,000 $52,000 Add: Additional Investment $2,000 $2,000 $4,000 Add: Share of Net Income $12,400 $9,600 $22,000 Capital, December 31 $42,400 $35,600 $78,000
: Partnership Liquidation Journal Entries for Sagastina
Initial Balance Sheet Analysis:
The problem states total assets are 65,000.
However, the sum of listed liabilities (16,000 Accounts Payable = 15,000 Saga + 1,200 Tina = 31,000 + 64,200.
There is an 65,000 - 800). To balance the initial balance sheet, this $800 is assumed to be unrecorded capital distributed among partners based on their income ratio (3:2:1).- Saga:
800 \times \frac{3}{6} = \400$ - Courage:
800 \times \frac{2}{6} = \266.67$ - Tina:
800 \times \frac{1}{6} = \133.33$ Adjusted initial capital balances: - Saga: 400 = $15,400
- Courage: 266.67 = $17,266.67
- Tina: 133.33 = 1,333.33
- Saga:
Record the sale of noncash assets.
Noncash assets include Accounts Receivable (35,000), and Inventory (8,000) reduces the book value of equipment.
Book value of noncash assets: The assets are sold for80,000 cash. Gain on realization: $$ \80,000 (\text{sale price}) - $60,000 (\text{book value}) = $20,000 $$ The journal entry records the cash received, removes the book value of assets, and recognizes the gain.Distribute the gain on realization to partners' capital accounts.
The gain on realization is
20,000. The income ratio is 3:2:1 (total 6 parts).
Saga's share of gain:
$$ \
20,000 \times \frac{3}{6} = $10,000 $20,000 \times \frac{2}{6} = $6,666.67 $20,000 \times \frac{1}{6} = $3,333.33 $$ The journal entry debits Gain on Realization and credits each partner's capital account.Record the payment of liabilities.
Total liabilities: Notes Payable 16,000 = $31,000. The journal entry debits the liability accounts and credits Cash.
Distribute remaining cash to partners.
First, calculate the final capital balance for each partner after distributing the gain and adjusting for the initial discrepancy:
- Saga, Capital: 10,000 (gain) = $25,400$
- Courage, Capital: 6,666.67 (gain) = $23,933.34$
- Tina, Capital: 3,333.33 (gain) = $4,666.6625,400 + 4,666.66 = $54,000$.
Next, calculate the final cash balance:
- Initial Cash: $5,000
- Add: Cash from sale of assets: $80,000
- Less: Cash paid for liabilities: $31,000
- Final Cash balance: 80,000 -
31,000 = \54,000$. The final cash balance matches the total capital to be distributed.
The journal entry debits each partner's capital account and credits Cash.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp