
We read your photo as:
Prepare the trial balance
ScanSolve AI Answer
Step-by-step solution
3 stepshere is the adjusted Trial Balance for the enterprise as at 31 May 2015, incorporating all the additional information and corrections.
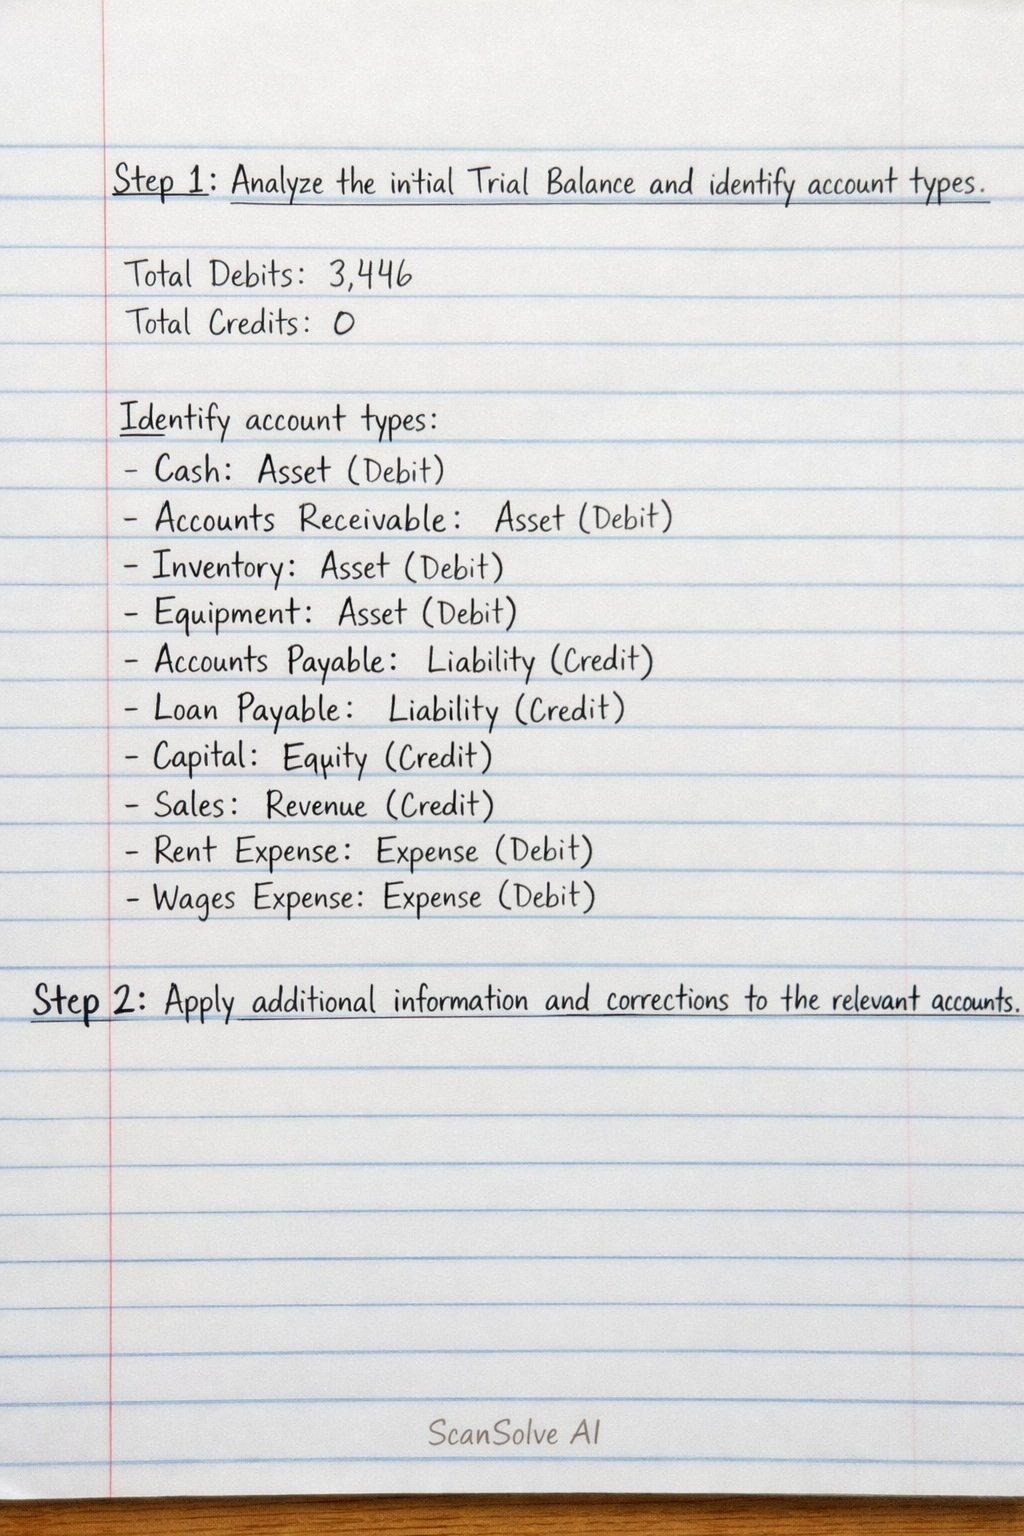
Analyze the initial Trial Balance and identify account types.
The provided initial trial balance lists various accounts with their balances. We will assume these are the unadjusted balances before considering the additional information. The total of K3,446 given in the problem is the sum of the debit column as presented, not necessarily a balanced total.
Apply additional information and corrections to the relevant accounts.
-
Initial Balances (K'000):
- Debits: Land and buildings (800), Motor vehicles (500), Office equipment (400), Inventories (Opening) (240), Receivables (60), Cash and bank (45), Sales returns (40), Purchases (900), Carriage inwards (30), Carriage outwards (38), Salaries (210), Suspense a/c (12), Office rent (48), Discount allowed (23), Office expenses (139), Distribution expenses (72), Utility expenses (25), Bank charges (14), Interest expense (45).
- Credits: Capital (800), Acc. dep. L&B (50), Acc. dep. MV (120), Acc. dep. OE (70), Prov. for doubtful receivables (4), Payables (42), Bank loan (500), Sales (1,650), Purchase returns (34), Discount received (31).
-
(1) Inventories as at 31 May 2015 were K60,000.
- Closing Inventory: K60 (Debit). The opening inventory of K240 is removed from the trial balance and will be used in the income statement.
-
(2) Depreciation:
- Building 2% on cost (cost K500): Depreciation = .
- Depreciation Expense (Dr) K10.
- Accumulated Depreciation - Land and Buildings (Cr) K10. (New balance: )
- Motor vehicle 20% on reducing balance: NBV = . Depreciation = .
- Depreciation Expense (Dr) K76.
- Accumulated Depreciation - Motor Vehicles (Cr) K76. (New balance: )
- Equipment 25% on reducing balance: NBV = . Depreciation = .
- Depreciation Expense (Dr) K82.5.
- Accumulated Depreciation - Office Equipment (Cr) K82.5. (New balance: )
- Total Depreciation Expense: (Debit).
- Building 2% on cost (cost K500): Depreciation = .
-
(3) Prepaid rent was K8,000.
- Prepaid Rent (Dr) K8.
- Office Rent (Cr) K8. (New balance: )
-
(4) Provision for doubtful debts to be set at K10,000.
- Current provision: K4. Required: K10. Increase needed: .
- Provision for Doubtful Debts Expense (Dr) K6.
- Provision for Doubtful Debts (Cr) K6. (New balance: )
-
(5) Errors:
- (1) Credit sales K20,000 not entered:
- Receivables (Dr) K20. (New balance: )
- Sales (Cr) K20. (New balance: )
- (2) Distribution costs K6,000 included under office expenses:
- Distribution Expenses (Dr) K6. (New balance: )
- Office Expenses (Cr) K6. (New balance: )
- (3) Interest on loan not fully accounted (recorded K45,000). Loan K500 at 15%:
- Total interest due: .
- Under-recorded interest: .
- Interest Expense (Dr) K30. (New balance: )
- Accrued Interest (Cr) K30.
- (4) Cheque K12,000 paid to supplier recorded in cash book but not payables:
- Payables (Dr) K12. (New balance: )
- Suspense Account (Cr) K12. (New balance: )
- (1) Credit sales K20,000 not entered:
-
Prepare the Adjusted Trial Balance.
The trial balance does not balance. The difference is K150 (Debit total K3,773.5 - Credit total K3,623.5). This indicates that there might be an uncorrected error or an initial imbalance in the problem's provided figures beyond what the suspense account addressed. However, all adjustments have been applied as per the instructions.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Accounting Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp