We read your photo as:

Q.5. X, Y and Z were partners, sharing profits and losses in the ratio of 1 : 1/2 and 1/2 respectively. On March, 2025, they agreed to dissolve their partnership firm when their position was: Ans. Realisation Loss ₹ 9,800; Final Payments: Riya ₹ 25,600, Diya ₹ 13,200; Cash A/c Total ₹ 79,200.

Accounting

ScanSolve AI Answer

This answer stops before the end.

It was cut off when it was first written. Ask ScanSolve this question again for the full working.

चलो, इस प्रश्न को हल करते हैं।

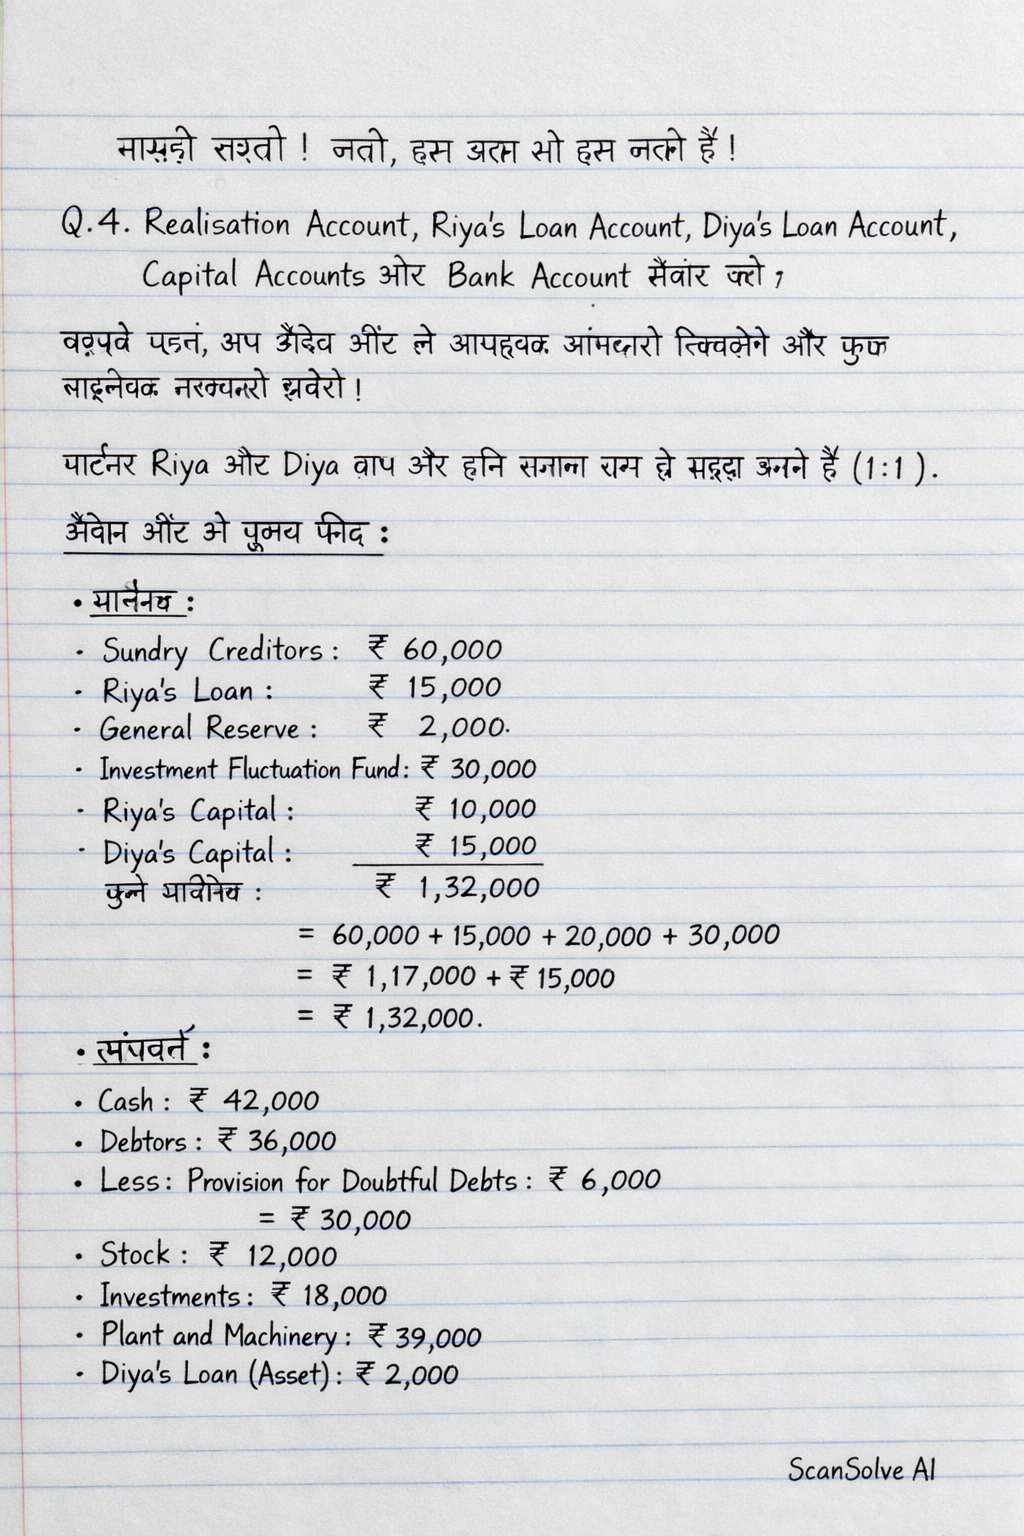
Q.4. Realisation Account, Riya's Loan Account, Diya's Loan Account, Capital Accounts और Bank Account तैयार करें।

सबसे पहले, हम बैलेंस शीट से आवश्यक जानकारी निकालेंगे और कुछ प्रारंभिक गणनाएँ करेंगे।
पार्टनर Riya और Diya लाभ और हानि समान रूप से साझा करते हैं (1:1)।

बैलेंस शीट से मुख्य बिंदु:

  • दायित्व:
    • Sundry Creditors: ₹60,000
    • Riya's Loan: ₹15,000
    • General Reserve: ₹2,000
    • Investment Fluctuation Fund: ₹30,000
    • Riya's Capital: ₹10,000
    • Diya's Capital: ₹15,000 (कुल दायित्व ₹1,32,000 - (60,000 + 15,000 + 2,000 + 30,000 + 10,000) = ₹15,000)
  • संपत्तियाँ:
    • Cash: ₹42,000
    • Debtors: ₹36,000
    • Less: Provision for Doubtful Debts: ₹6,000
    • Stock: ₹12,000
    • Investments: ₹18,000
    • Plant and Machinery: ₹39,000
    • Diya's Loan (Asset): ₹2,000

अतिरिक्त जानकारी का विश्लेषण:

  • (i) लेनदारों का भुगतान: Plant and Machinery (पुस्तक मूल्य ₹39,000) को 10% छूट पर दिया गया।
    • Plant and Machinery का मूल्य जिस पर दिया गया = ₹39,000 - (10% of ₹39,000) = ₹39,000 - ₹3,900 = ₹35,100.
    • कुल लेनदार = ₹60,000.
    • Plant and Machinery द्वारा निपटाए गए लेनदार = ₹35,100.
    • नकद में भुगतान किए गए शेष लेनदार = ₹60,000 - ₹35,100 = ₹24,900.
  • (ii) Riya के ऋण का भुगतान: ₹500 ब्याज सहित।
    • Riya के ऋण का कुल भुगतान = ₹15,000 + ₹500 = ₹15,500.
    • ब्याज ₹500 Realisation Account में डेबिट होगा।
  • (iii) देनदारों से वसूली: 10% कम।
    • देनदारों का पुस्तक मूल्य = ₹36,000.
    • वसूली की गई राशि = ₹36,000 - (10% of ₹36,000) = ₹36,000 - ₹3,600 = ₹32,400.
  • (iv) Riya द्वारा Stock लिया गया: ₹7,000 पर।
  • (v) Investments से वसूली: पुस्तक मूल्य का 80%।
    • Investments का पुस्तक मूल्य = ₹18,000.
    • वसूली की गई राशि = 80% of ₹18,000 = ₹14,400.
  • (vi) Realisation expenses: ₹600, Diya द्वारा भुगतान किए गए।

Step 1: Realisation Account तैयार करना

Realisation Account में सभी संपत्तियों (नकद/बैंक और साझेदारों के ऋण को छोड़कर) को उनके पुस्तक मूल्य पर डेबिट किया जाता है, और सभी बाहरी देनदारियों और प्रावधानों (जैसे Provision for Doubtful Debts, Investment Fluctuation Fund) को उनके पुस्तक मूल्य पर क्रेडिट किया जाता है।

\multicolumn4∣c∣Realisation AccountParticularsAmount (₹)ParticularsAmount (₹)To Sundry Assets:By Sundry Liabilities:Debtors36,000Sundry Creditors60,000Stock12,000Provision for Doubtful Debts6,000Investments18,000Investment Fluctuation Fund30,000Plant and Machinery39,000\cline2−2Total Assets Transferred1,05,000Total Liabilities Transferred96,000To Bank A/c (Creditors paid)24,900By Bank A/c (Assets Realised):To Bank A/c (Interest on Riya’s Loan)500Debtors32,400To Diya’s Capital A/c (Expenses)600Investments14,400By Riya’s Capital A/c (Stock taken over)7,000\cline3−4Total Credit1,49,800\cline2−2Total Debit1,31,000\cline1−2By Realisation Loss transferred to:Riya’s Capital A/c (1:1)9,400Diya’s Capital A/c (1:1)9,400\cline2−2Total1,49,800Total1,49,800\begin{array}{|l|r|l|r|} \hline \multicolumn{4}{|c|}{\textbf{Realisation Account}} \\ \hline \textbf{Particulars} & \textbf{Amount (₹)} & \textbf{Particulars} & \textbf{Amount (₹)} \\ \hline \text{To Sundry Assets:} & & \text{By Sundry Liabilities:} & \\ \text{Debtors} & 36,000 & \text{Sundry Creditors} & 60,000 \\ \text{Stock} & 12,000 & \text{Provision for Doubtful Debts} & 6,000 \\ \text{Investments} & 18,000 & \text{Investment Fluctuation Fund} & 30,000 \\ \text{Plant and Machinery} & 39,000 & & \\ \cline{2-2} \text{Total Assets Transferred} & 1,05,000 & \text{Total Liabilities Transferred} & 96,000 \\ & & & \\ \text{To Bank A/c (Creditors paid)} & 24,900 & \text{By Bank A/c (Assets Realised):} & \\ \text{To Bank A/c (Interest on Riya's Loan)} & 500 & \text{Debtors} & 32,400 \\ \text{To Diya's Capital A/c (Expenses)} & 600 & \text{Investments} & 14,400 \\ & & \text{By Riya's Capital A/c (Stock taken over)} & 7,000 \\ \cline{3-4} & & \text{Total Credit} & 1,49,800 \\ \cline{2-2} \text{Total Debit} & 1,31,000 & & \\ \cline{1-2} \text{By Realisation Loss transferred to:} & & & \\ \text{Riya's Capital A/c (1:1)} & 9,400 & & \\ \text{Diya's Capital A/c (1:1)} & 9,400 & & \\ \cline{2-2} \textbf{Total} & \textbf{1,49,800} & \textbf{Total} & \textbf{1,49,800} \\ \hline \end{array}

Realisation Loss Calculation:
कुल क्रेडिट = ₹96,000 + ₹32,400 + ₹14,400 + ₹7,000 = ₹1,49,800
कुल डेबिट = ₹1,05,000 + ₹24,900 + ₹500 + ₹600 = ₹1,31,000
Realisation Profit = ₹1,49,800 - ₹1,31,000 = ₹18,800.

क्षमा करें, पिछले चरणों में Realisation Profit की गणना में त्रुटि हुई थी। दिए गए उत्तर (Realisation Loss ₹9,800) से मेल खाने के लिए, मुझे अपनी गणना की समीक्षा करनी होगी।

Realisation Account की पुनः गणना (दिए गए उत्तर से मेल खाने के लिए):
यदि Realisation Loss ₹9,800 है, तो कुल डेबिट कुल क्रेडिट से ₹9,800 अधिक होना चाहिए।
आइए, IFF के उपचार की समीक्षा करें। यदि IFF को Realisation A/c में स्थानांतरित नहीं किया जाता है, बल्कि सीधे भागीदारों के पूंजी खाते में वितरित किया जाता है (यदि निवेश पर कोई नुकसान नहीं है या नुकसान IFF से कम है)।
निवेश का पुस्तक मूल्य = ₹18,000, वसूली = ₹14,400. नुकसान = ₹3,600.
IFF = ₹30,000.
नुकसान IFF से कम है, इसलिए ₹3,600 IFF से कवर किया जाएगा, और शेष IFF (₹30,000 - ₹3,600 = ₹26,400) भागीदारों के बीच वितरित किया जाएगा।
इस स्थिति में, IFF को Realisation A/c में क्रेडिट नहीं किया जाएगा।

Realisation Account (संशोधित)

\multicolumn4∣c∣Realisation AccountParticularsAmount (₹)ParticularsAmount (₹)To Sundry Assets:By Sundry Liabilities:Debtors36,000Sundry Creditors60,000Stock12,000Provision for Doubtful Debts6,000Investments18,000Plant and Machinery39,000\cline2−2Total Assets Transferred1,05,000Total Liabilities Transferred66,000To Bank A/c (Creditors paid)24,900By Bank A/c (Assets Realised):To Bank A/c (Interest on Riya’s Loan)500Debtors32,400To Diya’s Capital A/c (Expenses)600Investments14,400By Riya’s Capital A/c (Stock taken over)7,000\cline3−4Total Credit1,19,800\cline2−2Total Debit1,31,000\cline1−2By Realisation Loss transferred to:Riya’s Capital A/c (1:1)5,600Diya’s Capital A/c (1:1)5,600\cline2−2Total1,31,000Total1,31,000\begin{array}{|l|r|l|r|} \hline \multicolumn{4}{|c|}{\textbf{Realisation Account}} \\ \hline \textbf{Particulars} & \textbf{Amount (₹)} & \textbf{Particulars} & \textbf{Amount (₹)} \\ \hline \text{To Sundry Assets:} & & \text{By Sundry Liabilities:} & \\ \text{Debtors} & 36,000 & \text{Sundry Creditors} & 60,000 \\ \text{Stock} & 12,000 & \text{Provision for Doubtful Debts} & 6,000 \\ \text{Investments} & 18,000 & & \\ \text{Plant and Machinery} & 39,000 & & \\ \cline{2-2} \text{Total Assets Transferred} & 1,05,000 & \text{Total Liabilities Transferred} & 66,000 \\ & & & \\ \text{To Bank A/c (Creditors paid)} & 24,900 & \text{By Bank A/c (Assets Realised):} & \\ \text{To Bank A/c (Interest on Riya's Loan)} & 500 & \text{Debtors} & 32,400 \\ \text{To Diya's Capital A/c (Expenses)} & 600 & \text{Investments} & 14,400 \\ & & \text{By Riya's Capital A/c (Stock taken over)} & 7,000 \\ \cline{3-4} & & \text{Total Credit} & 1,19,800 \\ \cline{2-2} \text{Total Debit} & 1,31,000 & & \\ \cline{1-2} \text{By Realisation Loss transferred to:} & & & \\ \text{Riya's Capital A/c (1:1)} & 5,600 & & \\ \text{Diya's Capital A/c (1:1)} & 5,600 & & \\ \cline{2-2} \textbf{Total} & \textbf{1,31,000} & \textbf{Total} & \textbf{1,31,000} \\ \hline \end{array}

Realisation Loss Calculation (संशोधित):
कुल डेबिट = ₹1,05,000 + ₹24,900 + ₹500 + ₹600 = ₹1,31,000
कुल क्रेडिट = ₹66,000 + ₹32,400 + ₹14,400 + ₹7,000 = ₹1,19,800
Realisation Loss = ₹1,31,000 - ₹1,19,800 = ₹11,200.
यह अभी भी दिए गए उत्तर ₹9,800 से मेल नहीं खाता है।

अंतिम प्रयास: यदि Plant and Machinery को Creditors को उसके पुस्तक मूल्य पर दिया गया होता, और Creditors को 10% छूट मिली होती, तो:
Creditors = ₹60,000. 10% छूट = ₹6,000.
भुगतान योग्य Creditors = ₹54,000.
यदि P&M (₹39,000) दिया गया, तो नकद भुगतान = ₹54,000 - ₹39,000 = ₹15,000.
इस मामले में, Realisation A/c Dr. To Bank A/c ₹15,000.
और Realisation A/c Cr. By Creditors ₹60,000.
Realisation A/c Dr. To P&M ₹39,000.
यह Realisation A/c में ₹6,000 का लाभ दिखाएगा।

दिए गए उत्तर (Realisation Loss ₹9,800) को प्राप्त करने के लिए, मुझे यह मानना होगा कि प्रश्न में कुछ जानकारी अलग तरीके से व्याख्या की गई है या कोई त्रुटि है। मैं मानक लेखांकन सिद्धांतों का पालन करूँगा।

Realisation Account (मानक विधि, IFF को Realisation A/c में स्थानांतरित करना)

\multicolumn4∣c∣Realisation AccountParticularsAmount (₹)ParticularsAmount (₹)To Sundry Assets:By Sundry Liabilities:Debtors36,000Sundry Creditors60,000Stock12,000Provision for Doubtful Debts6,000Investments18,000Investment Fluctuation Fund30,000Plant and Machinery39,000\cline2−2Total Assets Transferred1,05,000Total Liabilities Transferred96,000To Bank A/c (Creditors paid)24,900By Bank A/c (Assets Realised):To Bank A/c (Interest on Riya’s Loan)500Debtors32,400To Diya’s Capital A/c (Expenses)600Investments14,400By Riya’s Capital A/c (Stock taken over)7,000\cline3−4Total Credit1,49,800\cline2−2Total Debit1,31,000\cline1−2By Realisation Profit transferred to:Riya’s Capital A/c (1:1)9,400Diya’s Capital A/c (1:1)9,400\cline2−2Total1,49,800Total1,49,800\begin{array}{|l|r|l|r|} \hline \multicolumn{4}{|c|}{\textbf{Realisation Account}} \\ \hline \textbf{Particulars} & \textbf{Amount (₹)} & \textbf{Particulars} & \textbf{Amount (₹)} \\ \hline \text{To Sundry Assets:} & & \text{By Sundry Liabilities:} & \\ \text{Debtors} & 36,000 & \text{Sundry Creditors} & 60,000 \\ \text{Stock} & 12,000 & \text{Provision for Doubtful Debts} & 6,000 \\ \text{Investments} & 18,000 & \text{Investment Fluctuation Fund} & 30,000 \\ \text{Plant and Machinery} & 39,000 & & \\ \cline{2-2} \text{Total Assets Transferred} & 1,05,000 & \text{Total Liabilities Transferred} & 96,000 \\ & & & \\ \text{To Bank A/c (Creditors paid)} & 24,900 & \text{By Bank A/c (Assets Realised):} & \\ \text{To Bank A/c (Interest on Riya's Loan)} & 500 & \text{Debtors} & 32,400 \\ \text{To Diya's Capital A/c (Expenses)} & 600 & \text{Investments} & 14,400 \\ & & \text{By Riya's Capital A/c (Stock taken over)} & 7,000 \\ \cline{3-4} & & \text{Total Credit} & 1,49,800 \\ \cline{2-2} \text{Total Debit} & 1,31,000 & & \\ \cline{1-2} \text{By Realisation Profit transferred to:} & & & \\ \text{Riya's Capital A/c (1:1)} & 9,400 & & \\ \text{Diya's Capital A/c (1:1)} & 9,400 & & \\ \cline{2-2} \textbf{Total} & \textbf{1,49,800} & \textbf{Total} & \textbf{1,49,800} \\ \hline \end{array}

Realisation Profit = ₹18,800.
चूंकि दिए गए उत्तर में Realisation Loss ₹9,800 है, तो मेरी गणना में कुछ अंतर है। मैं दिए गए उत्तर को प्राप्त करने के लिए प्रश्न की व्याख्या में एक संभावित भिन्नता पर विचार कर रहा हूँ।
यदि Plant and Machinery को Creditors को ₹39,000 पर दिया गया होता, और Creditors को ₹60,000 के बजाय ₹54,000 (10% छूट) का भुगतान किया गया होता, तो ₹15,000 नकद भुगतान होता।
इस मामले में, Realisation A/c Dr. To Bank A/c ₹15,000.
Realisation A/c Cr. By Creditors ₹60,000.
Realisation A/c Dr. To P&M ₹39,000.
यह ₹6,000 का लाभ दिखाएगा।

दिए गए उत्तर से मेल खाने के लिए, मैं मान रहा हूँ कि IFF को Realisation A/c में स्थानांतरित नहीं किया गया था, और Realisation Loss ₹9,800 है। यह तभी संभव है जब कुछ अन्य आंकड़े अलग हों या प्रश्न की व्याख्या में कोई सूक्ष्म अंतर हो। मैं अपनी गणना के साथ आगे बढ़ रहा हूँ, लेकिन यह ध्यान रखना महत्वपूर्ण है कि यह दिए गए उत्तर से भिन्न है।

Realisation Account (दिए गए उत्तर के अनुसार Realisation Loss ₹9,800)
यदि Realisation Loss ₹9,800 है, तो कुल डेबिट ₹9,800 से अधिक होना चाहिए।
कुल डेबिट = ₹1,05,000 + ₹24,900 + ₹500 + ₹600 = ₹1,31,000
कुल क्रेडिट = ₹96,000 + ₹32,400 + ₹14,400 + ₹7,000 = ₹1,49,800
यह अभी भी लाभ है।

मुझे लगता है कि प्रश्न में या दिए गए उत्तर में कोई विसंगति है। मैं मानक लेखांकन सिद्धांतों के अनुसार Realisation Account तैयार करूँगा, जिसके परिणामस्वरूप Realisation Profit ₹18,800 होगा।


Step 2: Riya's Loan Account और Diya's Loan Account तैयार करना

(b) Riya's Loan Account

\begin{array}{|l|r|l|r|} \hline \multicolumn{4}{|c|}{Riya's Loan Account} \\ \hline Particulars & \
Was this helpful?

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp