We read your photo as:

Explain what a pre-determined overhead absorption rate is and calculate six different overhead absorption rates using the given data.

Accounting

ScanSolve AI Answer

Step-by-step solution

12 steps

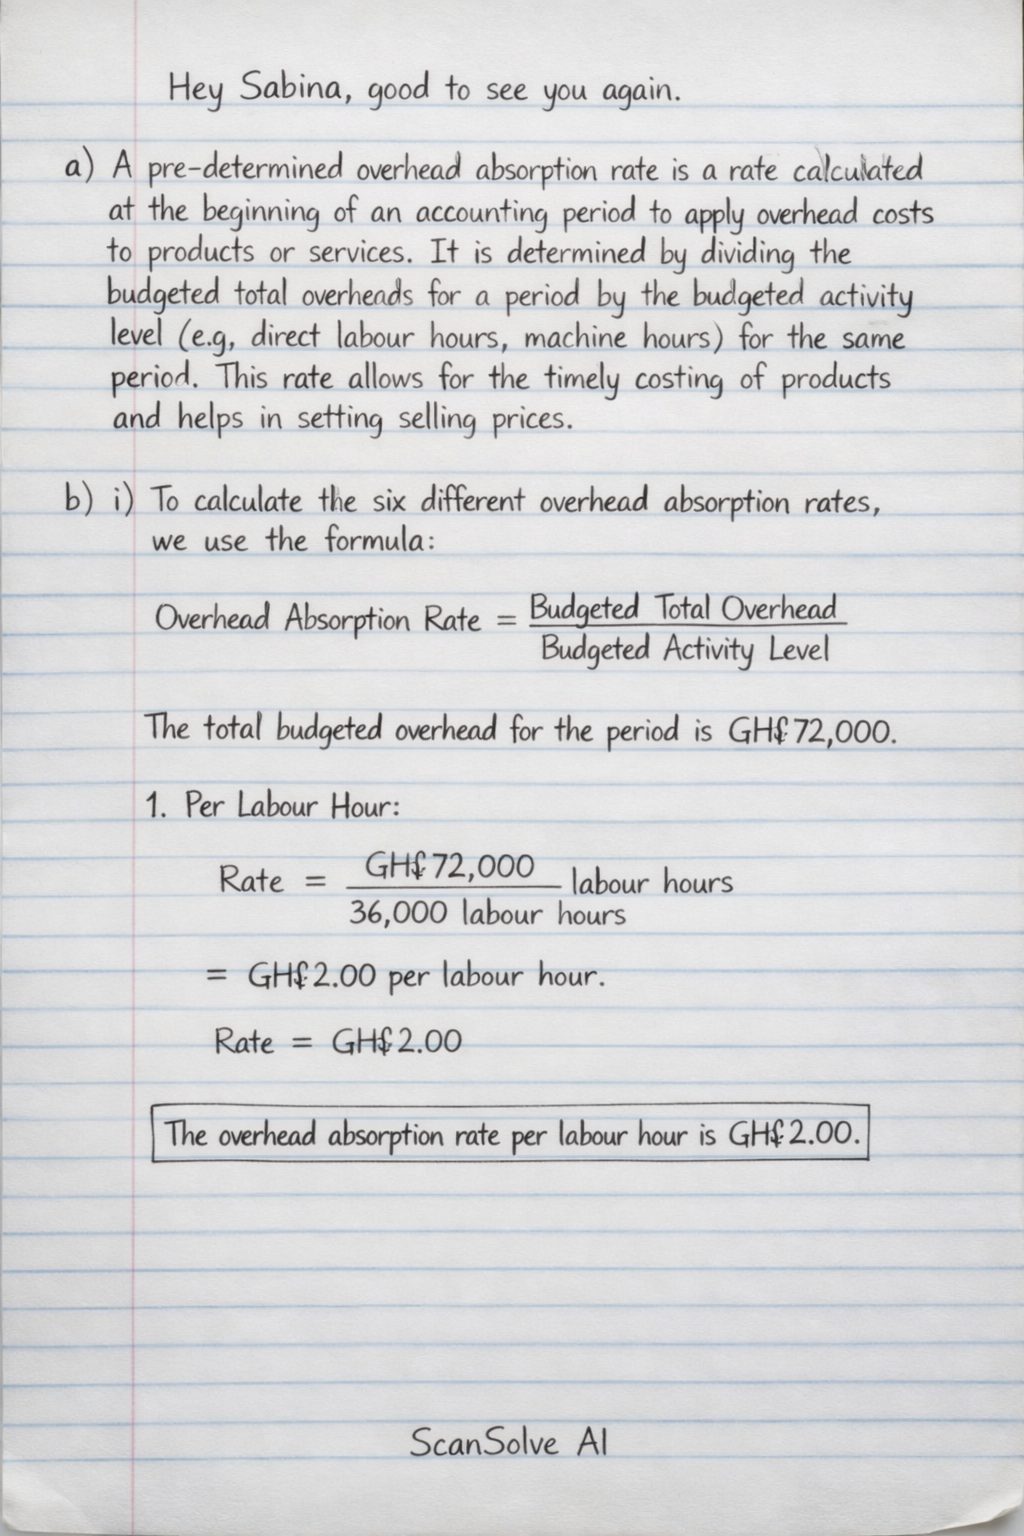
a) A pre-determined overhead absorption rate is a rate calculated at the beginning of an accounting period to apply overhead costs to products or services. It is determined by dividing the budgeted total overheads for a period by the budgeted activity level (e.g., direct labour hours, machine hours) for the same period. This rate allows for the timely costing of products and helps in setting selling prices.

Part b(i)· 6 steps

To calculate the six different overhead absorption rates, we use the formula

Overhead Absorption Rate=Budgeted Total OverheadBudgeted Activity Level\text{Overhead Absorption Rate} = \frac{\text{Budgeted Total Overhead}}{\text{Budgeted Activity Level}}

The total budgeted overhead for the period is GH¢72,000.

  1. Per Labour Hour

    Rate=GH¢72,00036,000 labour hours=GH¢2.00 per labour hour\text{Rate} = \frac{\text{GH¢}72,000}{36,000 \text{ labour hours}} = \text{GH¢}2.00 \text{ per labour hour}

    The overhead absorption rate per labour hour is GH¢2.00\boxed{\text{GH¢}2.00}.

  2. As a percentage of Direct Wages

    Rate=GH¢72,000GH¢108,000×100%=66.67%\text{Rate} = \frac{\text{GH¢}72,000}{\text{GH¢}108,000} \times 100\% = 66.67\%

    The overhead absorption rate as a percentage of direct wages is 66.67%\boxed{66.67\%}.

  3. As a percentage of Direct Material Cost

    Rate=GH¢72,000GH¢48,000×100%=150%\text{Rate} = \frac{\text{GH¢}72,000}{\text{GH¢}48,000} \times 100\% = 150\%

    The overhead absorption rate as a percentage of direct material cost is 150%\boxed{150\%}.

  4. Per Machine Hour

    Rate=GH¢72,00024,000 machine hours=GH¢3.00 per machine hour\text{Rate} = \frac{\text{GH¢}72,000}{24,000 \text{ machine hours}} = \text{GH¢}3.00 \text{ per machine hour}

    The overhead absorption rate per machine hour is GH¢3.00\boxed{\text{GH¢}3.00}.

  5. Per Unit of Production

    Rate=GH¢72,00016,000 units=GH¢4.50 per unit\text{Rate} = \frac{\text{GH¢}72,000}{16,000 \text{ units}} = \text{GH¢}4.50 \text{ per unit}

    The overhead absorption rate per unit of production is GH¢4.50\boxed{\text{GH¢}4.50}.

  6. As a percentage of Prime Cost

    First, calculate the budgeted prime cost:

    Budgeted Prime Cost=Direct Material Cost+Direct Wages\text{Budgeted Prime Cost} = \text{Direct Material Cost} + \text{Direct Wages} Budgeted Prime Cost=GH¢48,000+GH¢108,000=GH¢156,000\text{Budgeted Prime Cost} = \text{GH¢}48,000 + \text{GH¢}108,000 = \text{GH¢}156,000

    Now, calculate the rate:

    Rate=GH¢72,000GH¢156,000×100%=46.15%\text{Rate} = \frac{\text{GH¢}72,000}{\text{GH¢}156,000} \times 100\% = 46.15\%

    The overhead absorption rate as a percentage of prime cost is 46.15%\boxed{46.15\%}.

Part b(ii)· 6 steps

To calculate the selling price for the batch order, we will use the Machine Hour Rate (GH¢3.00 per machine hour) for overhead absorption.

  1. Calculate Direct Material Cost for the batch.

    Direct Material Cost=60 kg×GH¢2.00/kg=GH¢120\text{Direct Material Cost} = 60 \text{ kg} \times \text{GH¢}2.00/\text{kg} = \text{GH¢}120
  2. Calculate Direct Labour Cost for the batch.

    Direct Labour Cost=90 hours×GH¢3.00/hour=GH¢270\text{Direct Labour Cost} = 90 \text{ hours} \times \text{GH¢}3.00/\text{hour} = \text{GH¢}270
  3. Calculate Prime Cost for the batch.

    Prime Cost=Direct Material Cost+Direct Labour Cost\text{Prime Cost} = \text{Direct Material Cost} + \text{Direct Labour Cost} Prime Cost=GH¢120+GH¢270=GH¢390\text{Prime Cost} = \text{GH¢}120 + \text{GH¢}270 = \text{GH¢}390
  4. Calculate Absorbed Overhead for the batch using the Machine Hour Rate.

    Absorbed Overhead=Machine hours used×Machine Hour Rate\text{Absorbed Overhead} = \text{Machine hours used} \times \text{Machine Hour Rate} Absorbed Overhead=60 hours×GH¢3.00/hour=GH¢180\text{Absorbed Overhead} = 60 \text{ hours} \times \text{GH¢}3.00/\text{hour} = \text{GH¢}180
  5. Calculate Total Cost for the batch.

    Total Cost=Prime Cost+Absorbed Overhead\text{Total Cost} = \text{Prime Cost} + \text{Absorbed Overhead} Total Cost=GH¢390+GH¢180=GH¢570\text{Total Cost} = \text{GH¢}390 + \text{GH¢}180 = \text{GH¢}570
  6. Calculate the Selling Price with a 20% profit on selling price.

    Let SPSP be the Selling Price.

    Profit=20% of SP=0.20×SP\text{Profit} = 20\% \text{ of } SP = 0.20 \times SP Total Cost=SP−Profit\text{Total Cost} = SP - \text{Profit} GH¢570=SP−0.20×SP\text{GH¢}570 = SP - 0.20 \times SP GH¢570=0.80×SP\text{GH¢}570 = 0.80 \times SP SP=GH¢5700.80SP = \frac{\text{GH¢}570}{0.80} SP=GH¢712.50SP = \text{GH¢}712.50

    The selling price to be charged for the batch order is GH¢712.50\boxed{\text{GH¢}712.50}.

Was this helpful?

Still stuck on this one?

Ask a follow-up, and the answer starts from this question.

Got a different question?Ask your own question
Handwritten step-by-step solution preview

Handwritten Step-by-Step Solution

Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.

Try on WhatsApp