
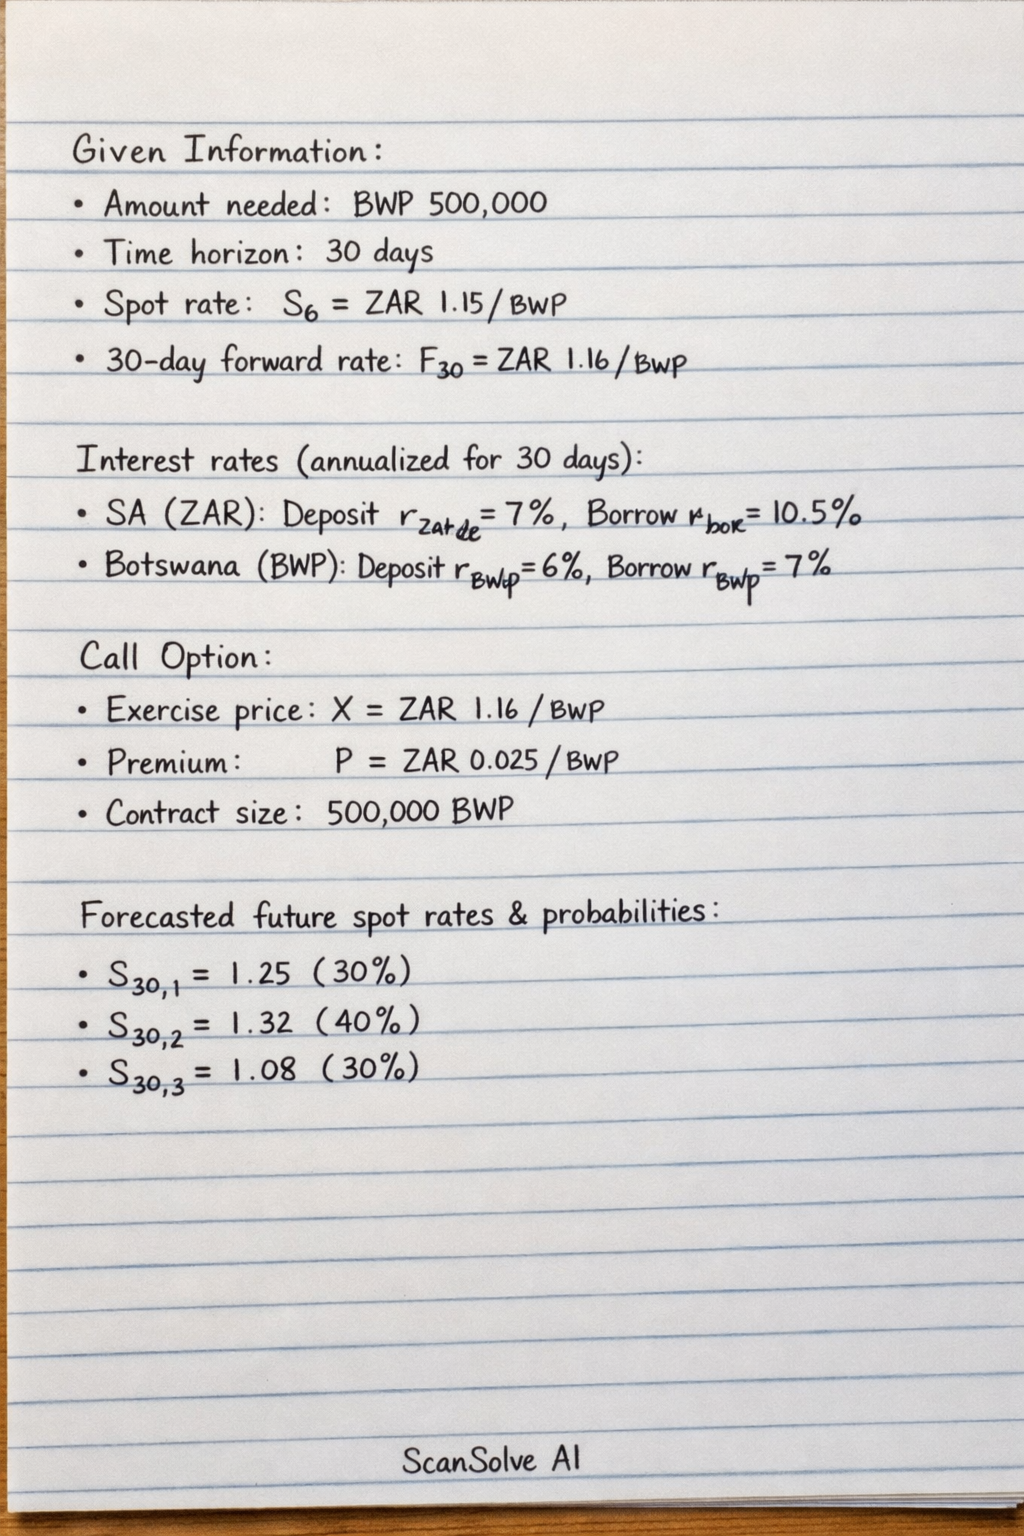
We read your photo as:
Advise the client on how to use the hedging techniques (call option, money market hedge and forward contract) to get the BWP 500 000 at the lowest cost. Show comparison between unhedged and hedged scenarios.
ScanSolve AI Answer
Step-by-step solution
5 stepsTo advise the client on the best hedging technique, we will calculate the expected cost in ZAR for each scenario: unhedged, forward contract, money market hedge, and call option. The client needs to pay BWP 500,000 in 30 days.
Given Information:
- Amount needed: BWP 500,000
- Time horizon: 30 days
- Spot rate:
- 30-day forward rate:
- Interest rates (annualized for 30 days):
- South Africa (ZAR): Deposit , Borrowing
- Botswana (BWP): Deposit , Borrowing
- Call option:
- Exercise price:
- Premium:
- Contract size: BWP 500,000
- Forecasted future spot rates () and probabilities:
- (30%)
- (40%)
- (30%)
Calculate the cost of the Unhedged Scenario
The client will buy BWP 500,000 at the future spot rate. We calculate the expected cost based on the forecasted outcomes.
Expected cost of unhedged scenario:
Calculate the cost of the Forward Contract
The client locks in the exchange rate today for a future transaction using the 30-day forward rate.
Calculate the cost of the Money Market Hedge
The strategy for paying foreign currency (BWP) in the future is:
- Calculate the present value of BWP 500,000 using the Botswana deposit rate.
- Convert this BWP amount to ZAR today using the spot rate.
- Borrow this ZAR amount in South Africa for 30 days using the South African borrowing rate.
- The total ZAR to be repaid in 30 days is the cost.
First, calculate the 30-day interest rates:
Amount of BWP to deposit today ():
Convert to ZAR today using the spot rate:
Borrow this ZAR amount for 30 days at the South African borrowing rate:
Calculate the cost of the Call Option
The client buys a call option on BWP.
Exercise price
Premium
Contract size = BWP 500,000First, calculate the future value of the premium, which is paid upfront.
Now, calculate the cost for each outcome in 30 days:
-
Outcome 1: Since , the option will be exercised.
-
Outcome 2: Since , the option will be exercised.
-
Outcome 3: Since , the option will not be exercised. The client will buy BWP at the spot rate.
Expected cost of the call option:
-
Comparison and Recommendation
Here is a summary of the expected costs for each scenario:
Hedging Technique Expected Cost (ZAR) Unhedged Scenario 613,500.00 Forward Contract 580,000.00 Money Market Hedge 577,110.04 Call Option 580,607.87 Based on the expected costs, the Money Market Hedge offers the lowest cost for the client to acquire BWP 500,000 in 30 days. This method also provides certainty regarding the future ZAR cost, similar to a forward contract, but at a more favorable rate in this specific case.
Recommendation:
The client should implement a Money Market Hedge. This involves:- Calculating the present value of BWP 500,000 using Botswana's 30-day deposit rate.
- Converting this BWP amount to ZAR today at the spot rate.
- Borrowing the equivalent ZAR amount in South Africa for 30 days at the South African borrowing rate. This strategy will result in the lowest expected ZAR cost of ZAR 577,110.04 to obtain the required BWP 500,000 in 30 days.
Still stuck on this one?
Ask a follow-up, and the answer starts from this question.
More Business/Management Questions
Handwritten Step-by-Step Solution
Get this as a handwritten image on WhatsApp — like a tutor wrote it for you.
Try on WhatsApp